Americas Surgical Equipment Market Snapshot
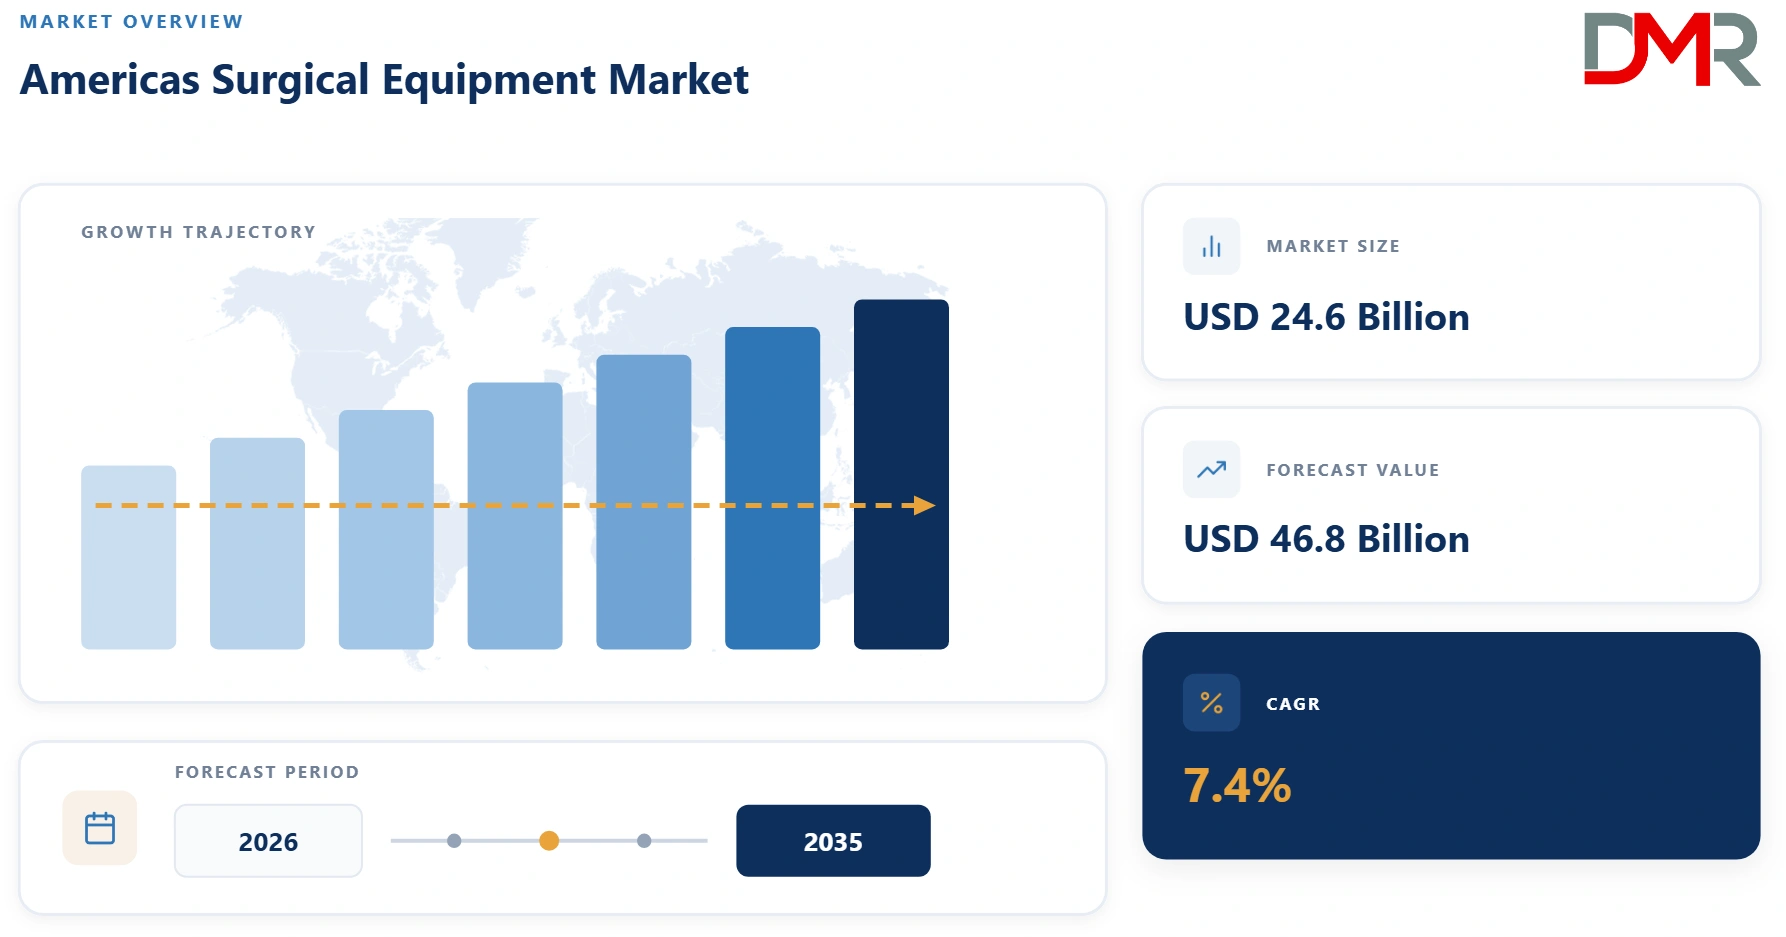
- Americas Surgical Equipment Market Size in 2026: USD 24.6 Billion
- Americas Surgical Equipment Market Size in 2035: USD 46.8 Billion
- Americas CAGR from 2026 to 2035: 7.4%
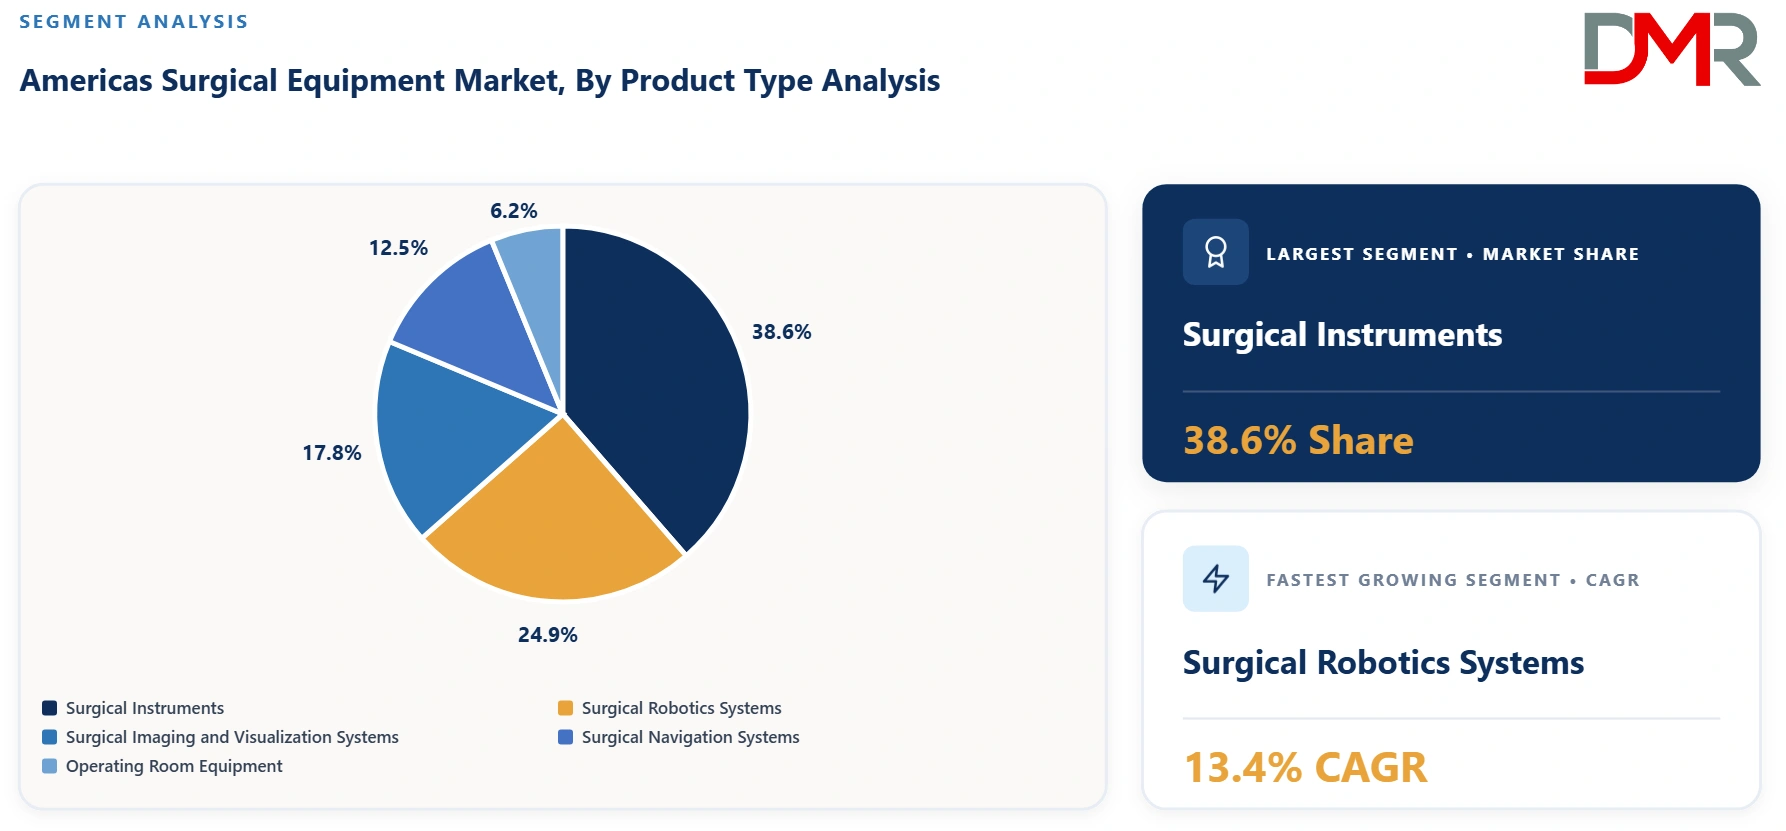
- Surgical Instruments is the leading product type segment in 2026: 38.6%
- Minimally Invasive Surgery is the leading surgery type segment in 2026: 48.3%
- General Surgery is the leading application segment in 2026: 26.8%
- Hospitals is the leading end user segment in 2026: 66.4%
What is the Americas Surgical Equipment Market and its Market Size?
The Americas Surgical Equipment Market is projected to be valued at USD 24.6 Billion in 2026 and is projected to reach USD 46.8 Billion by 2035, expanding at a CAGR of 7.4% during the forecast period.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Growth is being propelled by the region's rapidly aging population driving sustained growth in surgical procedure volumes across cardiovascular, orthopedic, and general surgery categories, continued rapid adoption of surgical robotics and minimally invasive surgical technology offering improved patient outcomes and faster recovery times, and sustained hospital and ambulatory surgical center capital investment in advanced surgical imaging, navigation, and operating room equipment across both mature North American healthcare systems and rapidly developing Latin American markets. The maturing of next-generation surgical robotics platforms expanding beyond traditional urological and gynecological applications into orthopedic, cardiovascular, and general surgery use cases, growing ambulatory surgical center capacity supporting efficient outpatient delivery of an expanding range of surgical procedures, and continued Latin American hospital infrastructure investment and surgical training capacity expansion across Brazil, Mexico, Colombia, and Argentina are reshaping the market from a largely conventional instrument-dominated category into an increasingly technology-integrated, robotics- and imaging-enabled surgical equipment industry. Investment is accelerating as device manufacturers and healthcare providers expand advanced surgical technology adoption across the region's varied and growing surgical care markets.
Use Cases
- Robot-Assisted Surgery for Urological, Gynecological, and Expanding General Surgery Applications: Hospitals and surgical centers across the United States, Canada, and leading Latin American healthcare systems deploy surgical robotics platforms for prostatectomy, hysterectomy, and an expanding range of general and colorectal surgery procedures, offering improved surgical precision and patient recovery outcomes relative to traditional open surgery.
- Advanced Imaging and Navigation-Guided Spinal and Orthopedic Surgery: Orthopedic and spine surgeons use advanced intraoperative imaging and surgical navigation systems to improve implant placement precision during joint reconstruction and spinal fusion procedures, reducing complication rates and improving surgical outcomes.
- Electrosurgical and Advanced Energy Devices for Minimally Invasive General Surgery: General surgeons across the Americas use advanced electrosurgical and energy-based devices supporting laparoscopic and other minimally invasive surgical approaches, enabling precise tissue cutting and coagulation with reduced blood loss compared to traditional surgical instrumentation.
- Cardiovascular Surgical Equipment for Structural Heart and Bypass Procedures: Cardiac surgery centers across North America and increasingly Latin America use specialized surgical instruments, imaging systems, and operating room equipment supporting complex cardiovascular procedures including coronary bypass and structural heart interventions.
Key Takeaways
- Market Size: The Americas Surgical Equipment Market is anticipated to be valued at USD 24.6 Billion in 2026 and is forecast to reach USD 46.8 Billion by 2035, expanding at a CAGR of 7.4%.
- Growth Outlook: Market expansion is sustained by the region's aging population driving surgical procedure volume growth, continued rapid adoption of surgical robotics and minimally invasive technology, and sustained capital investment in advanced surgical equipment across both North America and Latin America.
- Primary Growth Drivers: Rapidly aging populations driving surgical procedure volume growth across multiple specialty areas, continued rapid adoption of surgical robotics and minimally invasive surgical technology, expanding ambulatory surgical center capacity, and growing Latin American hospital infrastructure investment are accelerating market growth.
- By Product Type Analysis: Surgical Instruments is projected to lead the product type segment with a 38.6% share in 2026, reflecting their foundational and essential role across virtually all surgical procedure categories. Surgical Robotics Systems is the fastest-growing product type segment at 13.4% CAGR, driven by continued expansion of robotic surgery into new specialty applications.
- By Surgery Type Analysis: Minimally Invasive Surgery is expected to dominate with a 48.3% share in 2026, reflecting sustained clinical and patient preference for reduced-trauma surgical approaches. Robot-Assisted Surgery is the fastest-growing surgery type segment at 13.8% CAGR, driven by expanding robotic platform adoption across multiple surgical specialties.
- By Application Analysis: General Surgery is poised to lead with a 26.8% share in 2026, reflecting the broad and diverse range of procedures within this category. Orthopedic Surgery is the fastest-growing application segment at 8.9% CAGR, driven by the region's aging population and rising joint reconstruction procedure volumes.
- By End User Analysis: Hospitals are projected to dominate with a 66.4% share in 2026, reflecting the complex, capital-intensive nature of most surgical equipment categories. Ambulatory Surgical Centers is the fastest-growing end user segment at 10.6% CAGR, driven by continued shift of appropriate surgical procedures toward efficient outpatient delivery settings.
- By Region Analysis: North America is expected to command a 77.9% share in 2026, reflecting the scale of its healthcare system and surgical infrastructure relative to Latin America. Latin America is the fastest-growing region segment at 10.2% CAGR, driven by continued hospital infrastructure investment and surgical training capacity expansion across Brazil, Mexico, and other leading Latin American markets.
Key Drivers in the Americas Surgical Equipment Market
Rapidly Aging Populations Driving Surgical Procedure Volume Growth
The United States and Canada, alongside a gradually aging Latin American population base, continue to experience substantial growth in age-related surgical procedure demand spanning cardiovascular, orthopedic, oncological, and general surgery categories. This demographic-driven surgical procedure volume growth creates a structural, durable demand foundation for surgical equipment across the Americas, as aging populations generally require substantially higher rates of surgical intervention across multiple specialty areas than younger population segments, sustaining surgical equipment market growth independent of shorter-term healthcare spending cycles.
Continued Rapid Adoption of Surgical Robotics and Minimally Invasive Technology
Hospitals and surgical centers across the Americas continue to rapidly adopt surgical robotics platforms and minimally invasive surgical technology, extending beyond the traditional urological and gynecological applications where robotic surgery first achieved widespread clinical adoption into orthopedic, cardiovascular, general, and other surgical specialty areas. This continued technology adoption expansion reflects both maturing robotic platform capability addressing an increasing range of surgical procedure types and growing clinical evidence supporting improved patient outcomes and faster recovery associated with robot-assisted and other minimally invasive surgical approaches.
Restraints in the Americas Surgical Equipment Market
High Capital Costs of Advanced Surgical Robotics and Imaging Technology
The substantial capital investment required for advanced surgical robotics platforms, imaging systems, and navigation technology represents a meaningful restraint on the Americas Surgical Equipment Market, particularly for smaller hospitals and healthcare systems across both North America and Latin America facing more constrained capital budgets. This capital cost barrier can limit the pace of advanced surgical technology adoption among resource-constrained healthcare providers, potentially concentrating the most advanced surgical equipment capability within larger, better-capitalized hospital systems and creating disparities in advanced surgical technology access across different healthcare provider segments and geographic regions.
Growth Opportunities in the Americas Surgical Equipment Market
Expansion of Surgical Robotics Platforms into New Specialty Applications
Continued technology development expanding surgical robotics platform capability into orthopedic, cardiovascular, spine, and other surgical specialty applications beyond the traditional urological and gynecological procedure base presents a substantial opportunity for robotics manufacturers to capture growing market share as clinical adoption extends into these new specialty areas. Companies developing robotics platforms with demonstrated clinical efficacy across an expanding range of surgical procedure types can capture significant growth as hospitals continue expanding robotic surgery program scope.
Latin American Surgical Infrastructure and Training Investment
Continued healthcare infrastructure investment across Brazil, Mexico, Colombia, and Argentina, driven by both public healthcare system capacity expansion and growing private hospital sector development, presents a substantial opportunity for surgical equipment manufacturers to expand regional distribution, surgeon training support, and market development presence. Companies establishing strong distribution relationships and surgical training capability serving Latin American surgical markets can capture significant growth as these markets continue expanding advanced surgical capacity.
Trends in the Americas Surgical Equipment Market
Growing Integration of AI-Enhanced Surgical Planning and Intraoperative Decision Support
Surgical equipment manufacturers across the Americas are increasingly integrating AI-enhanced surgical planning and intraoperative decision support capability into imaging, navigation, and robotics platforms, supporting more precise preoperative planning and real-time surgical guidance. This technology integration trend reflects broader digitization of surgical care and growing surgeon interest in data-driven tools supporting improved surgical precision and outcome consistency.
Continued Shift Toward Ambulatory and Outpatient Surgical Delivery Models
The Americas Surgical Equipment Market is experiencing a continued shift in procedure delivery composition toward ambulatory surgical centers and outpatient settings for an expanding range of surgical procedures, reflecting broader healthcare system trends toward cost-effective, efficient surgical care delivery. This trend is encouraging surgical equipment manufacturers to develop products and platforms specifically suited to efficient ambulatory surgical workflows, including more compact and cost-effective equipment configurations appropriate for outpatient facility settings.
Research Scope and Analysis
The Americas Surgical Equipment Market is segmented by product type, surgery type, application, end user, and region, covering surgical instruments, robotics systems, imaging and navigation systems, operating room equipment, and cardiovascular, orthopedic, and general surgery applications across North American and Latin American country markets.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Product Type Analysis
Surgical Instruments is projected to dominate the Americas Surgical Equipment Market with 38.6% share in 2026, reflecting handheld instruments, electrosurgical devices, and sutures and staplers' foundational and essential role across virtually all surgical procedure categories throughout the region's healthcare systems. Surgical Robotics Systems is expected to register the highest CAGR of 13.4% during 2026-2035, driven by continued expansion of robotic surgery platforms into new specialty applications spanning orthopedic, cardiovascular, and general surgery beyond traditional urological and gynecological use cases.
By Surgery Type Analysis
Minimally Invasive Surgery is anticipated to dominate the Americas Surgical Equipment Market by surgery type, accounting for 48.3% share in 2026, reflecting sustained clinical and patient preference for reduced-trauma surgical approaches offering faster recovery and reduced complication risk relative to traditional open surgery. Robot-Assisted Surgery is projected to register the highest CAGR of 13.8% between 2026 and 2035, driven by expanding robotic platform adoption and clinical evidence supporting robotic surgery across multiple surgical specialties.
By Application Analysis
General Surgery is projected to lead the Americas Surgical Equipment Market with an estimated 26.8% share in 2026, reflecting the broad and diverse range of abdominal, colorectal, and other general surgical procedures conducted across the region's hospital and ambulatory surgical center infrastructure. Orthopedic Surgery is expected to register the fastest CAGR of 8.9% through 2035, driven by the region's aging population and correspondingly rising joint reconstruction and spinal surgery procedure volumes.
By End User Analysis
Hospitals are projected to lead the Americas Surgical Equipment Market with an estimated 66.4% share in 2026, reflecting the complex, capital-intensive nature of most surgical equipment categories requiring comprehensive hospital-based surgical and support infrastructure. Ambulatory Surgical Centers are expected to register the fastest CAGR of 10.6% through 2035, driven by continued shift of appropriate surgical procedures toward efficient, lower-cost outpatient delivery settings across North American healthcare systems.
The Americas Surgical Equipment Market Report is segmented based on the following:
By Product Type
- Surgical Instruments
- Handheld Instruments
- Electrosurgical Devices
- Sutures and Staplers
- Surgical Robotics Systems
- Surgical Imaging and Visualization Systems
- Surgical Navigation Systems
- Operating Room Equipment
- Surgical Tables
- Surgical Lights
- Others
By Surgery Type
- Minimally Invasive Surgery
- Open Surgery
- Robot-Assisted Surgery
By Application
- Cardiovascular Surgery
- Orthopedic Surgery
- Neurosurgery
- General Surgery
- Gynecological Surgery
- Urological Surgery
- Others
By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Surgical Clinics
By Region Analysis
North America, comprising the United States and Canada, is projected to lead the Americas Surgical Equipment Market with an estimated 77.9% share in 2026, reflecting the substantial scale of its hospital systems, healthcare expenditure, and established surgical infrastructure and technology adoption relative to Latin America. Latin America, comprising Mexico, Brazil, Colombia, Argentina, and the Rest of LATAM, is expected to register the fastest CAGR of 10.2% through 2035, driven by continued hospital infrastructure investment, growing private healthcare sector development, and expanding surgical training capacity across the region's leading economies.
By Region
North America
Latin America
- Mexico
- Brazil
- Colombia
- Argentina
- Rest of LATAM
Technology Analysis
Technology development is central to the trajectory of the Americas Surgical Equipment Market as companies invest in next-generation surgical robotics platforms expanding clinical application breadth, AI-enhanced surgical planning and intraoperative decision support software, and advanced imaging and navigation systems improving surgical precision across complex procedures. Growing use of augmented reality-based surgical visualization is supporting more intuitive intraoperative guidance for surgeons across multiple specialty areas. Opportunities are expanding for companies developing more compact, cost-effective surgical robotics and imaging configurations suited to ambulatory surgical center and Latin American hospital market economics, as well as digital surgical training and simulation technology supporting workforce development across the region. However, achieving broad access to advanced surgical technology amid high capital cost barriers remains an ongoing consideration for smaller and resource-constrained healthcare providers.
Investment and White Space Analysis
Investment opportunities in the Americas Surgical Equipment Market are expanding alongside the region's aging population and associated surgical procedure volume growth, continued rapid surgical robotics and minimally invasive technology adoption, and expanding healthcare infrastructure investment across both North America and Latin America. Significant white space exists in surgical robotics platform expansion into new specialty applications, cost-effective equipment configurations suited to ambulatory and Latin American market economics, and AI-enhanced surgical planning and decision support technology. Companies with strong clinical evidence generation capability, established relationships with major hospital systems across both North and Latin America, and technology adaptable across varied healthcare delivery settings are positioned to capture premium, longer-duration growth opportunities. However, high capital costs of advanced surgical robotics and imaging technology can constrain adoption pace among smaller and resource-constrained healthcare providers, particularly across Latin America.
Competitive Landscape
The Americas Surgical Equipment Market is moderately consolidated and increasingly competitive, comprising large diversified global medical device companies with substantial Americas operations, specialized surgical robotics and imaging technology companies, and regional Latin American medical device distributors and manufacturers. Competition centers on surgical robotics and imaging technology innovation and clinical outcomes data, established relationships with major North American hospital systems and group purchasing organizations, surgeon training and clinical support capability, and Latin American market distribution and regulatory expertise. Large diversified global companies benefit from substantial research and development resources and broad surgical equipment portfolios, while specialized robotics and imaging companies compete through deep technical expertise in specific technology categories. Companies increasingly differentiate through clinical training support and platform versatility across multiple surgical specialties rather than instrument breadth alone.
Some of the prominent players in the Americas Surgical Equipment Market are:
- Intuitive Surgical
- Medtronic
- Stryker Corporation
- Johnson & Johnson MedTech
- Becton, Dickinson and Company (BD)
- Zimmer Biomet
- Smith+Nephew
- Boston Scientific Corporation
- Olympus Corporation
- CONMED Corporation
- Karl Storz
- Getinge Group
- Baxter International
- STERIS plc
- B. Braun Melsungen
- Globus Medical
- Asensus Surgical
- Baumer S.A. (Brazil)
- Grupo Notre Dame Intermédica (Latin America Distribution Partnerships)
- Other Key Players
Recent Developments
- September 2026: Announced a strategic partnership with Cornerstone Robotics, including a USD 700 million investment, to expand access to robotic-assisted surgery and strengthen its surgical robotics portfolio.
- September 2026: Introduced SportSuite Vision, an FDA-authorized surgical application for Apple Vision Pro, and completed its first hip arthroscopy procedure using the spatial-computing platform at Duke HealthStryker
- August 2026: Launched the POWERSEAL Open Extended Jaw Sealer/Divider commercially in the U.S. and Canada, expanding its advanced bipolar surgical energy portfolio for multiple open-surgery specialtiesOlympus America
- July 2026: Received FDA De Novo authorization for the OTTAVA Robotic Surgical System, a table-integrated soft-tissue robotic platform authorized for multiple general surgery procedures in the U.S.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 24.6 Bn |
| Forecast Value (2035) |
USD 46.8 Bn |
| CAGR (2026–2035) |
7.4% |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Product Type, By Surgery Type, By Application, By End User |
| Regional Coverage |
North America – The US and Canada; Latin America – Mexico, Brazil, Colombia, Argentina, Rest of LATAM |
Frequently Asked Questions
How big is the Americas Surgical Equipment Market?
▾ The Americas Surgical Equipment Market is poised to be valued at USD 24.6 Billion in 2026 and is projected to reach USD 46.8 Billion by 2035, reflecting the region's aging population and continued rapid adoption of surgical robotics and minimally invasive surgical technology.
What is the CAGR of the Americas Surgical Equipment Market from 2026 to 2035?
▾ The market is projected to expand at a compound annual growth rate (CAGR) of 7.4% between 2026 and 2035, supported by demographic-driven surgical procedure volume growth, continued robotics adoption, and expanding Latin American healthcare infrastructure investment.
What factors are driving the growth of the Americas Surgical Equipment Market?
▾ Growth is driven by rapidly aging populations driving surgical procedure volume growth across multiple specialty areas, continued rapid adoption of surgical robotics and minimally invasive surgical technology, expanding ambulatory surgical center capacity, and growing Latin American hospital infrastructure investment.
What are the major trends in the Americas Surgical Equipment Market?
▾ Major trends include growing integration of AI-enhanced surgical planning and intraoperative decision support, continued shift toward ambulatory and outpatient surgical delivery models, and rising expansion of surgical robotics platforms into new specialty applications.
Who are the key players in the Americas Surgical Equipment Market?
▾ Key market participants include Intuitive Surgical, Medtronic, Stryker Corporation, Johnson & Johnson MedTech, and Becton, Dickinson and Company (BD), among other global and regional surgical equipment manufacturers.
How is the Americas Surgical Equipment Market segmented?
▾ The market is segmented by product type, surgery type, application, end user, and region, with North America comprising the United States and Canada, and Latin America comprising Mexico, Brazil, Colombia, Argentina, and the Rest of LATAM.