Chile Food Processing Equipment Market Snapshot
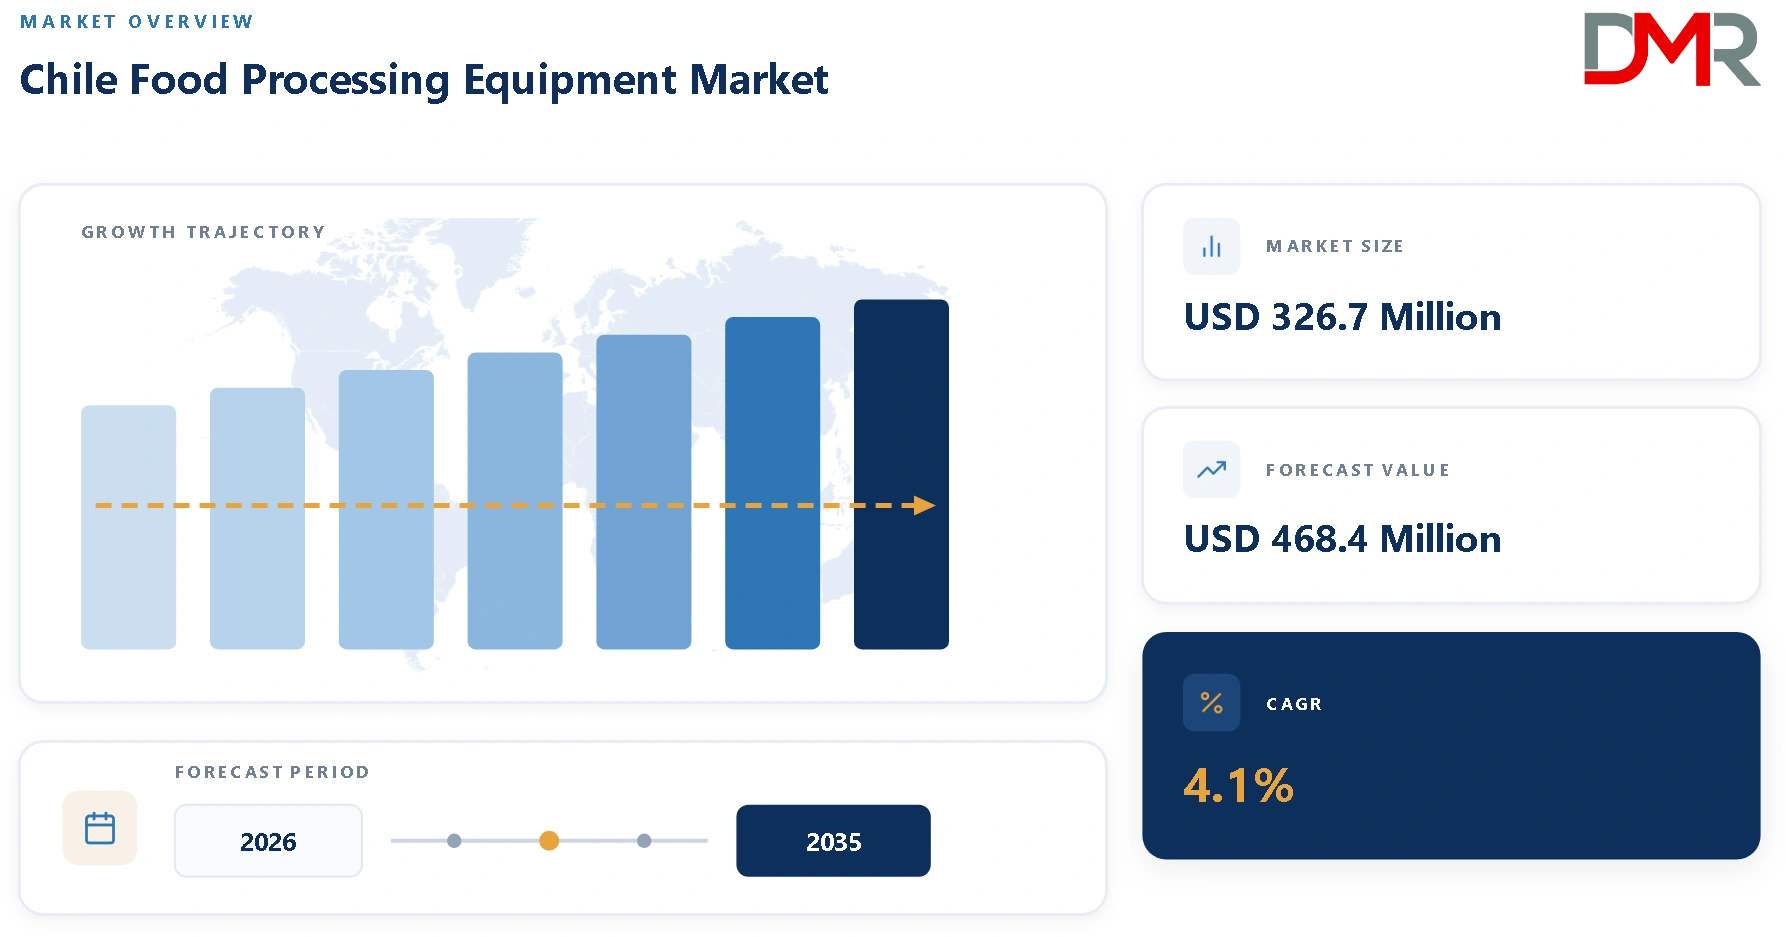
- Market Size in 2026: USD 326.7 million
- Market Size in 2035: USD 468.4 million
- CAGR, 2026-2035: 4.1%
- Leading Equipment Type in 2026: Processing Equipment, 52% share
- Leading Mode of Operation in 2026: Automatic, 58% share
- Leading Food Category in 2026: Beverages, 22% share
- Fastest-Growing Segment: Automatic Equipment, 6.2% CAGR
- Second-largest Equipment Type: Packaging Equipment, 30%
- Second-largest Food Category: Meat, Poultry and Seafood, 21%
- Largest End-User Group: Large-Scale Food Processors, 67%
What is the Chile Food Processing Equipment and its Market Size?
The Chile Food Processing Equipment Market is estimated at USD 326.7 million in 2026 and is forecast to reach approximately USD 468.4 million by 2035, representing a 4.1% CAGR.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
The Chile Food Processing Equipment Market comprises machinery, integrated production lines, process-control systems and supporting equipment used to transform agricultural, livestock, seafood and other food inputs into processed, packaged and commercially saleable products. Equipment includes processing machinery, packaging systems, material-handling equipment, cooking and cooling systems, and cleaning and sanitation equipment. The market serves dairy, meat and seafood, bakery and confectionery, beverages, fruit and vegetable processing, grain milling and other food manufacturers. Its principal value proposition is to improve throughput, product consistency, food safety, labor productivity, shelf life and resource efficiency while enabling Chilean producers to compete in domestic and export markets.
Use Cases
- Dairy processing: Pasteurization, homogenization, separation, filling and cooling for milk, yogurt, cheese and dairy alternatives.
- Meat and seafood processing: Cutting, deboning, grinding, marinating, cooking, freezing, weighing and hygienic packaging.
- Bakery and confectionery: Mixing, dough preparation, baking, cooling, depositing, forming and automated packaging.
- Beverage production: Blending, filtration, pasteurization, filling, capping, labeling and secondary packaging for beverages.
- Fruit and vegetable processing: Washing, sorting, cutting, pulping, freezing, dehydration and aseptic or flexible packaging.
- Grain and ingredient processing: Cleaning, milling, grinding, extrusion, weighing, conveying and bagging of grains and ingredients.
Key Takeaways
- Market size: The market is estimated at USD 326.7 million in 2026, increasing to USD 468.4 million by 2035.
- Growth rate: The forecast 4.1% CAGR reflects steady replacement demand combined with capacity expansion and technology upgrades.
- Growth drivers: Export-oriented food production, automation, labor productivity, food safety, sustainability and demand for convenient processed foods.
- Segment dominance: Processing equipment leads with 52%, while automatic systems account for 58% of equipment demand.
- Food-category leadership: Beverages represent the largest food-category application at 22%, closely followed by meat, poultry and seafood at 21%.
- Fastest growth: Automatic equipment is forecast to expand at 6.2% CAGR, substantially above manual systems, as processors seek higher throughput and lower unit labor costs.
How AI/Gen AI is Transforming the Chile Food Processing Equipment Market?
AI, IoT and cloud-connected automation are shifting Chilean food-processing equipment from standalone machinery toward connected production systems. Sensors increasingly monitor temperature, pressure, flow, vibration, energy consumption and product quality, while cloud platforms aggregate operational data across production lines. GEA, for example, markets connected machines through GEA Cloud and describes AI-enabled monitoring as a mechanism for improving uptime and sustainable industrial performance. Tetra Pak similarly launched its Factory OS platform in 2025 to provide contextualized real-time production information and prepare food factories for AI-enabled decision-making.
The principal benefits are predictive maintenance, reduced unplanned downtime, improved yield, lower energy and water consumption, faster changeovers and more consistent product quality. Tetra Pak reports that highly automated beverage factories in its benchmarking can achieve materially higher equipment effectiveness and lower waste and packaging-line downtime than less automated plants.
Key Drivers in the Chile Food Processing Equipment Market
Growing Demand for Processed and Convenience Foods:
Changing consumer lifestyles, urbanization and increasing demand for convenient, ready-to-eat and value-added food products are supporting investment in modern processing machinery in Chile. Food manufacturers are expanding product portfolios across beverages, dairy, bakery products, processed meats, seafood, fruits and vegetables. The country's strong food-processing and export orientation further encourages manufacturers to improve production capacity, product consistency and shelf life. As processors move toward higher-value products, demand is increasing for advanced cutting, mixing, blending, cooking, cooling, filling and packaging systems.
Increasing Adoption of Automation and Digital Technologies:
Food processors are increasingly adopting automated machinery to improve productivity, reduce dependence on manual labor and achieve consistent product quality. Automation is being incorporated into processing, material handling, inspection, weighing, filling, packaging and sanitation operations. Digital monitoring and connected equipment are also becoming more important as manufacturers seek better production visibility and predictive maintenance capabilities. Automation enables processors to reduce downtime, improve throughput and minimize production waste while supporting stringent quality and food-safety requirements.
Restraints in the Chile Food Processing Equipment Market
High Initial Investment and Financing Constraints:
Advanced food-processing equipment requires significant capital expenditure, particularly for fully automated processing lines, high-speed packaging systems, robotics, refrigeration infrastructure and integrated production systems. This creates a greater barrier for smaller and medium-sized processors, which represent a large portion of Chile's food-processing companies. Smaller manufacturers may continue using semi-automatic or manual machinery for longer periods, replace individual machines rather than complete production lines, or postpone modernization projects.
Regulatory Requirements and Technical Complexity:
Food processors must maintain high standards for hygiene, food safety, quality control and production consistency. Compliance requirements can increase equipment-selection, installation and validation complexity. Manufacturers also need machinery that can be easily cleaned, maintained and integrated into hygienic production environments. Imported equipment may require adaptation to local operating conditions, plant infrastructure and production processes.
Growth Opportunities in the Chile Food Processing Equipment Market
Smart Automation, Robotics and Predictive Maintenance:
The transition from conventional machinery toward connected and intelligent production systems represents a significant opportunity for equipment manufacturers and technology providers. Food processors can increasingly integrate sensors, machine vision, robotics, automated inspection and production-monitoring systems into existing facilities. Predictive maintenance can identify equipment abnormalities before failures occur, while real-time production monitoring can improve process control and reduce downtime.
Energy-Efficient and Sustainable Processing Solutions:
Sustainability is creating growing demand for machinery that reduces energy consumption, water usage, food waste and material requirements. Food processors are increasingly evaluating equipment based not only on production capacity but also on operating efficiency and environmental performance. Opportunities exist for efficient refrigeration and cooling systems, heat-recovery technologies, optimized processing equipment, water-efficient cleaning systems and sustainable packaging machinery.
Trends in the Chile Food Processing Equipment Market
Shift Toward Integrated and Automated Production Lines:
The Chilean market is gradually moving from standalone machinery toward integrated processing, handling and packaging lines. Manufacturers increasingly prefer equipment that can communicate across production stages and provide centralized monitoring and control. This trend improves production consistency, reduces manual intervention and simplifies maintenance. Automated material handling, robotic packaging, machine vision and digital quality-control systems are becoming increasingly relevant as processors seek higher productivity and greater operational visibility.
Growing Focus on Sustainability and Resource Efficiency:
Sustainability is becoming an important consideration in food-processing equipment selection. Manufacturers are increasingly looking for machinery capable of reducing energy consumption, water usage, product losses and waste while maintaining production performance. This trend is encouraging equipment suppliers to develop more efficient processing, cooling, cleaning and packaging technologies. Sustainable machinery is also becoming commercially attractive because reductions in resource consumption can lower operating costs while helping food processors respond to environmental expectations from customers and export markets.
Research Scope and Analysis
The market is segmented By Equipment Type, By Mode of Operation, By Food Category and By End User. The analysis captures capital equipment, integrated processing systems, automation intensity and demand differences across Chile's major food-processing industries.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Equipment Type Analysis
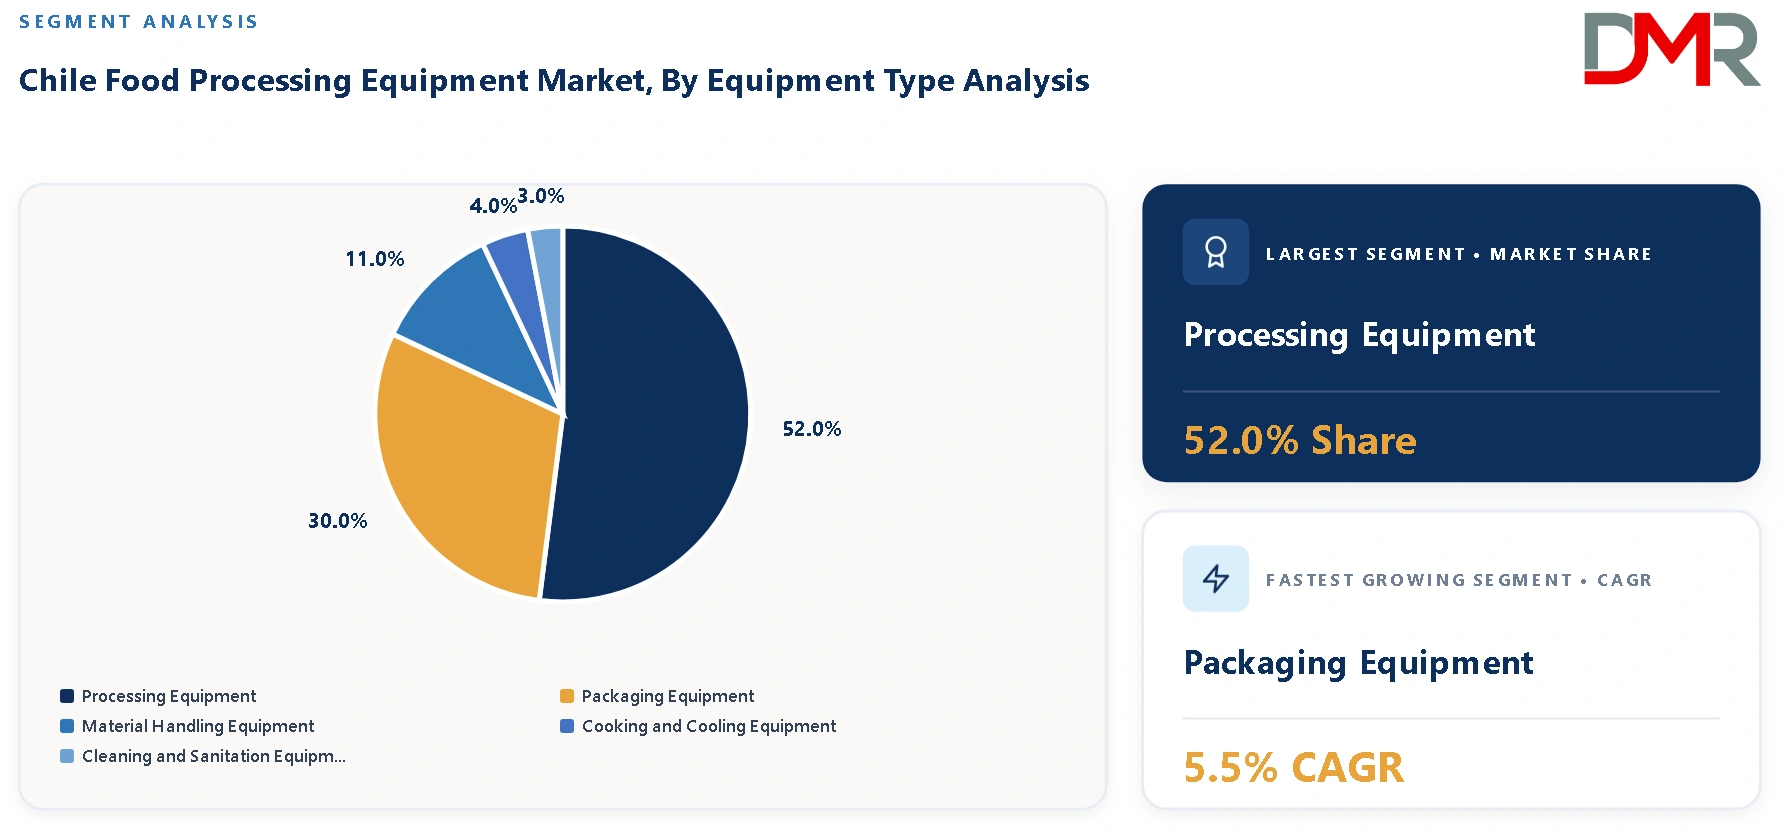
Processing Equipment is estimated to dominate in 2026 with 52% market share, reflecting the capital intensity and broad application of mixers, cutters, grinders, separators, pasteurizers, homogenizers, evaporators, dryers, ovens and other machinery directly involved in transforming food inputs. Packaging Equipment is the second-largest category at approximately 30%, supported by export requirements, shelf-life extension, portion control and increasingly automated filling and sealing. Material Handling Equipment accounts for around 11%, while Cooking and Cooling Equipment represents approximately 4% and Cleaning and Sanitation Equipment about 3%. The fastest-growing sub-segment is Packaging Equipment, forecast at approximately 5.5% CAGR, as processors respond to convenience-oriented consumption, export specifications and automated high-speed lines. Processing Equipment remains dominant because it is essential to virtually every industrial food category, while packaging has a faster replacement cycle and greater scope for automation, machine vision and format flexibility. Chile has established supplier ecosystems covering filling, processing, hygienic equipment and packaging, including Tetra Pak, GEA, Bühler and local integrators.
By Mode of Operation Analysis
Automatic equipment is estimated to lead the market in 2026 with 58% share, reflecting the economics of large-scale Chilean processors and export-oriented production. Automatic systems improve throughput, consistency, traceability and labor productivity and are increasingly combined with sensors, PLCs, machine vision and cloud-based monitoring. Semi-Automatic equipment represents approximately 30%, remaining important among small and medium-sized processors that require productivity gains but cannot justify fully automated production lines. Manual equipment accounts for approximately 12%, concentrated in artisanal, specialty and low-volume operations. Automatic equipment is also the fastest-growing sub-segment at an estimated 6.2% CAGR, substantially ahead of manual systems, because Chilean processors are moving toward predictive maintenance, automated quality control and integrated line management. The shift is supported by global suppliers introducing digitalized machinery and by increasing pressure to reduce production variability and labor dependence. GEA's connected-machine strategy and Tetra Pak's Factory OS illustrate the growing integration of physical equipment and software.
By Food Category Analysis
Beverages represent the largest application category with an estimated 22% share in 2026, supported by bottled beverages, juices, dairy drinks, functional products and other liquid formulations requiring sophisticated processing, filling and packaging systems. Meat, Poultry and Seafood rank second at approximately 21%, reflecting Chile's significant protein and seafood-processing base and demand for cutting, portioning, freezing, hygienic handling and packaging equipment. Bakery and Confectionery accounts for 17%, Dairy Products 15%, Fruits and Vegetables 10%, Grain Milling and Processing 8%, and Others 7%. The fastest-growing application is estimated to be Beverages at 5.4% CAGR, driven by product diversification, convenience formats, functional beverages and automated filling. Dairy also offers attractive technology opportunities as processors invest in digitalization, energy-efficient thermal processing and value-added products. Tetra Pak's Chile operation specifically serves dairy and beverage processing and packaging, while Bühler maintains local capabilities covering grain milling, bakery, pasta, brewing and related food-processing applications.
By End User Analysis
Large-Scale Food Processors account for approximately 67% of 2026 market revenue, making them the dominant end-user group. These companies have the capital, production volumes and export exposure necessary to justify automated processing lines, robotics, high-speed packaging, digital monitoring and energy optimization. Small and Medium-Sized Processors hold around 25%, with demand concentrated in modular machinery, semi-automatic equipment and retrofit solutions that provide measurable productivity improvements without the cost of complete plant automation. Artisanal and Specialty Food Producers represent approximately 8%, purchasing smaller-capacity mixers, ovens, fillers, packaging systems and specialized processing equipment. SMEs are nevertheless expected to record stronger unit growth than large processors as financing and modular automation improve. Their modernization needs create a substantial aftermarket opportunity for local distributors and integrators. Suppliers offering scalable systems that can begin semi-automatically and later incorporate robotics or digital controls are particularly well positioned to address this segment.
The Chile Food Processing Equipment Market Report is segmented on the basis of the following:
By Equipment Type
- Processing Equipment
- Packaging Equipment
- Material Handling Equipment
- Cooking and Cooling Equipment
- Cleaning and Sanitation Equipment
By Mode of Operation
- Automatic
- Semi-Automatic
- Manual
By Food Category
- Dairy Products
- Meat, Poultry and Seafood
- Bakery and Confectionery
- Beverages
- Fruits and Vegetables
- Grain Milling and Processing
- Others
By End User
- Large-Scale Food Processors
- Small and Medium-Sized Processors
- Artisanal and Specialty Food Producers
Regulatory Landscape
Chile's food-processing equipment market operates within a stringent sanitary framework led by the Reglamento Sanitario de los Alimentos (RSA), which governs production, importation, processing, packaging, storage, distribution and sale of food for human consumption. The rules require auditable Good Manufacturing Practices and, where designated by the authorities, HACCP implementation. The regulatory environment favors hygienic equipment design, cleanability, stainless-steel construction, controlled processing parameters, contamination prevention and traceability. For suppliers, compliance can increase engineering and validation requirements but also raises barriers to low-quality imports. Future opportunities will center on automated sanitation, digital traceability, machine vision and connected quality-control systems that allow processors to demonstrate consistent compliance while reducing manual inspection. Regulatory requirements therefore function as both a market constraint and a demand catalyst.
Investment and White Space Analysis
Investment opportunities are strongest where automation, sustainability and production flexibility intersect. The largest white spaces include retrofit automation for SMEs, predictive-maintenance platforms, energy-efficient thermal systems, hygienic conveying, automated inspection, cold-chain optimization and sustainable packaging machinery. Large exporters will continue investing in integrated lines, but the broader opportunity lies in modular solutions that allow smaller processors to automate incrementally. Local service capability is another underserved area: global manufacturers have Chilean operations or representatives, including Tetra Pak, GEA and Bühler, while local integrators supply specialized equipment and engineering services.
Competitive Landscape
The Chile Food Processing Equipment Market is moderately fragmented at the supplier level but concentrated in high-value integrated systems. Global engineering companies compete alongside specialized international manufacturers, distributors and Chilean system integrators. Leading suppliers differentiate through process expertise, equipment reliability, automation, hygienic design, energy efficiency, commissioning capability and after-sales service. Large players increasingly pursue integrated solutions spanning processing, packaging, automation and lifecycle support. Tetra Pak has a direct Chilean commercial presence, GEA maintains offices in Santiago and Osorno, and Bühler operates a Chilean base supporting food-processing customers. Local distributors such as Alfa Group provide specialized machinery across meat, seafood, bakery and other applications.
Some of the prominent players in the Chile Food Processing Equipment Market are:
- GEA Group
- Tetra Pak
- Bühler Group
- JBT Marel
- Krones
- Alfa Laval
- SPX FLOW
- Heat and Control
- Ishida
- MULTIVAC
- Syntegon Technology
- IMA Group
- KHS
- Sidel
- FLSmidth
- Hosokawa Micron
- ANDRITZ
- Baker Perkins
- Clextral
- Pavan Group
- Shibuya Corporation
- Shikoku Kakoki
- Fuji Machinery
- Yamato Scale
- Marel
- Flottweg
- Bucher Unipektin
- Alfa Laval Chile
- GEA Chile
- Tetra Pak Chile
- JBT Marel Chile
- Krones Chile
- Taglermaq
- Silbertec
- Bracker
- Artipac
- Equipos Gastronomicos Chile
- IMECO
- Mundo Equipos
- Factoria de Equipos Industriales
- Other Key Players
Recent Developments
- November 2025: Tetra Pak launched Factory OS, a modular automation and digitalization portfolio designed to provide real-time contextualized production information and prepare food and beverage factories for AI-enabled operations.
- October 2025: Tetra Pak highlighted dairy-processing innovation during the World Dairy Summit in Santiago, emphasizing automation, sustainability, nutrition and higher-value dairy products as priorities for Chile's dairy industry.
- April 2025: GEA introduced NEXUS, an integrated engineering approach combining processing and heating/cooling systems, with potential plant-wide energy savings of up to 30% in suitable food, dairy and beverage applications.
- January 2025: Tetra Pak expanded its homogenizer range with the Tetra Pak 15C and 20C, featuring a redesigned two-in-one homogenization approach intended to reduce energy consumption and simplify installation and maintenance.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 326.7 Mn |
| Forecast Value (2035) |
USD 468.4 Mn |
| CAGR (2026–2035) |
4.1% |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Equipment Type, By Mode of Operation, By Food Category, By End User |
| Country Coverage |
Chile |
Frequently Asked Questions
What is the Chile Food Processing Equipment Market size in 2026?
▾ The Chile Food Processing Equipment Market is estimated to reach approximately USD 326.7 million in 2026, supported by modernization and automation investments.
What will the Chile Food Processing Equipment Market size be in 2035?
▾ The Chile Food Processing Equipment Market is projected to reach approximately USD 468.4 million by 2035, driven by continued equipment replacement and capacity expansion.
What is the CAGR of the Chile Food Processing Equipment Market?
▾ The Chile Food Processing Equipment Market is expected to expand at approximately 4.1% CAGR during the 2026–2035 forecast period.
What are the key drivers of the Chile Food Processing Equipment Market?
▾ The Chile Food Processing Equipment Market is driven by processed-food demand, export-oriented production, automation, food-safety requirements and the need for greater manufacturing efficiency.
Which segment dominates the Chile Food Processing Equipment Market?
▾ Processing Equipment dominates the Chile Food Processing Equipment Market, supported by widespread applications across beverage, dairy, meat, seafood, bakery and other food-processing operations.
Which is the fastest-growing segment in the Chile Food Processing Equipment Market?
▾ Automatic equipment is expected to be the fastest-growing segment in the Chile Food Processing Equipment Market as manufacturers increasingly adopt automation and digital production technologies.
Who are the key players in the Chile Food Processing Equipment Market?
▾ Key participants in the Chile Food Processing Equipment Market include Tetra Pak, GEA, Bühler and various specialized international manufacturers, distributors and local system integrators.
How is technology influencing the Chile Food Processing Equipment Market?
▾ AI, IoT, robotics, machine vision and connected systems are transforming the Chile Food Processing Equipment Market by improving productivity, quality control, predictive maintenance and resource efficiency.