China IUCD Market Snapshot
- China IUCD Market Size in 2026: USD 486.2 Million
- China IUCD Market Size in 2035: USD 782.4 Million
- China CAGR from 2026 to 2035: 5.4%
- Copper/Non-Hormonal IUCDs is the leading product type segment in 2026: 68.3%
- Copper is the leading material segment in 2026: 64.2%
- 25-34 Years is the leading age group segment in 2026: 42.6%
- Hospitals and Gynecology Clinics is the leading distribution channel segment in 2026: 61.8%
- Public Healthcare Institutions is the leading end user segment in 2026: 58.4%
What is the China IUCD Market and its Market Size?
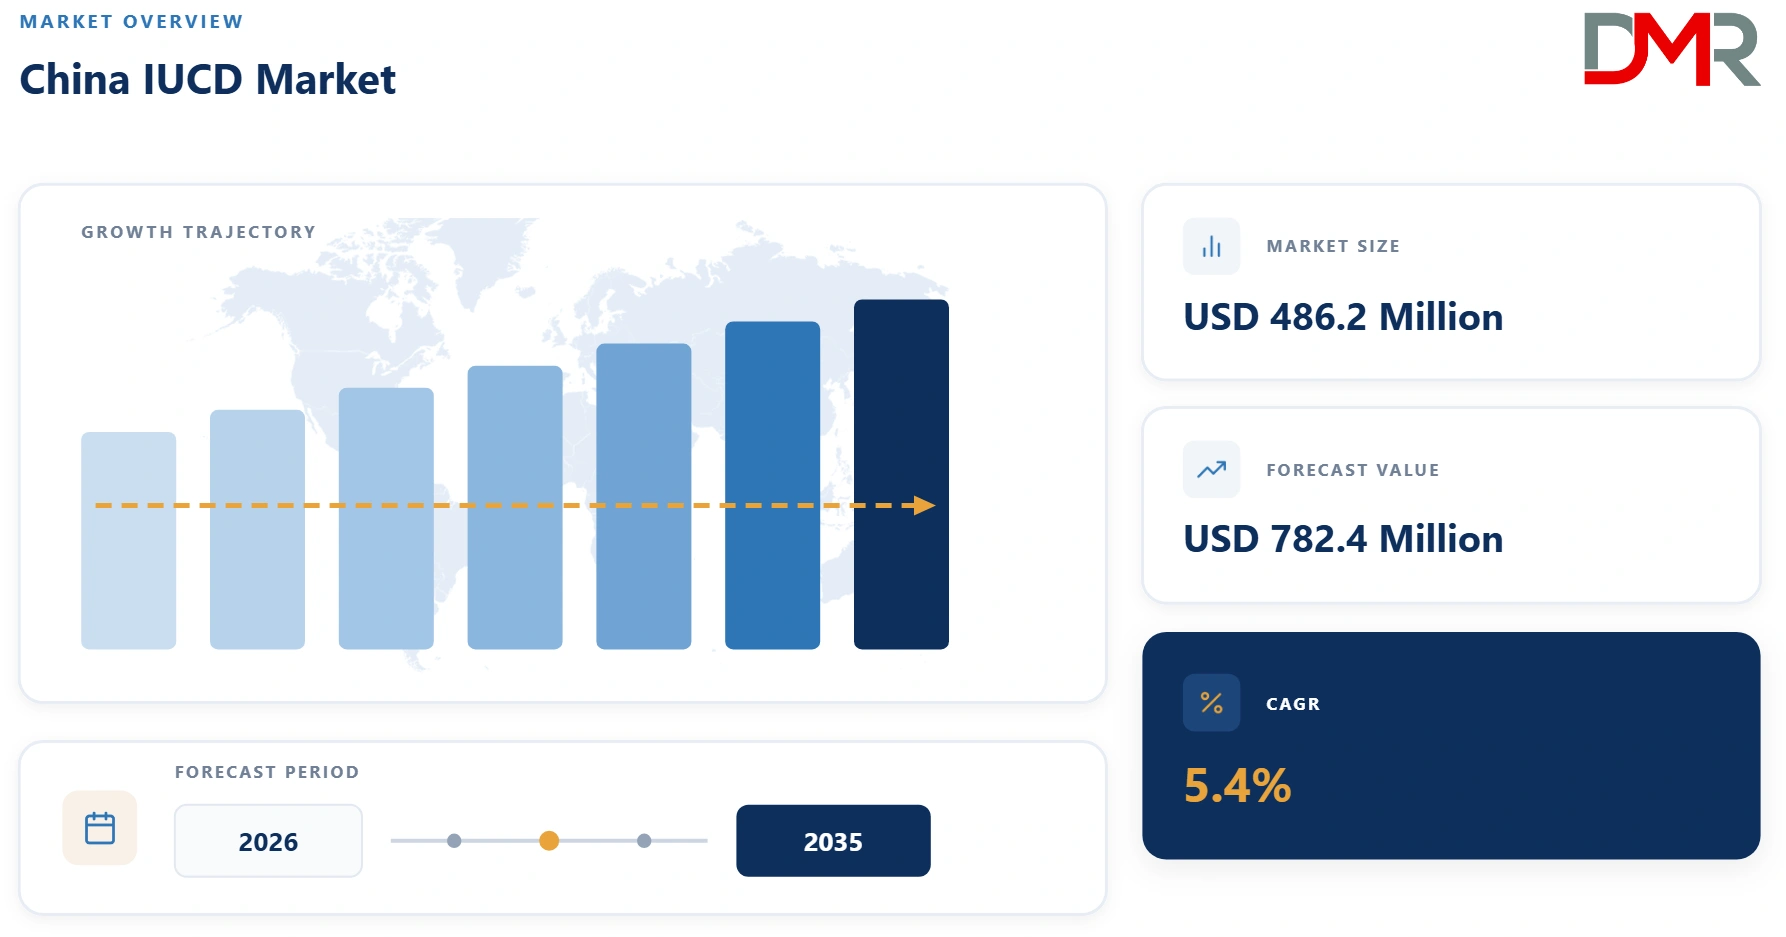
The China IUCD Market is projected to be valued at USD 486.2 Million in 2026 and is projected to reach USD 782.4 Million by 2035, expanding at a CAGR of 5.4% during the forecast period.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Growth is being propelled by China's massive and long-established base of intrauterine device users built up over decades of national family planning policy, continued government public health program support for long-acting reversible contraception as part of broader reproductive health services, and gradually growing adoption of hormonal levonorgestrel-releasing IUCDs among urban Chinese women seeking additional non-contraceptive benefits alongside pregnancy prevention. The maturing of hormonal IUCD availability and clinician familiarity across major Chinese hospital systems, growing private hospital and gynecology clinic capacity offering broader IUCD product choice and counseling beyond traditional public health system channels, and continued government efforts to support women's reproductive health services following the evolution of national family planning policy away from historical one-child and two-child restrictions toward broader reproductive autonomy and support are reshaping the market from a historically standardized, copper-IUCD-dominated public health program category into an increasingly diversified, patient-choice-oriented contraceptive market. Investment is accelerating as both public health institutions and private healthcare providers expand IUCD counseling and insertion services while gradually broadening product offerings beyond traditional copper devices.
Use Cases
- Public Health Program-Supported Copper IUCD Insertion for Long-Term Contraception: Chinese public healthcare institutions and community health centers provide copper IUCD insertion services as part of government-supported reproductive health programs, continuing a long-established pattern of public health system support for long-acting contraceptive access.
- Hormonal IUCD Adoption Among Urban Women Seeking Non-Contraceptive Benefits: Urban Chinese women increasingly choose levonorgestrel-releasing hormonal IUCDs through private hospitals and gynecology clinics, seeking both contraceptive effectiveness and non-contraceptive benefits including reduced menstrual bleeding and pain associated with hormonal IUCD use.
- Postpartum IUCD Insertion Supporting Birth Spacing: Hospitals across China offer postpartum IUCD insertion services immediately following childbirth, supporting healthy birth spacing objectives and providing a convenient contraceptive option at a point of existing clinical contact.
- IUCD Counseling and Insertion Services Within Expanding Private Gynecology Clinic Networks: Growing private gynecology clinic and hospital networks across major Chinese cities offer comprehensive contraceptive counseling and IUCD insertion services, providing an alternative to traditional public health system channels for women seeking more personalized reproductive health care.
Key Takeaways
- Market Size: The China IUCD Market is anticipated to be valued at USD 486.2 Million in 2026 and is forecast to reach USD 782.4 Million by 2035, expanding at a CAGR of 5.4%.
- Growth Outlook: Market expansion is sustained by China's massive established IUCD user base built through decades of family planning policy, continued government reproductive health program support, and gradually growing hormonal IUCD adoption among urban women.
- Primary Growth Drivers: China's long-established and substantial IUCD user base, continued government public health program support for long-acting reversible contraception, growing hormonal IUCD adoption among urban women seeking non-contraceptive benefits, and expanding private gynecology clinic capacity are supporting steady market growth.
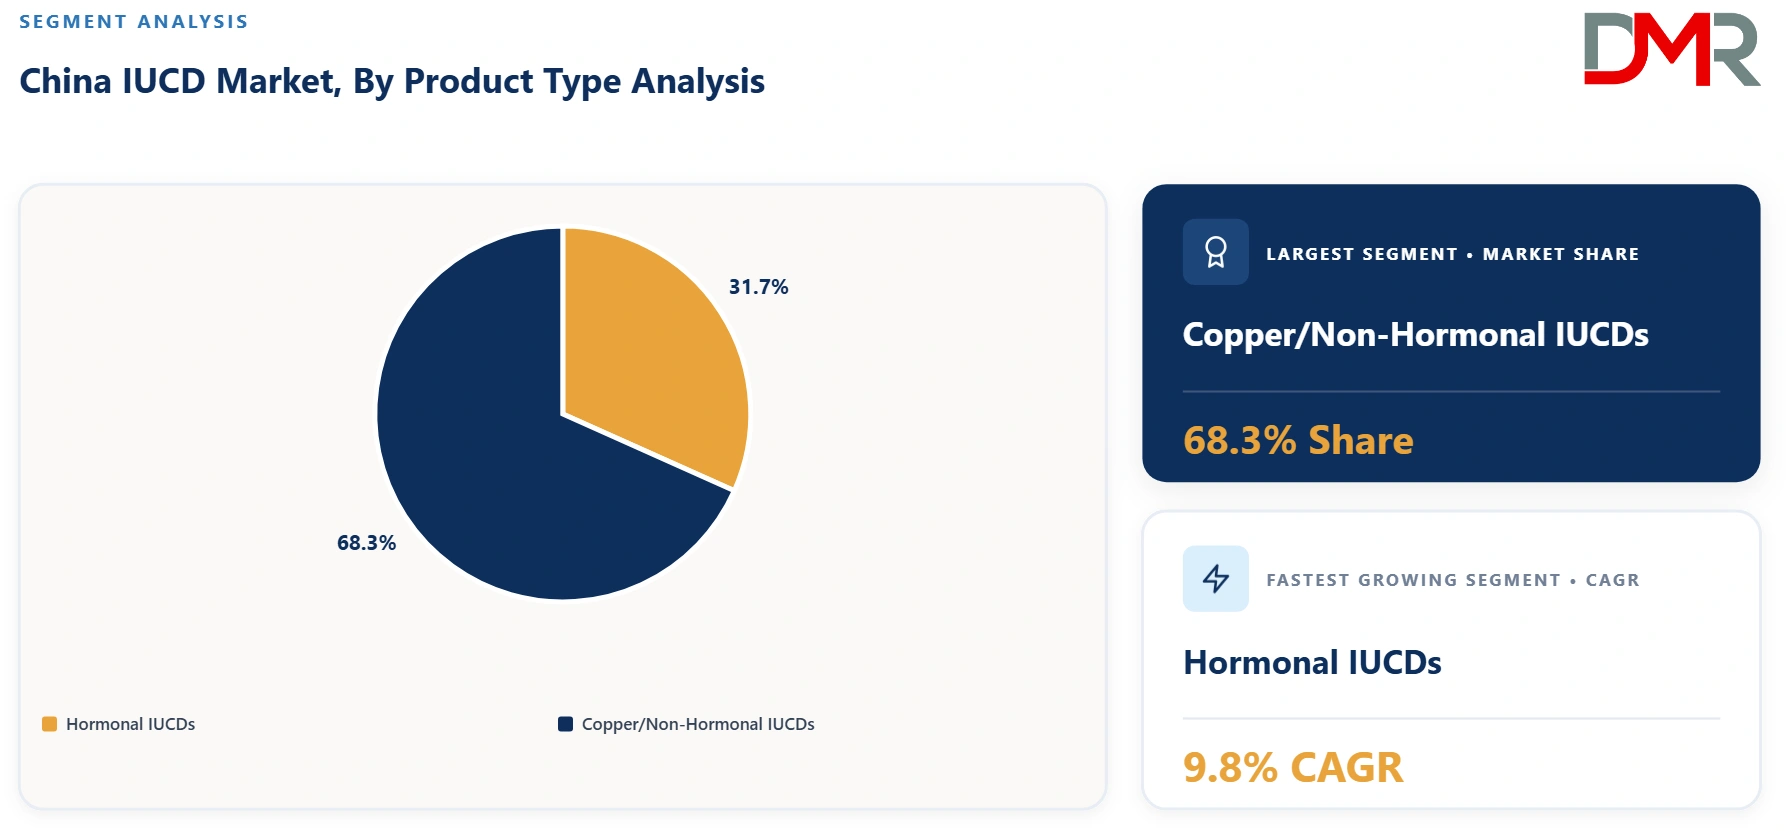
- By Product Type Analysis: Copper/Non-Hormonal IUCDs is projected to lead the product type segment with a 68.3% share in 2026, reflecting the historical dominance of copper devices within China's public health-supported contraceptive programs. Hormonal IUCDs is the fastest-growing product type segment at 9.8% CAGR, driven by growing urban adoption of levonorgestrel-releasing devices offering additional clinical benefits.
- By Material Analysis: Copper is expected to dominate with a 64.2% share in 2026, supported by its established role in China's long-running public health contraceptive programs. Levonorgestrel-Releasing is the fastest-growing material segment at 9.8% CAGR, driven by rising clinician and patient familiarity with hormonal IUCD benefits.
- By Age Group Analysis: 25-34 Years is poised to lead with a 42.6% share in 2026, reflecting the concentration of IUCD use among women in this key reproductive and family planning age range. 35-44 Years is the fastest-growing age group segment at 6.2% CAGR, driven by continued use among women completing their families and seeking effective longer-term contraception.
- By Distribution Channel Analysis: Hospitals and Gynecology Clinics is projected to dominate with a 61.8% share in 2026, reflecting the clinical, procedure-based nature of IUCD insertion. Online Channels is the fastest-growing distribution channel segment at 8.9% CAGR, driven by growing use of digital platforms for reproductive health information and appointment scheduling ahead of in-clinic insertion procedures.
- By End User Analysis: Public Healthcare Institutions are projected to dominate with a 58.4% share in 2026, reflecting the historical and continued central role of China's public health system in IUCD service delivery. Private Hospitals and Clinics is the fastest-growing end user segment at 8.6% CAGR, driven by growing consumer preference for private healthcare services offering greater choice and personalized counseling.
Key Drivers in the China IUCD Market
China's Long-Established and Substantial IUCD User Base
China maintains one of the world's largest populations of IUCD users, reflecting decades of national family planning policy that historically promoted long-acting reversible contraception, particularly copper IUCDs, as a primary contraceptive method supported through the public health system. This substantial established user base, while gradually evolving in composition as national family planning policy has shifted, continues to provide a large and stable underlying demand foundation for the China IUCD Market, including sustained demand for device replacement as existing IUCDs reach their effective lifespan and require removal or reinsertion.
Continued Government Public Health Program Support for Long-Acting Reversible Contraception
China's public health system continues to support access to long-acting reversible contraception, including IUCDs, as part of broader reproductive health service provision, even as national family planning policy has evolved substantially from historical one-child and two-child era restrictions toward policies encouraging higher birth rates. This continued public health program infrastructure supporting IUCD counseling, insertion, and removal services provides an accessible and often subsidized pathway for Chinese women to access long-acting contraception, sustaining baseline market demand across the country's public healthcare institution network.
Restraints in the China IUCD Market
Evolving National Family Planning Policy Creating Demand Uncertainty
China's national family planning policy has evolved substantially in recent years, shifting from historical birth restriction policies toward government encouragement of higher birth rates in response to demographic aging and declining birth rate concerns. This evolving policy environment creates some uncertainty regarding the future trajectory of long-acting contraceptive method demand and government program support prioritization, as public health messaging and program resource allocation may gradually shift emphasis in ways that could affect the pace of IUCD market growth relative to a more stable historical policy environment.
Growth Opportunities in the China IUCD Market
Hormonal IUCD Market Development Among Urban, Higher-Income Women
Growing urban Chinese women's health awareness and willingness to pay for premium reproductive health products presents a substantial opportunity for hormonal IUCD manufacturers to expand market penetration beyond the traditional copper IUCD base, particularly among higher-income women seeking the additional clinical benefits, including reduced menstrual bleeding, associated with levonorgestrel-releasing devices. Companies capable of building clinician and patient awareness of hormonal IUCD benefits through private hospital and gynecology clinic channels can capture significant growth within this underpenetrated premium product segment.
Private Gynecology Clinic Network Expansion Supporting Broader Product Choice
Continued expansion of private hospital and gynecology clinic networks across major Chinese cities presents an opportunity for IUCD manufacturers to develop stronger distribution and clinician education relationships supporting broader contraceptive product choice and counseling quality beyond what has historically been available primarily through public health system channels. Companies building strong private healthcare channel relationships can capture growing demand from women seeking more personalized reproductive health care and product selection.
Trends in the China IUCD Market
Gradual Diversification Beyond Traditional Copper IUCD Dominance
The China IUCD Market continues to gradually diversify beyond its historical near-total dependence on copper IUCD devices, with growing clinician and patient awareness of hormonal IUCD options gradually expanding this product category's market share, particularly within private healthcare channels serving urban, higher-income patient populations. This diversification trend reflects broader evolution in Chinese women's healthcare consumption patterns toward greater product choice and personalized care.
Growing Integration of Digital Health Platforms for Reproductive Health Education and Access
Chinese healthcare providers and digital health platforms are increasingly incorporating reproductive health education and appointment scheduling capability into broader digital health service offerings, supporting improved women's access to information about contraceptive options including IUCDs ahead of in-clinic consultation and insertion procedures. This digital integration trend reflects China's broader strength in digital health platform development and growing consumer comfort accessing health information and services through digital channels.
Research Scope and Analysis
The China IUCD Market is segmented by product type, material, age group, distribution channel, and end user, covering hormonal and copper IUCDs, copper and levonorgestrel-releasing materials, and public and private healthcare institution end users.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Product Type Analysis
Copper/Non-Hormonal IUCDs are projected to dominate the China IUCD Market with a 68.3% share in 2026, reflecting the historical and continued dominance of copper devices within China's public health-supported contraceptive programs built over decades of national family planning policy implementation. Hormonal IUCDs is expected to register the highest CAGR of 9.8% during 2026-2035, driven by growing urban adoption of levonorgestrel-releasing devices offering additional clinical benefits beyond contraception alone.
By Material Analysis
Copper is anticipated to dominate the China IUCD Market by material, accounting for 64.2% share in 2026, supported by its established, low-cost role in China's long-running public health contraceptive programs and broad clinician familiarity across the country's healthcare system. Levonorgestrel-Releasing is projected to register the highest CAGR of 9.8% between 2026 and 2035, driven by rising clinician and patient familiarity with hormonal IUCD benefits, particularly within private healthcare channels serving urban patient populations.
By Age Group Analysis
25-34 Years is projected to lead the China IUCD Market with an estimated 42.6% share in 2026, reflecting the concentration of IUCD use among women in this key reproductive and family planning age range following childbirth or as an ongoing contraceptive method. 35-44 Years is expected to register the fastest CAGR of 6.2% through 2035, driven by continued IUCD use among women who have completed their families and seek effective, low-maintenance longer-term contraception.
By Distribution Channel Analysis
Hospitals and Gynecology Clinics are projected to dominate the China IUCD Market with 61.8% share in 2026, reflecting the clinical, procedure-based nature of IUCD insertion requiring qualified healthcare provider administration. Online Channels is expected to register the fastest CAGR of 8.9% through 2035, driven by growing use of digital platforms for reproductive health information access and appointment scheduling ahead of in-clinic insertion procedures.
By End User Analysis
Public Healthcare Institutions are projected to dominate the China IUCD Market with 58.4% share in 2026, reflecting the historical and continued central role of China's public health system in IUCD counseling, insertion, and removal service delivery. Private Hospitals and Clinics are expected to register the fastest CAGR of 8.6% through 2035, driven by growing consumer preference for private healthcare services offering greater product choice and more personalized reproductive health counseling.
The China IUCD Market Report is segmented based on the following:
By Product Type
- Hormonal IUCDs
- Copper/Non-Hormonal IUCDs
By Material
- Copper
- Levonorgestrel-Releasing
- Others
By Age Group
- 15-24 Years
- 25-34 Years
- 35-44 Years
- 45 Years and Above
By Distribution Channel
- Hospitals and Gynecology Clinics
- Community Health Centers
- Retail Pharmacies
- Online Channels
By End User
- Public Healthcare Institutions
- Private Hospitals and Clinics
Technology Analysis
Technology development is increasingly shaping competitiveness in the China IUCD Market as manufacturers invest in improved copper IUCD frame designs reducing insertion discomfort and expulsion rates, advanced levonorgestrel-releasing hormonal IUCD formulations offering extended effective duration, and digital health platforms supporting reproductive health education and provider appointment access. Growing use of ultrasound-guided insertion technique training is supporting improved insertion accuracy and reduced complication rates across both public and private healthcare provider networks. Opportunities are expanding for companies developing improved device designs specifically suited to Chinese women's anatomical considerations, as well as digital platforms supporting broader reproductive health education addressing historical information gaps regarding hormonal IUCD options. However, achieving broader clinician training and patient awareness supporting hormonal IUCD adoption beyond traditional copper device usage patterns remains an ongoing consideration across the industry.
Investment and White Space Analysis
Investment opportunities in the China IUCD Market are expanding alongside the country's substantial established IUCD user base, continued public health program support, and gradually growing hormonal IUCD adoption among urban women. Significant white space exists in hormonal IUCD market development among urban, higher-income women, private gynecology clinic network relationship development, and digital health platform integration supporting reproductive health education and access. Companies with strong clinician education and training capability, established relationships with both public healthcare institutions and growing private hospital networks, and digital health platform partnerships are positioned to capture premium, longer-duration growth opportunities. However, evolving national family planning policy creating some demand trajectory uncertainty, along with continued price sensitivity within public health system channels, can constrain the pace of premiumization-driven market value growth relative to underlying device volume.
Competitive Landscape
The China IUCD Market is moderately consolidated and increasingly competitive, comprising large diversified global contraceptive and women's health device companies with substantial Chinese operations, established domestic Chinese IUCD manufacturers serving the country's substantial public health system demand, and growing private hospital and gynecology clinic networks. Competition centers on established public health system distribution relationships, clinician training and education capability supporting hormonal IUCD adoption, private healthcare channel development, and digital health platform integration. Large global companies benefit from advanced hormonal IUCD technology and international clinical evidence, while domestic Chinese manufacturers compete through established cost-competitive copper IUCD production and deep public health system distribution relationships. Companies increasingly differentiate through clinician education support and private healthcare channel development rather than device portfolio breadth alone.
Some of the prominent players in the China IUCD Market are:
- Bayer AG
- CooperSurgical, Inc.
- DKT International
- Pregna International Ltd.
- SMB Corporation of India
- HLL Lifecare Limited
- OCON Therapeutics Ltd.
- Mona Lisa N.V.
- Eurogine, S.L.
- Prosan International B.V.
- Meril Life Sciences Pvt. Ltd.
- Pregna International (Shanghai)
- Zhejiang Daji Medical Instruments Co., Ltd.
- Jiangsu Suyun Medical Materials Co., Ltd.
- Jiangsu Rongye Technology Co., Ltd.
- Shanghai Medical Instruments Co., Ltd.
- Shanghai Dahua Medical Apparatus Co., Ltd.
- Shanghai Kindly Enterprise Development Group Co., Ltd.
- Jiangsu Kanghua Medical Equipment Co., Ltd.
- Jiangsu Huida Medical Instruments Co., Ltd.
- Jiangsu Jichun Medical Devices Co., Ltd.
- Nantong Angel Medical Instruments Co., Ltd.
- Jiangsu Yuyue Medical Equipment & Supply Co., Ltd.
- Zhejiang Gongdong Medical Technology Co., Ltd.
- Jiangsu Province Huaxing Medical Apparatus Industry Co., Ltd.
- Jiangsu Kangjin Medical Instrument Co., Ltd.
- Changzhou Medical Appliances General Factory Co., Ltd.
- Jiangsu Weikang Jiejing Medical Apparatus Co., Ltd.
- Jiangsu Shuangsheng Medical Instrument Co., Ltd.
- Ningbo Greetmed Medical Instruments Co., Ltd.
- Hangzhou Kangna Medical Instrument Technology Co., Ltd.
- Zhejiang Fert Medical Device Co., Ltd.
- Shandong Qiaopai Group Co., Ltd.
- Shandong Ande Healthcare Apparatus Co., Ltd.
- Henan Shuguang Jianshi Medical Equipment Group Co., Ltd.
- Guangzhou Improve Medical Instruments Co., Ltd.
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- Beijing Choice Electronic Technology Co., Ltd.
- Tianjin Medic Medical Equipment Co., Ltd.
- Shanghai Kindly Medical Instruments Co., Ltd.
- Other Key Players
Recent Developments
- July 2026: Bayer secured a equity investment from Apollo-managed funds in a newly created entity holding its long-acting reversible contraceptives business, while retaining majority ownership and full operational control. The transaction supports Bayer’s continued focus on hormonal intrauterine systems and other LARC products globally.
- November 2025: Heilongjiang Maternal and Child Health Hospital awarded procurement contracts for multiple intrauterine contraceptive devices, including T-shaped copper IUDs, indomethacin-containing copper IUDs, and HCu280 Y-shaped copper IUDs, to domestic manufacturers including Wuxi Tianyi Medical Equipment, Yantai Family Planning Pharmaceutical Equipment, and Shenyang Liren Medical Technology.
- December 2025: Frost & Sullivan released its 2025 China Contraceptive Products Market Development White Paper, highlighting increasing product innovation, growing demand for higher-quality contraceptive solutions, and changing competitive dynamics across China’s contraceptive device industry.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 486.2 Mn |
| Forecast Value (2035) |
USD 782.4 Mn |
| CAGR (2026–2035) |
5.4% |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Product Type, By Material, By Age Group, By Distribution Channel, By End User |
| Country Coverage |
China |
Frequently Asked Questions
How big is the China IUCD Market?
▾ The China IUCD Market is poised to be valued at USD 486.2 Million in 2026 and is projected to reach USD 782.4 Million by 2035, reflecting China's substantial established IUCD user base and continued public health program support for long-acting contraception.
What is the CAGR of the China IUCD Market from 2026 to 2035?
▾ The market is projected to expand at a compound annual growth rate (CAGR) of 5.4% between 2026 and 2035, supported by continued public health program support, growing hormonal IUCD adoption, and expanding private gynecology clinic capacity.
What factors are driving the growth of the China IUCD Market?
▾ Growth is driven by China's long-established and substantial IUCD user base, continued government public health program support for long-acting reversible contraception, growing hormonal IUCD adoption among urban women seeking non-contraceptive benefits, and expanding private gynecology clinic capacity.
What are the major trends in the China IUCD Market?
▾ Major trends include gradual diversification beyond traditional copper IUCD dominance, growing integration of digital health platforms for reproductive health education and access, and continued expansion of private gynecology clinic networks.
Who are the key players in the China IUCD Market?
▾ Key market participants include Bayer AG, Cooper Surgical, Shanghai Dahua Medical Apparatus Company, and other global and domestic Chinese contraceptive device manufacturers, alongside China's national family planning program infrastructure.
How is the China IUCD Market segmented?
▾ The market is segmented by product type, material, age group, distribution channel, and end user, with demand analysis concentrated across major Chinese provinces and urban centers including Guangdong, Jiangsu, and Shandong.