Europe Dental Software Market Snapshot
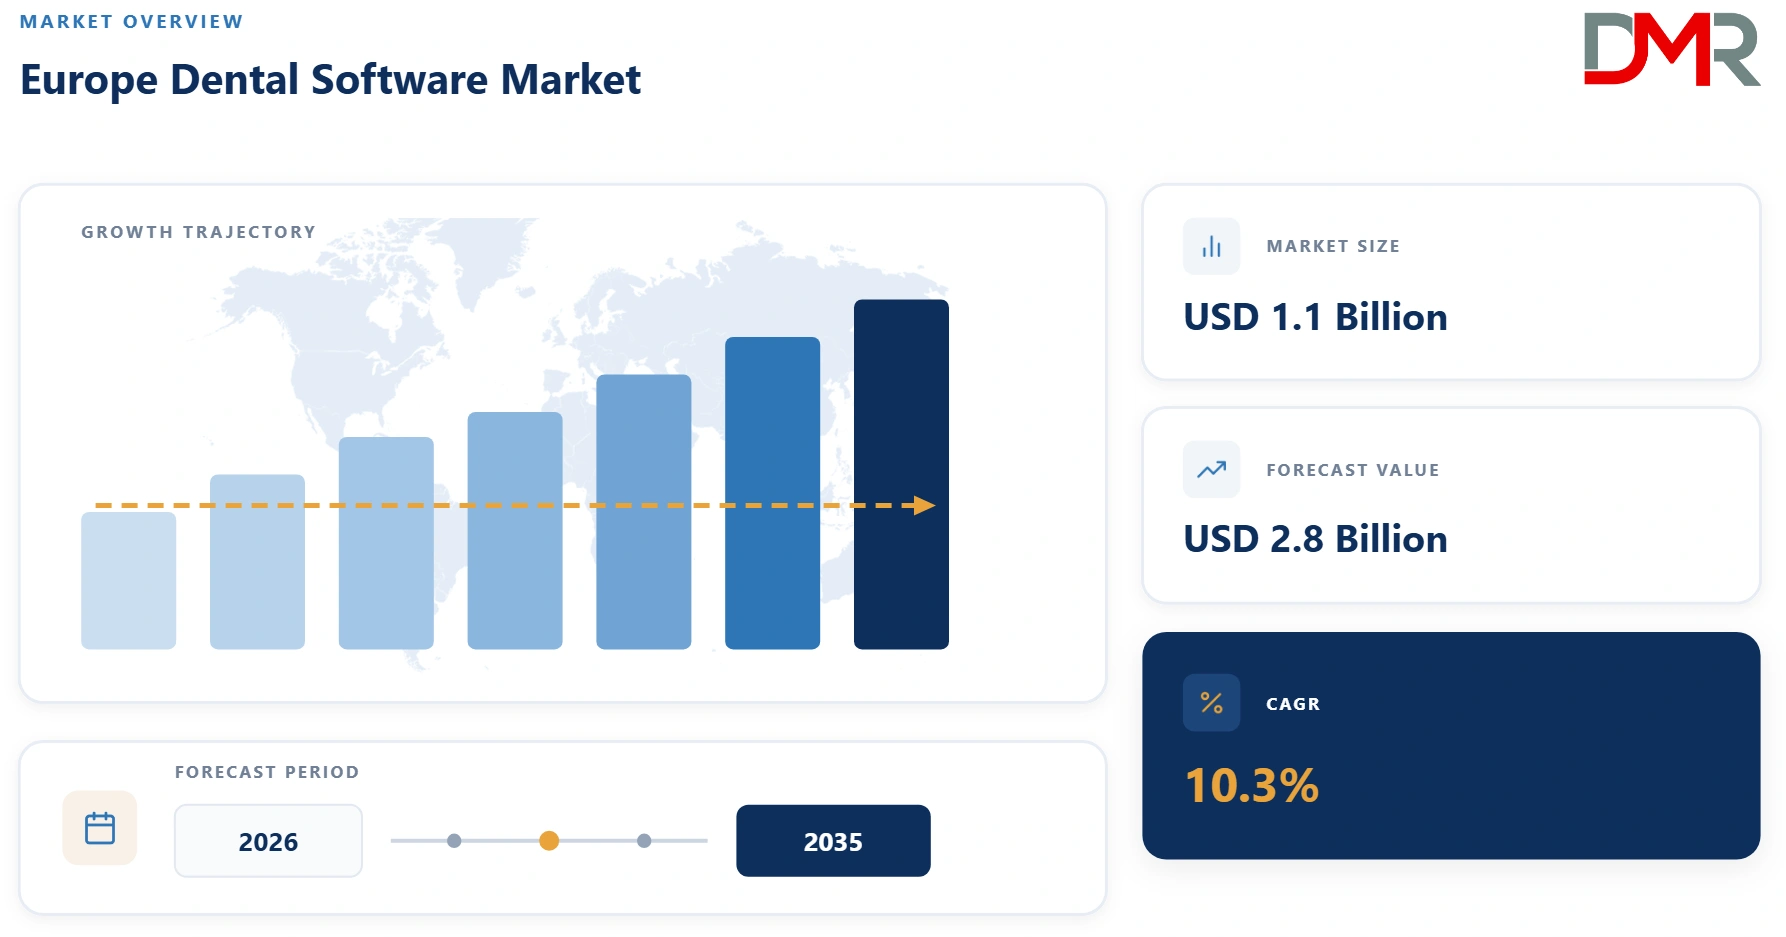
- Europe Dental Software Market Size in 2026: USD 1.1 Billion
- Europe Dental Software Market Size in 2035: USD 2.8 Billion
- Europe CAGR from 2026 to 2035: 10.3%
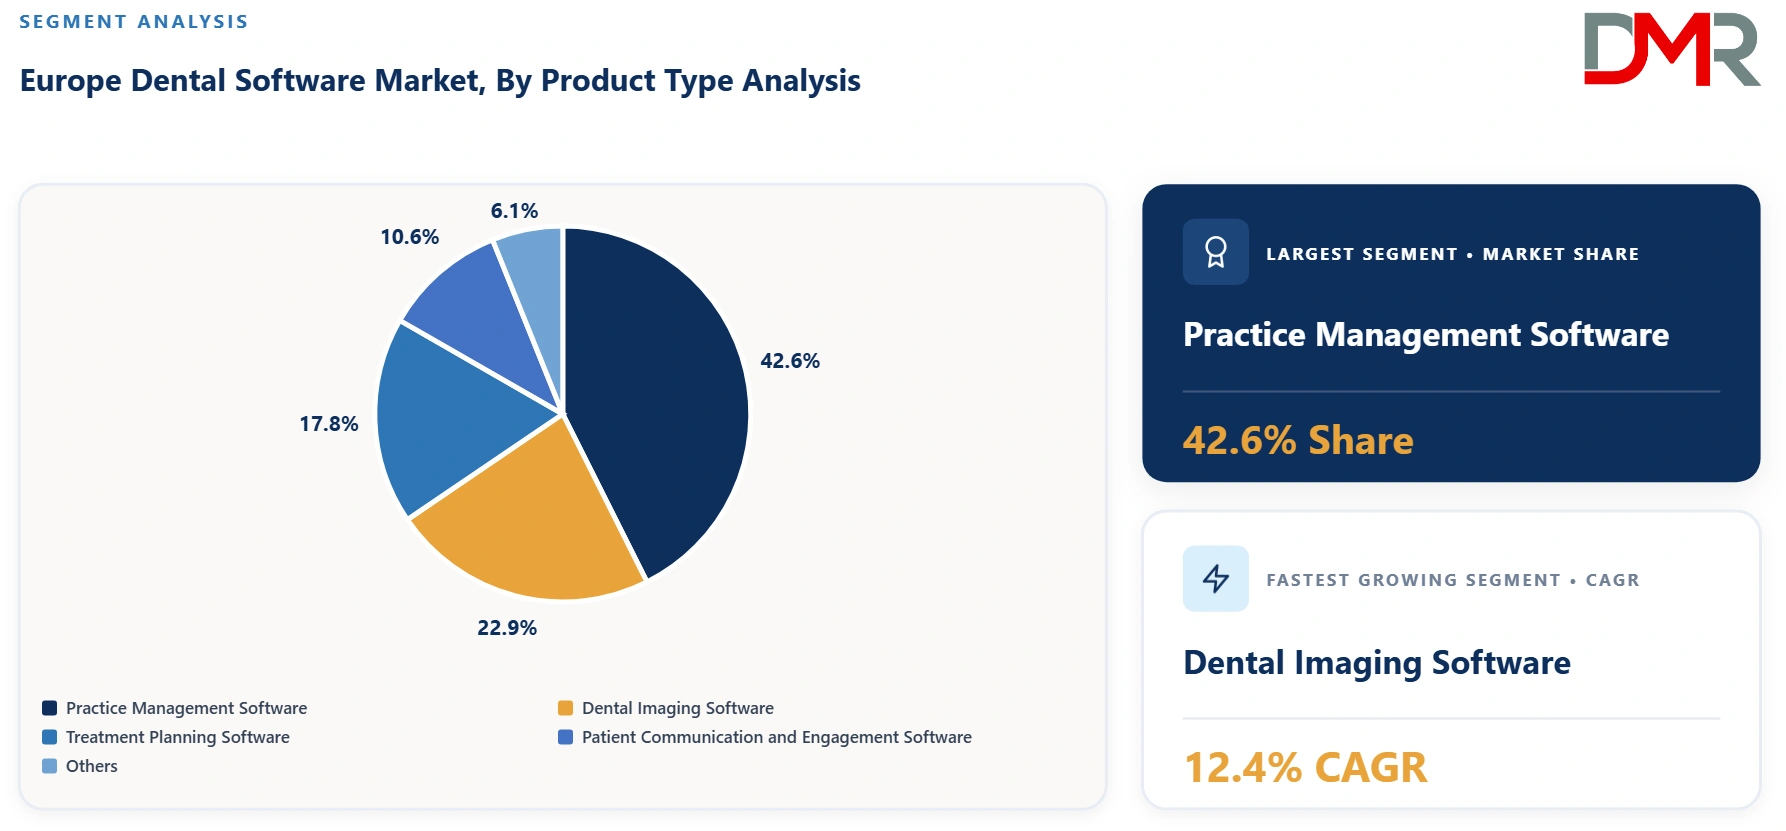
- Practice Management Software is the leading product type segment in 2026: 42.6%
- Cloud-Based is the leading deployment mode segment in 2026: 61.4%
- General Dentistry is the leading application segment in 2026: 48.3%
- Solo/Small Dental Practices is the leading end user segment in 2026: 46.8%
What is the Europe Dental Software Market and its Market Size?
The Europe Dental Software Market is projected to be valued at USD 1.1 Billion in 2026 and is projected to reach USD 2.8 Billion by 2035, expanding at a CAGR of 10.3% during the forecast period.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Growth is being propelled by continued consolidation of European dental practices into larger dental service organizations and group practices requiring integrated, scalable practice management and clinical software systems, accelerating digital transformation across dental imaging and treatment planning workflows supporting increasingly digital dentistry approaches, and growing patient expectations for digital communication, online booking, and streamlined administrative experiences consistent with broader consumer healthcare digitization trends. The maturing of cloud-based practice management platforms offering improved accessibility and reduced IT infrastructure burden for smaller independent practices, growing integration between dental imaging software and AI-enhanced diagnostic support tools improving clinical decision-making, and continued European dental service organization expansion driving demand for standardized, multi-location practice management software supporting centralized administrative and clinical oversight are reshaping the market from a largely fragmented, practice-specific software category into an increasingly cloud-native, integrated dental technology ecosystem. Investment is accelerating as software vendors expand cloud-based platform capability and AI-enhanced clinical features to serve both consolidating dental service organizations and independent practices across Europe.
Use Cases
- Multi-Location Practice Management for Dental Service Organizations: European dental service organizations and group dental practices use integrated practice management software to standardize scheduling, billing, patient records, and administrative workflows across multiple practice locations, supporting centralized operational oversight and consistent patient experience.
- AI-Enhanced Dental Imaging Analysis for Diagnostic Support: Dentists across Europe use AI-enhanced dental imaging software to support caries detection, periodontal disease assessment, and other diagnostic tasks, improving diagnostic consistency and supporting clinical decision-making alongside traditional radiographic interpretation.
- Digital Treatment Planning for Orthodontic and Restorative Procedures: Orthodontists and restorative dentists use treatment planning software incorporating 3D imaging and digital workflow integration to plan and communicate treatment approaches for clear aligner therapy, implant placement, and other complex restorative procedures.
- Patient Communication and Online Booking Platforms for Practice Growth: Dental practices across Europe use patient communication and engagement software supporting online appointment booking, automated reminder systems, and digital patient intake, improving practice efficiency and meeting growing patient expectations for convenient digital interaction.
Key Takeaways
- Market Size: The Europe Dental Software Market is anticipated to be valued at USD 1.1 Billion in 2026 and is forecast to reach USD 2.8 Billion by 2035, expanding at a CAGR of 10.3%.
- Growth Outlook: Market expansion is sustained by continued dental service organization consolidation requiring scalable practice management systems, accelerating digital dentistry workflow adoption, and growing patient demand for digital communication and administrative experiences.
- Primary Growth Drivers: Continued European dental service organization consolidation and group practice expansion, accelerating digital imaging and treatment planning workflow adoption, growing patient expectations for digital communication and booking convenience, and rising AI-enhanced diagnostic support tool integration are accelerating market growth.
- By Product Type Analysis: Practice Management Software is projected to lead the product type segment with a 42.6% share in 2026, reflecting its foundational role across scheduling, billing, and administrative workflow management for dental practices of all sizes. Dental Imaging Software is the fastest-growing product type segment at 12.4% CAGR, driven by continued digital dentistry adoption and AI-enhanced diagnostic support integration.
- By Deployment Mode Analysis: Cloud-Based is expected to dominate with a 61.4% share in 2026, supported by growing preference for reduced IT infrastructure burden and improved accessibility, particularly among smaller independent practices. Cloud-Based is also the fastest-growing deployment mode segment as dental service organizations increasingly favor cloud platforms supporting centralized, multi-location software management.
- By Application Analysis: General Dentistry is poised to lead with a 48.3% share in 2026, reflecting the broad base of general dental practices representing the largest segment of Europe's dental care delivery infrastructure. Oral and Maxillofacial Surgery is the fastest-growing application segment at 11.8% CAGR, driven by growing adoption of specialized treatment planning and imaging software for complex surgical cases.
- By End User Analysis: Solo/Small Dental Practices is projected to dominate with a 46.8% share in 2026, reflecting the continued substantial presence of independent practices across the European dental care landscape. Group Dental Practices and DSOs is the fastest-growing end user segment at 13.6% CAGR, driven by continued consolidation trends requiring scalable, multi-location software solutions.
Key Drivers in the Europe Dental Software Market
Continued European Dental Service Organization Consolidation and Group Practice Expansion
European dental care delivery continues to consolidate from a historically highly fragmented, independent practice-dominated structure toward larger dental service organizations and group practices, particularly across markets including the United Kingdom, Germany, and the Nordic countries where private equity-backed consolidation has proceeded most rapidly. This consolidation trend directly drives demand for standardized, scalable practice management software capable of supporting centralized administrative oversight, consistent clinical protocols, and integrated reporting across multiple practice locations, positioning dental service organization growth as a primary structural driver of software market expansion.
Accelerating Digital Imaging and Treatment Planning Workflow Adoption
European dental practices continue to accelerate adoption of digital imaging technology, including intraoral scanning and cone beam computed tomography, alongside corresponding treatment planning software supporting increasingly digital dentistry workflows spanning restorative, orthodontic, and surgical treatment planning. This continued digital workflow adoption is driving sustained demand for compatible dental imaging and treatment planning software capable of processing, analyzing, and integrating digital imaging data into comprehensive treatment planning and patient communication workflows.
Restraints in the Europe Dental Software Market
Data Privacy Compliance Complexity Under GDPR Affecting Software Development and Deployment
The European Union's General Data Protection Regulation creates substantial data privacy compliance requirements for dental software handling sensitive patient health information, representing a meaningful restraint on the Europe Dental Software Market. Software vendors must invest significantly in data protection infrastructure, consent management functionality, and compliance documentation capability, increasing development costs and potentially slowing deployment timelines, particularly for smaller software vendors with more limited compliance resources relative to larger, well-capitalized competitors.
Growth Opportunities in the Europe Dental Software Market
AI-Enhanced Diagnostic and Clinical Decision Support Tool Development
Growing dental practitioner interest in AI-enhanced diagnostic support tools capable of improving caries detection, periodontal assessment, and other diagnostic task consistency presents a substantial opportunity for software vendors to differentiate through advanced clinical AI capability integrated within broader imaging and practice management platforms. Companies capable of demonstrating clinically validated diagnostic support accuracy can capture premium positioning and stronger practitioner adoption as AI-enhanced dental software capability continues maturing.
Integrated, Interoperable Software Ecosystems Supporting Dental Service Organization Scalability
Growing dental service organization demand for fully integrated software ecosystems spanning practice management, imaging, treatment planning, and patient communication functionality presents a substantial opportunity for vendors capable of offering comprehensive, interoperable platform solutions rather than standalone point products. Companies developing integrated software ecosystems that reduce the operational complexity of managing multiple disconnected software systems across growing multi-location practice networks can capture significant value from continued dental service organization consolidation.
Trends in the Europe Dental Software Market
Growing Adoption of Cloud-Based, Subscription-Model Software Platforms
European dental practices are increasingly transitioning from traditional on-premise, licensed software toward cloud-based, subscription-model software platforms, reflecting both reduced upfront capital investment requirements and improved software update and support accessibility. This transition trend is particularly pronounced among dental service organizations seeking centralized software management capability across multiple practice locations without requiring separate on-premise IT infrastructure at each site.
Increasing Integration of Patient-Facing Digital Engagement Tools
Dental software vendors are increasingly expanding patient-facing digital engagement functionality, including online booking, digital treatment plan presentation, and automated communication tools, reflecting broader consumer healthcare expectations for convenient digital interaction. This trend is encouraging dental practices to view patient engagement software as an increasingly important practice growth and patient retention tool rather than a purely administrative convenience.
Research Scope and Analysis
The Europe Dental Software Market is segmented by product type, deployment mode, application, and end user, covering practice management, imaging, treatment planning, and patient communication software across cloud-based and on-premise deployment models and various dental specialty applications.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Product Type Analysis
Practice Management Software is projected to dominate the Europe Dental Software Market with 42.6% share in 2026, reflecting its foundational and essential role across scheduling, billing, patient records, and administrative workflow management for dental practices of all sizes and organizational structures. Dental Imaging Software is expected to register the highest CAGR of 12.4% during 2026-2035, driven by continued digital dentistry workflow adoption and growing integration of AI-enhanced diagnostic support capability within imaging analysis platforms.
By Deployment Mode Analysis
Cloud-Based deployment is anticipated to dominate the Europe Dental Software Market, accounting for 61.4% share in 2026, supported by growing practice preference for reduced IT infrastructure burden, improved software accessibility, and simplified update and support management, particularly valuable for smaller independent practices with limited dedicated IT resources. Cloud-Based deployment is also projected to register the highest CAGR as dental service organizations increasingly favor cloud platforms supporting centralized, multi-location software management and reporting capability.
By Application Analysis
General Dentistry is projected to lead the Europe Dental Software Market with an estimated 48.3% share in 2026, reflecting the broad base of general dental practices representing the largest segment of Europe's overall dental care delivery infrastructure. Oral and Maxillofacial Surgery is expected to register the fastest CAGR of 11.8% through 2035, driven by growing adoption of specialized treatment planning and advanced imaging software supporting increasingly complex surgical case planning and execution.
By End User Analysis
Solo/Small Dental Practices are projected to dominate the Europe Dental Software Market with 46.8% share in 2026, reflecting the continued substantial presence of independent dental practices across the European dental care landscape despite ongoing consolidation trends. Group Dental Practices and DSOs are expected to register the fastest CAGR of 13.6% through 2035, driven by continued consolidation trends requiring scalable, standardized, multi-location software solutions supporting centralized operational and clinical oversight.
The Europe Dental Software Market Report is segmented based on the following:
By Product Type
- Practice Management Software
- Dental Imaging Software
- Treatment Planning Software
- Patient Communication and Engagement Software
- Others
By Deployment Mode
By Application
- General Dentistry
- Orthodontics
- Endodontics
- Periodontics
- Oral and Maxillofacial Surgery
- Others
By End User
- Solo/Small Dental Practices
- Group Dental Practices and DSOs
- Hospitals and Dental Clinics
- Academic and Research Institutes
Country Analysis
Germany is poised to dominate the Europe Dental Software Market due to its advanced dental care infrastructure, strong presence of established dental technology companies, and rapid adoption of digital practice management and imaging solutions. Dental clinics across the country increasingly use integrated software for appointment scheduling, billing, patient records, treatment planning, and diagnostic workflows. France and the U.K. also represent important markets, supported by growing digitalization of dental practices and demand for cloud-based platforms. Italy and Spain are witnessing steady adoption as clinics modernize administrative and clinical processes. The Rest of Europe is expanding through increasing awareness of digital dentistry, wider use of electronic health records, and growing demand for efficient, connected, and patient-focused dental software solutions.
By Country
Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
Technology Analysis
Technology development is increasingly shaping competitiveness in the Europe Dental Software Market as vendors invest in AI-enhanced diagnostic imaging analysis, cloud-native practice management architecture supporting seamless multi-location deployment, and interoperability standards enabling integration across diverse dental imaging, treatment planning, and practice management software systems. Growing use of predictive analytics is supporting practice growth and patient retention insights for dental service organizations managing multiple practice locations. Opportunities are expanding for companies developing clinically validated AI diagnostic support tools, comprehensive integrated software ecosystems reducing multi-system management complexity, and GDPR-compliant data architecture supporting confident cross-border dental service organization data management. However, achieving robust interoperability across the historically fragmented European dental software vendor landscape remains an ongoing technical and industry coordination challenge.
Investment and White Space Analysis
Investment opportunities in the Europe Dental Software Market are expanding alongside continued dental service organization consolidation, accelerating digital dentistry workflow adoption, and growing patient demand for digital engagement tools. Significant white space exists in AI-enhanced diagnostic and clinical decision support tool development, integrated software ecosystems supporting dental service organization scalability, and GDPR-compliant cloud infrastructure supporting confident cross-border data management. Companies with strong clinical AI development capability, established relationships with growing dental service organizations, and robust data privacy compliance infrastructure are positioned to capture premium, longer-duration growth opportunities. However, data privacy compliance complexity under GDPR, along with the challenge of achieving interoperability across a historically fragmented vendor landscape, can constrain smaller vendors' ability to compete effectively for larger dental service organization software contracts.
Competitive Landscape
The Europe Dental Software Market is fragmented and increasingly competitive, comprising large diversified global dental technology companies with substantial European operations, specialized European dental software vendors with deep regional market knowledge, and emerging AI-focused dental diagnostic software startups. Competition centers on software integration and interoperability capability, AI-enhanced clinical diagnostic support functionality, GDPR compliance and data privacy infrastructure, and established relationships with growing dental service organizations and independent practices. Large diversified global companies benefit from broad product portfolios and substantial research and development resources, while specialized European vendors compete through deep regional regulatory knowledge and closer, more responsive client relationships. Companies increasingly differentiate through AI diagnostic capability and integrated ecosystem functionality rather than standalone practice management features alone.
Some of the prominent players in the Europe Dental Software Market are:
- Henry Schein One
- Dentsply Sirona Inc.
- Carestream Dental LLC
- Align Technology, Inc.
- Planmeca Oy
- Vatech Co., Ltd.
- 3Shape A/S
- exocad GmbH
- DentalMonitoring SAS
- Software of Excellence
- Dentally
- Pearl, Inc.
- Overjet
- Planet DDS
- Curve Dental
- Open Dental Software
- MOGO, Inc.
- iDentalSoft
- ACE Dental Software
- Denticon
- tab32
- Dovetail Dental Software
- Dental Intelligence
- Aerona Software
- Sensei Cloud
- CareStack
- Cloud 4 Dentists
- Dentrix
- Dentrix Ascend
- Apteryx Imaging
- Medit Corp.
- ACTEON Group
- Dürr Dental SE
- Owandy Radiology
- Cefla Medical Equipment S.p.A.
- CompuGroup Medical SE & Co. KGaA
- Solutio GmbH
- DAMPSOFT GmbH
- Evident GmbH
- Clinicminds Ltd.
- Other Key Players
Recent Developments
- February 2026: exocad launched PartialCAD 3.3 Chemnitz, introducing a split-denture workflow that allows dental professionals to design implant-based suprastructures and precisely fitting underlying bars through integrated digital workflows.
- February 2026: 3Shape introduced expanded AI-powered dental laboratory workflows within Dental System 2025, including AI bite alignment, automated tooth outlining, and margin-line detection to improve speed and accuracy in restorative design.
- April 2026: 3Shape received FDA 510(k) clearance for its Dx Plus and Dx Standard software. Dx Plus uses AI-assisted analysis to help detect caries, plaque, tooth wear, and gingival recession, while the platform was already being used across several international markets, including Europe.
- May 2026: exocad hosted Insights 2026 in Palma de Mallorca, Spain, highlighting product innovation, digital dentistry workflows, software advances, and clinical and laboratory applications for dental professionals worldwide.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 1.1 Bn |
| Forecast Value (2035) |
USD 2.8 Bn |
| CAGR (2026–2035) |
10.3% |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Product Type, By Deployment Mode, By Application, and By End User |
| Country Coverage |
Europe – Germany, France, The UK, Italy, Spain, Rest of Europe |
Frequently Asked Questions
How big is the Europe Dental Software Market?
▾ The Europe Dental Software Market is poised to bevalued at USD 1.1 Billion in 2026 and is projected to reach USD 2.8 Billion by 2035, reflecting continued dental service organization consolidation and accelerating digital dentistry workflow adoption.
What is the CAGR of the Europe Dental Software Market from 2026 to 2035?
▾ The market is projected to expand at a compound annual growth rate (CAGR) of 10.3% between 2026 and 2035, supported by continued consolidation, growing AI-enhanced diagnostic tool adoption, and rising patient demand for digital engagement.
What factors are driving the growth of the Europe Dental Software Market?
▾ Growth is driven by continued European dental service organization consolidation and group practice expansion, accelerating digital imaging and treatment planning workflow adoption, growing patient expectations for digital communication and booking convenience, and rising AI-enhanced diagnostic support tool integration.
What are the major trends in the Europe Dental Software Market?
▾ Major trends include growing adoption of cloud-based, subscription-model software platforms, increasing integration of patient-facing digital engagement tools, and rising development of AI-enhanced diagnostic and clinical decision support capability.
Who are the key players in the Europe Dental Software Market?
▾ Key market participants include Dentsply Sirona, Align Technology, Henry Schein One, Carestream Dental, and Planmeca Oy, among other global and specialized European dental software vendors.
How is the Europe Dental Software Market segmented?
▾ The market is segmented by product type, deployment mode, application, and end user, with demand analysis concentrated across Germany, the United Kingdom, France, Italy, Spain, and Rest of Europe.