France Food Processing Equipment Market Snapshot
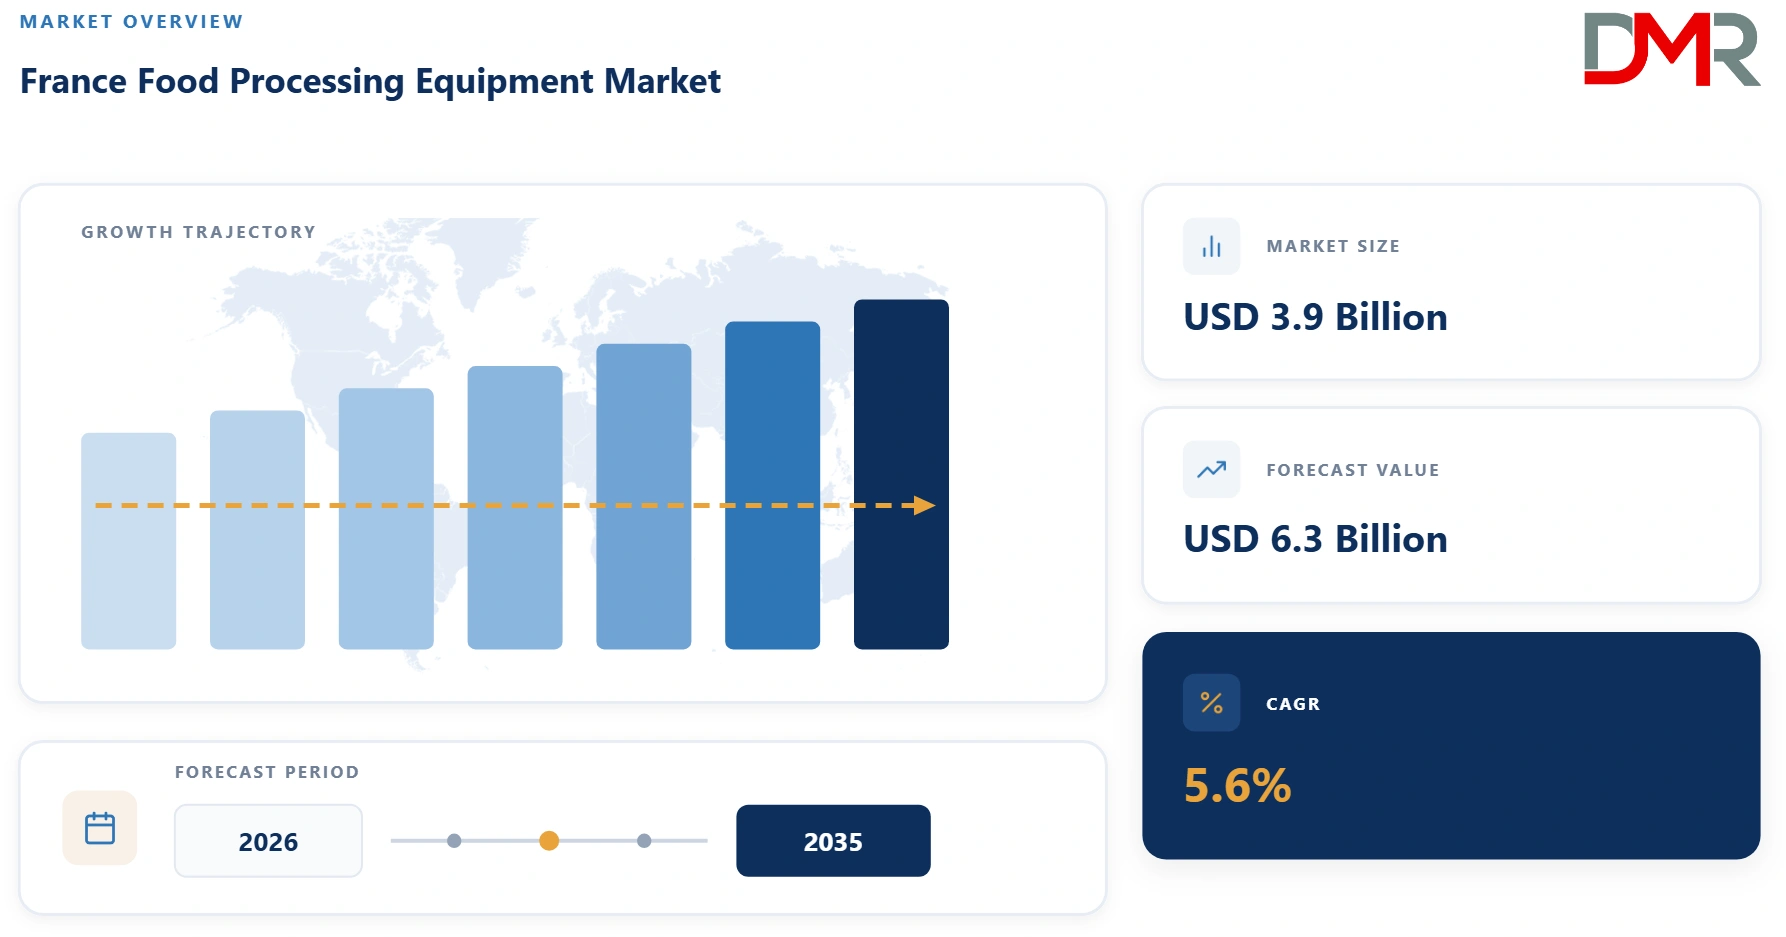
- France Food Processing Equipment Market Size in 2026: USD 3.9 Billion
- France Food Processing Equipment Market Size in 2035: USD 6.3 Billion
- France CAGR from 2026 to 2035: 5.6%
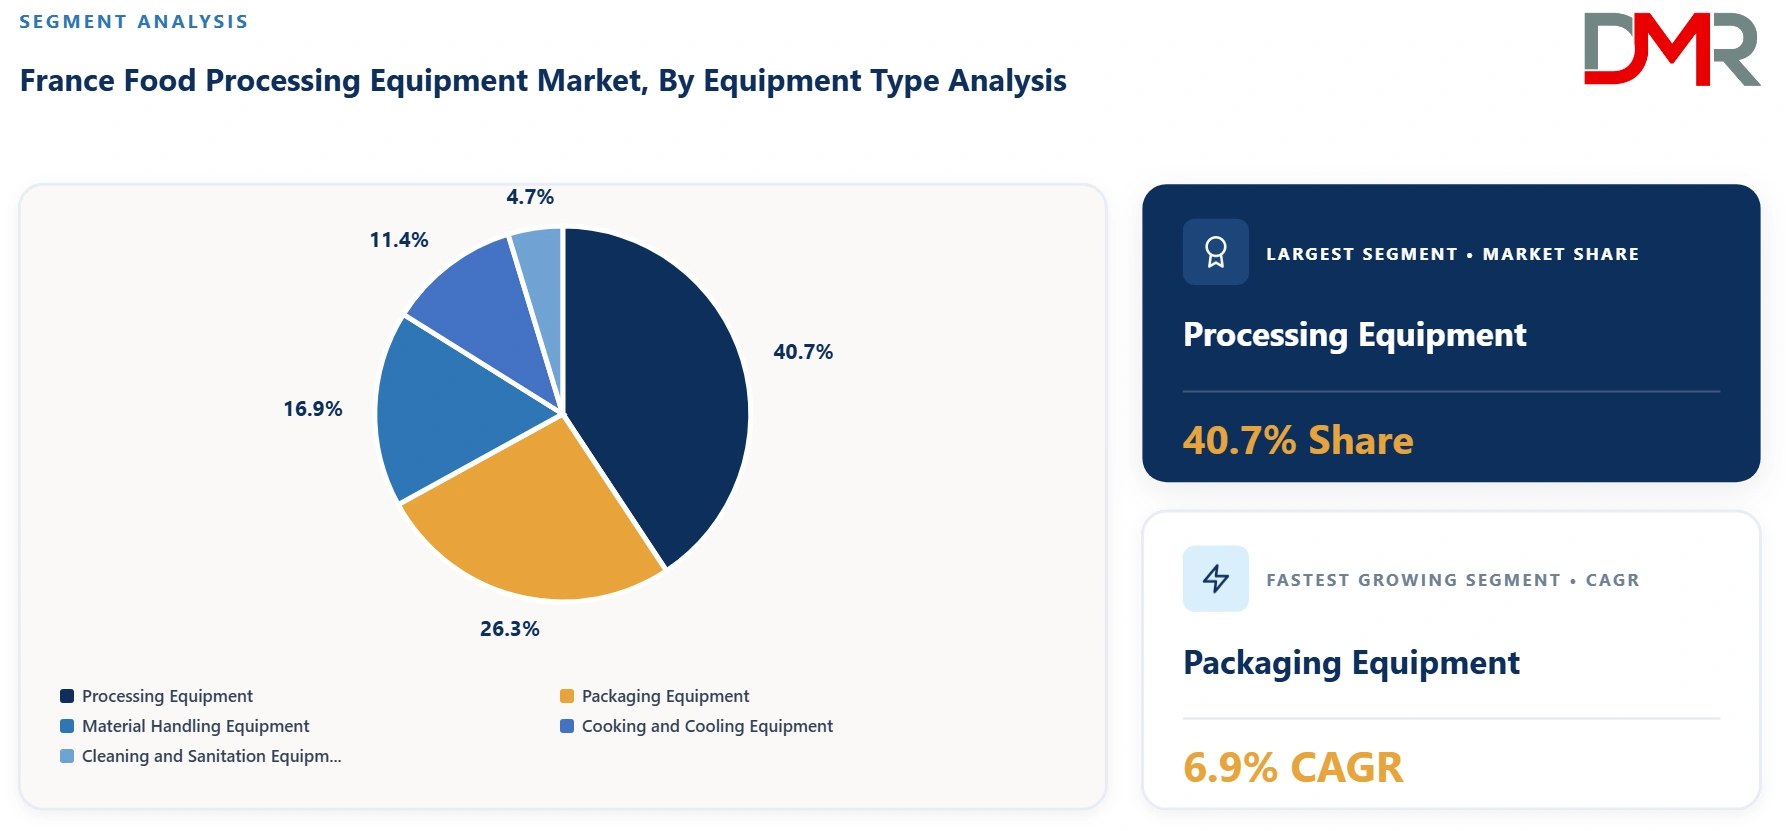
- Processing Equipment is the leading equipment type segment in 2026: 40.7%
- Automatic is the leading mode of operation segment in 2026: 51.9%
- Dairy Products is the leading food category segment in 2026: 27.4%
- Large-Scale Food Processors is the leading end user segment in 2026: 54.6%
What is the France Food Processing Equipment Market and its Market Size?
The France Food Processing Equipment Market is projected to be valued at USD 3.9 Billion in 2026 and is projected to reach USD 6.3 Billion by 2035, expanding at a CAGR of 5.6% during the forecast period.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Growth is being propelled by France's position as one of Europe's largest food and beverage manufacturing sectors, sustained modernization investment across the country's extensive dairy, bakery, wine, and processed food industries, and rising labor cost pressures that continue to make automation an increasingly compelling capital investment for processors of all sizes. The maturing of hygienic, energy-efficient automated equipment suited to France's stringent European Union food safety and environmental regulatory environment, growing processor investment in flexible, changeover-friendly equipment supporting France's traditionally diverse and artisanal-influenced food product landscape, and continued export-oriented capacity expansion among French food and beverage manufacturers serving both European and international markets are reshaping the market from simple equipment replacement cycles into more strategic, efficiency- and sustainability-oriented capital investment programs. Investment is accelerating as French processors balance automation modernization against rising energy costs and navigate an evolving European regulatory landscape covering food safety, sustainability, and packaging requirements.
Use Cases
- Automated Dairy Processing Line Modernization: French dairy cooperatives and processors invest in automated pasteurization, homogenization, and cheese-making equipment to expand capacity and improve consistency across the country's extensive and highly diverse cheese and dairy product portfolio.
- Bakery and Viennoiserie Production Automation: Industrial and craft bakery operators invest in automated mixing, proofing, and baking equipment to scale production of traditional French bakery products while managing rising labor costs and addressing recruitment challenges in physically demanding bakery production roles.
- Wine and Beverage Processing Equipment Upgrades: Wine producers and beverage manufacturers invest in modernized fermentation, filtration, and bottling equipment to improve production consistency and capacity, supporting both domestic consumption and France's significant wine and spirits export industry.
- Flexible, Changeover-Friendly Equipment for Diverse Product Portfolios: Food manufacturers serving France's diverse regional and artisanal food product landscape invest in flexible processing and packaging equipment capable of rapid changeover between product formulations and package formats, supporting smaller batch production runs alongside larger-scale manufacturing.
Key Takeaways
- Market Size: The France Food Processing Equipment Market is anticipated to be valued at USD 3.9 Billion in 2026 and is forecast to reach USD 6.3 Billion by 2035, expanding at a CAGR of 5.6%.
- Growth Outlook: Market expansion is sustained by continued modernization investment across France's extensive dairy, bakery, and wine processing industries, rising labor cost pressures favoring automation, and growing export-oriented capacity expansion among French food and beverage manufacturers.
- Primary Growth Drivers: Rising food manufacturing labor costs and recruitment challenges, sustained modernization investment across France's traditional food processing sectors, growing export demand for French food and beverage products, and tightening European Union food safety and sustainability regulatory requirements are accelerating equipment investment.
- By Equipment Type Analysis: Processing Equipment is projected to lead the equipment type segment with a 40.7% share in 2026, reflecting its central role across France's diverse dairy, bakery, and beverage processing operations. Packaging Equipment is the fastest-growing equipment type segment at 6.9% CAGR, driven by rising demand for flexible, sustainable packaging line automation supporting evolving European packaging regulation.
- By Mode of Operation Analysis: Automatic equipment is expected to dominate with a 51.9% share in 2026, supported by processor investment in labor-reducing automation. Automatic is also the fastest-growing mode of operation segment at 7.1% CAGR, as rising labor costs and recruitment challenges continue to favor higher levels of automation across French processing facilities.
- By Food Category Analysis: Dairy Products is expected to command a 27.4% share in 2026, underpinned by France's extensive and diverse dairy and cheese-making industry. Beverages is the fastest-growing food category segment at 6.8% CAGR, driven by continued modernization investment across the wine, spirits, and broader beverage manufacturing sector.
- By End User Analysis: Large-Scale Food Processors are projected to dominate with a 54.6% share in 2026, reflecting greater capital availability for comprehensive equipment modernization programs. Small and Medium-Sized Processors is the fastest-growing end user segment at 6.9% CAGR, driven by falling automation equipment costs and growing availability of flexible financing options suited to France's substantial base of smaller regional and artisanal food producers.
Key Drivers in the France Food Processing Equipment Market
Rising Labor Costs and Recruitment Challenges Across French Food Manufacturing
Sustained increases in French labor costs, combined with ongoing recruitment challenges for physically demanding food processing roles, are driving continued investment in automated processing equipment across the French food and beverage manufacturing sector. France's relatively high labor cost structure compared to some other European manufacturing locations increases the financial incentive for processors to invest in automation to maintain cost competitiveness, particularly for export-oriented manufacturers competing in international markets. As labor availability and cost pressures persist, automation investment is increasingly viewed as essential to maintaining production efficiency and competitiveness.
Sustained Modernization Investment Across France's Traditional Food Processing Sectors
France's extensive dairy, bakery, wine, and processed food manufacturing base continues to require ongoing capital investment to modernize aging equipment and expand production capacity, particularly as processors seek to preserve traditional product quality and craftsmanship while achieving greater production efficiency and consistency. This sustained modernization need across France's large and diverse food processing industry base provides a consistent underlying demand driver for processing equipment investment, independent of shorter-term economic cycles affecting discretionary capital expenditure.
Restraints in the France Food Processing Equipment Market
High Capital Costs and Retrofit Complexity Amid France's Diverse, Often Smaller-Scale Processing Base
Significant upfront capital investment required for modern automated processing equipment represents a meaningful restraint on the France Food Processing Equipment Market, particularly given the country's substantial base of smaller regional and artisanal food producers operating with more constrained capital budgets relative to large-scale industrial processors. Many smaller and traditional processing facilities also face physical layout constraints and outdated infrastructure that complicate automation retrofits, and processors must weigh automation investment against preserving the traditional production methods that often underpin the premium positioning and quality reputation of many French food and beverage products.
Growth Opportunities in the France Food Processing Equipment Market
Flexible, Small-Batch Automation for Artisanal and Regional Food Producers
Growing interest among France's substantial base of smaller and artisanal food producers in accessing automation benefits without compromising traditional production quality presents a significant opportunity for equipment vendors offering flexible, smaller-scale automation solutions suited to lower-volume, higher-variability production environments. Vendors developing equipment specifically designed for smaller batch sizes and frequent product changeovers can capture demand from this substantial and traditionally underserved segment of the French food processing industry.
Energy-Efficient Equipment for Managing Rising European Industrial Energy Costs
Rising industrial energy costs across France and broader Europe present a substantial opportunity for equipment vendors offering energy-efficient processing, refrigeration, and cleaning equipment capable of meaningfully reducing processor operating costs. Vendors demonstrating clear energy savings and favorable payback periods through efficient equipment design are well positioned to capture equipment replacement and modernization contracts, particularly given the significant energy intensity of French dairy, bakery, and beverage processing operations.
Trends in the France Food Processing Equipment Market
Growing Integration of Sustainability and Energy Efficiency into Equipment Purchasing Decisions
French food processors are increasingly incorporating sustainability and energy efficiency criteria into equipment purchasing decisions, reflecting both rising energy costs and growing corporate and regulatory emphasis on environmental performance across the European food manufacturing sector. Equipment vendors are responding by emphasizing energy consumption data, water usage efficiency, and recyclability of equipment components as competitive differentiators, alongside traditional performance and reliability considerations in the equipment purchasing decision process.
Rising Adoption of Flexible, Multi-Format Packaging Equipment
French food and beverage manufacturers are increasingly investing in flexible packaging equipment capable of handling multiple package formats and sizes on a single production line, supporting both the product diversity characteristic of the French food industry and the need to adapt packaging formats in response to evolving European Union packaging and packaging waste regulation. This flexibility trend is particularly relevant as processors navigate transitions toward more sustainable and recyclable packaging formats without requiring complete line replacement.
Research Scope and Analysis
The France Food Processing Equipment Market is segmented by equipment type, mode of operation, food category, and end user, covering processing, packaging, material handling, cooking and cooling, and cleaning and sanitation equipment across dairy, bakery, meat, beverage, and produce processing categories.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Equipment Type Analysis
Processing Equipment is projected to dominate the France Food Processing Equipment Market with approximately 40.7% share in 2026, reflecting its central role across the country's diverse dairy, bakery, meat, and beverage processing operations. Packaging Equipment is expected to register the highest CAGR of 6.9% during 2026-2035, driven by rising processor investment in flexible, multi-format packaging line automation supporting evolving European Union packaging sustainability regulation and requirements.
By Mode of Operation Analysis
Automatic equipment is anticipated to dominate the France Food Processing Equipment Market by mode of operation, accounting for approximately 51.9% share in 2026, supported by sustained processor investment in labor-reducing, throughput-improving automated systems amid persistent labor cost pressures. Automatic equipment is also projected to register the highest CAGR of 7.1% between 2026 and 2035, as continued labor cost increases and recruitment challenges favor higher levels of automation across both large-scale industrial and mid-sized French processing facilities.
By Food Category Analysis
Dairy Products is expected to lead the France Food Processing Equipment Market by food category, accounting for approximately 27.4% share in 2026, underpinned by France's extensive and diverse dairy and cheese-making industry requiring specialized processing equipment across a wide range of traditional and industrial-scale dairy products. Beverages is projected to achieve the fastest CAGR of 6.8% during 2026-2035, driven by continued modernization investment across France's significant wine, spirits, and broader beverage manufacturing sector.
By End User Analysis
Large-Scale Food Processors are projected to dominate the France Food Processing Equipment Market with approximately 54.6% share in 2026, reflecting greater capital availability for comprehensive equipment modernization and automation investment programs. Small and Medium-Sized Processors are expected to register the fastest CAGR of 6.9% through 2035, driven by falling automation equipment costs and growing availability of flexible financing solutions suited to France's substantial base of smaller regional and artisanal food producers.
The France Food Processing Equipment Market Report is segmented based on the following:
By Equipment Type
- Processing Equipment
- Packaging Equipment
- Material Handling Equipment
- Cooking and Cooling Equipment
- Cleaning and Sanitation Equipment
By Mode of Operation
- Automatic
- Semi-Automatic
- Manual
By Food Category
- Dairy Products
- Bakery and Confectionery
- Meat, Poultry and Seafood
- Beverages
- Fruits and Vegetables
- Others
By End User
- Large-Scale Food Processors
- Small and Medium-Sized Processors
- Artisanal and Specialty Food Producers
Technology Analysis
Technology development is increasingly shaping competitiveness in the France Food Processing Equipment Market as vendors invest in energy-efficient processing systems, flexible automation suited to smaller-batch and artisanal production, and digital monitoring technology supporting both operational efficiency and European food safety traceability requirements. Growing integration of predictive maintenance analytics is helping processors reduce unplanned downtime across both large industrial facilities and smaller regional processing operations. Opportunities are expanding for vendors developing equipment specifically suited to France's traditional food production methods, energy-efficient refrigeration and thermal processing systems addressing rising European energy costs, and flexible packaging equipment supporting evolving sustainability regulation. However, achieving automation solutions that preserve the traditional production characteristics valued in many French food and beverage categories, while still improving efficiency, remains a distinctive technical challenge for equipment vendors serving this market.
Investment and White Space Analysis
Investment opportunities in the France Food Processing Equipment Market are expanding alongside sustained modernization needs across France's extensive dairy, bakery, and beverage processing industries, rising labor cost pressures, and growing export-oriented capacity investment. Significant white space exists in flexible, small-batch automation solutions for artisanal and regional producers, energy-efficient equipment addressing rising European industrial energy costs, and flexible packaging equipment supporting evolving European Union sustainability regulation. Vendors with strong understanding of France's traditional food production requirements, energy efficiency credentials, and flexible commercial financing models are positioned to capture premium, longer-duration contracts across a broad base of processor sizes. However, high upfront capital costs, retrofit complexity amid France's diverse and often smaller-scale processing base, and the challenge of automating without compromising traditional production quality can constrain adoption pace, particularly among smaller, artisanal-oriented processors.
Competitive Landscape
The France Food Processing Equipment Market is moderately consolidated and increasingly competitive, comprising large diversified global food processing equipment manufacturers, specialty French and European equipment suppliers with deep expertise in traditional food production categories such as dairy, bakery, and wine, and international automation companies serving the broader food processing sector. Competition centers on food-grade equipment design and sanitation compliance, energy efficiency, flexibility suited to France's diverse product landscape, and breadth of after-sales service and technical support. Large diversified equipment manufacturers benefit from broad product portfolios and established processor relationships, while specialty French and European suppliers compete on deep category-specific expertise, particularly in traditional applications such as cheese-making and bakery production, and closer, more responsive client service relationships. Companies increasingly differentiate through flexible, small-batch automation capability and energy-efficient equipment design rather than equipment sales alone.
Some of the prominent players in the France Food Processing Equipment Market are:
- GEA Group
- Tetra Pak
- Bühler Group
- JBT Marel
- Alfa Laval
- Krones AG
- SPX FLOW
- Sidel
- Clextral
- MULTIVAC Group
- KHS Group
- Heat and Control
- BAADER Group
- The Middleby Corporation
- Bucher Industries
- Probat
- FEMIA Industrie
- MCA Process
- Boccard
- Serac Group
- Pierre Guérin
- VMI
- Palamatic Process
- TMI
- PCM Group
- ACTINI Group
- Della Toffola Group
- Syntegon Technology
- SACMI
- Coesia Group
- Duravant
- Handtmann Group
- MULTIVAC France
- Stephan Machinery
- FAM STUMABO
- Urschel Laboratories
- Risco S.p.A.
- Vemag Maschinenbau
- TNA Solutions
- Andritz AG
- Other Key Players
Recent Developments
- July 2026: GEA Group expanded its portfolio of energy-efficient food processing solutions in France, focusing on automation, heat recovery, and reduced energy consumption across production lines.
- June 2026: Clextral advanced its extrusion and food processing technology portfolio, supporting French manufacturers seeking higher production flexibility for plant-based proteins, snacks, and specialty foods.
- May 2026: Sidel strengthened its automated processing and packaging solutions for French food and beverage manufacturers, emphasizing digital monitoring, production efficiency, and sustainable operations.
- April 2026: Tetra Pak expanded its advanced food processing technology offerings, focusing on automation, energy efficiency, food safety, and optimized production performance for French manufacturers.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 3.9 Bn |
| Forecast Value (2035) |
USD 6.3 Bn |
| CAGR (2026–2035) |
5.6% |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Equipment Type, By Mode of Operation, By Food Category, By End User |
| Country Coverage |
France |
Frequently Asked Questions
How big is the France Food Processing Equipment Market?
▾ The France Food Processing Equipment Market is valued at USD 3.9 Billion in 2026 and is projected to reach USD 6.3 Billion by 2035, reflecting sustained investment in automated and modernized processing equipment across France's dairy, bakery, wine, and broader food manufacturing industries.
What is the CAGR of the France Food Processing Equipment Market from 2026 to 2035?
▾ The market is projected to expand at a compound annual growth rate (CAGR) of 5.6% between 2026 and 2035, supported by rising labor costs, sustained modernization investment across traditional food processing sectors, and growing export-oriented capacity expansion.
What factors are driving the growth of the France Food Processing Equipment Market?
▾ Growth is driven by rising food manufacturing labor costs and recruitment challenges, sustained modernization investment across France's traditional dairy, bakery, and wine processing industries, growing export demand for French food and beverage products, and tightening European Union food safety and sustainability regulatory requirements.
What are the major trends in the France Food Processing Equipment Market?
▾ Major trends include growing integration of sustainability and energy efficiency into equipment purchasing decisions, rising adoption of flexible, multi-format packaging equipment, and continued investment in automation solutions tailored to France's traditional and artisanal food production methods.
Who are the key players in the France Food Processing Equipment Market?
▾ Key market participants include GEA Group, Tetra Pak, Bühler Group, Alfa Laval, and JBT Corporation, among other diversified global and specialty French and European food processing equipment manufacturers.
How is the France Food Processing Equipment Market segmented?
▾ The market is segmented by equipment type, mode of operation, food category, and end user, with demand analysis concentrated across Brittany, Normandy, Nouvelle-Aquitaine, and the Île-de-France region.