Italy Pasta & Bakery Ingredients Market Snapshot
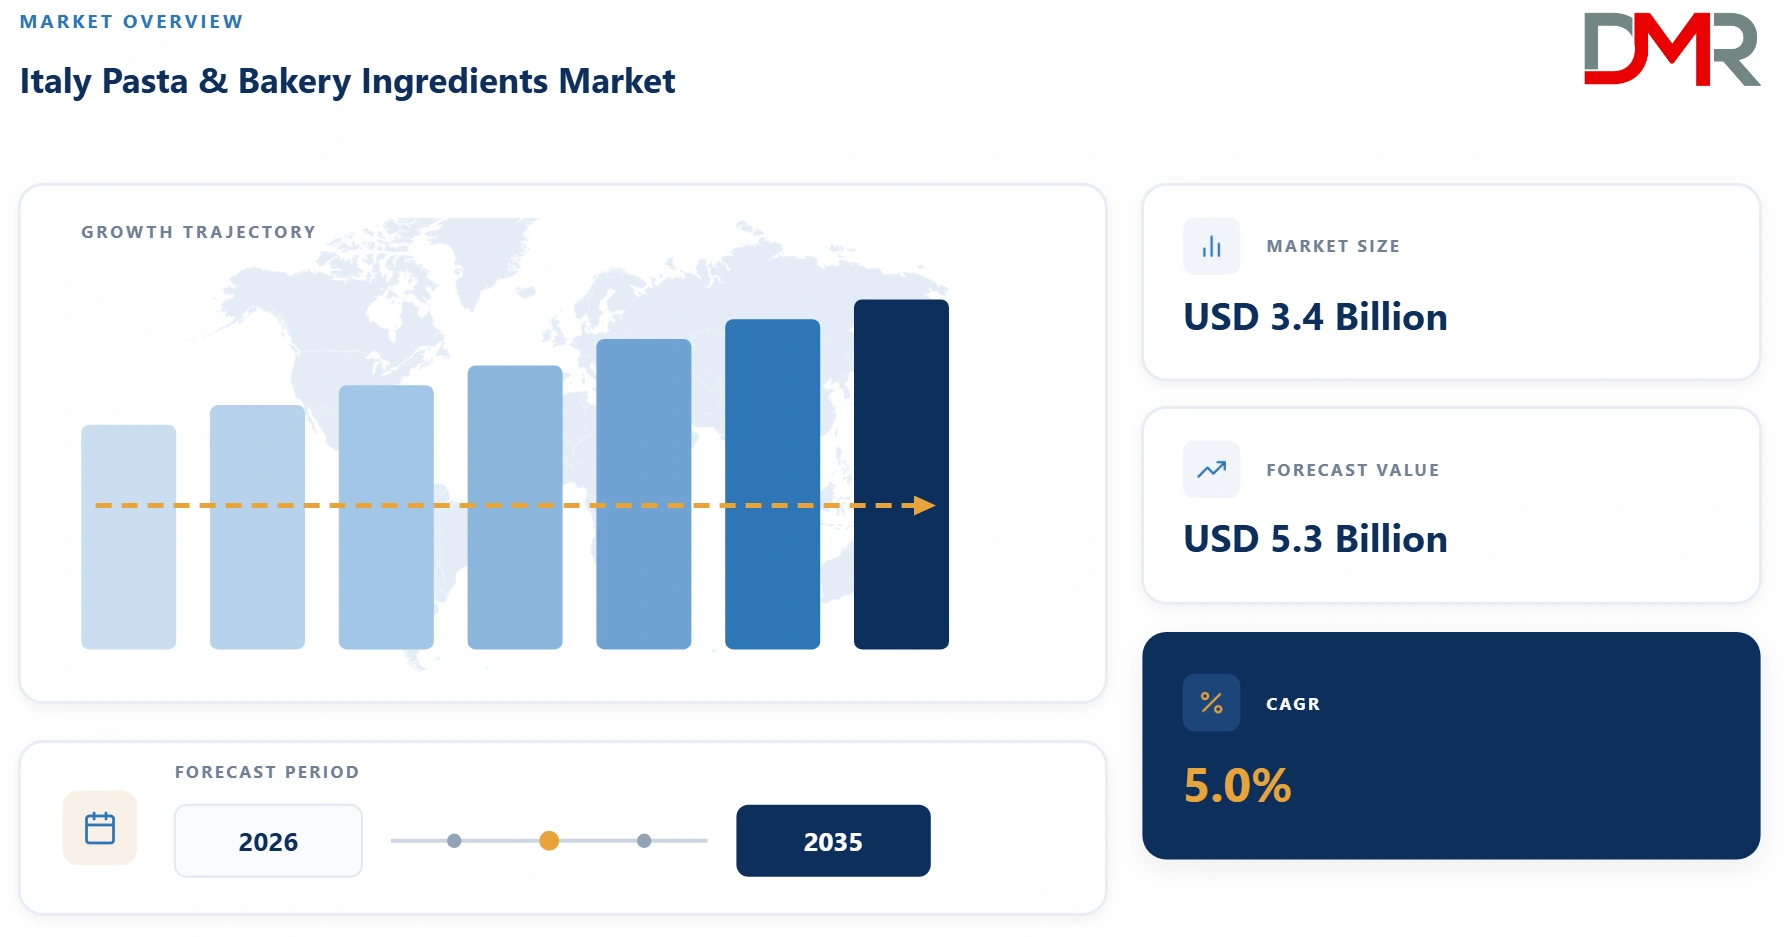
- Italy Pasta & Bakery Ingredients Market Size in 2026: USD 3.4 Billion
- Italy Pasta & Bakery Ingredients Market Size in 2035: USD 5.3 Billion
- Italy CAGR from 2026 to 2035: 5.0%
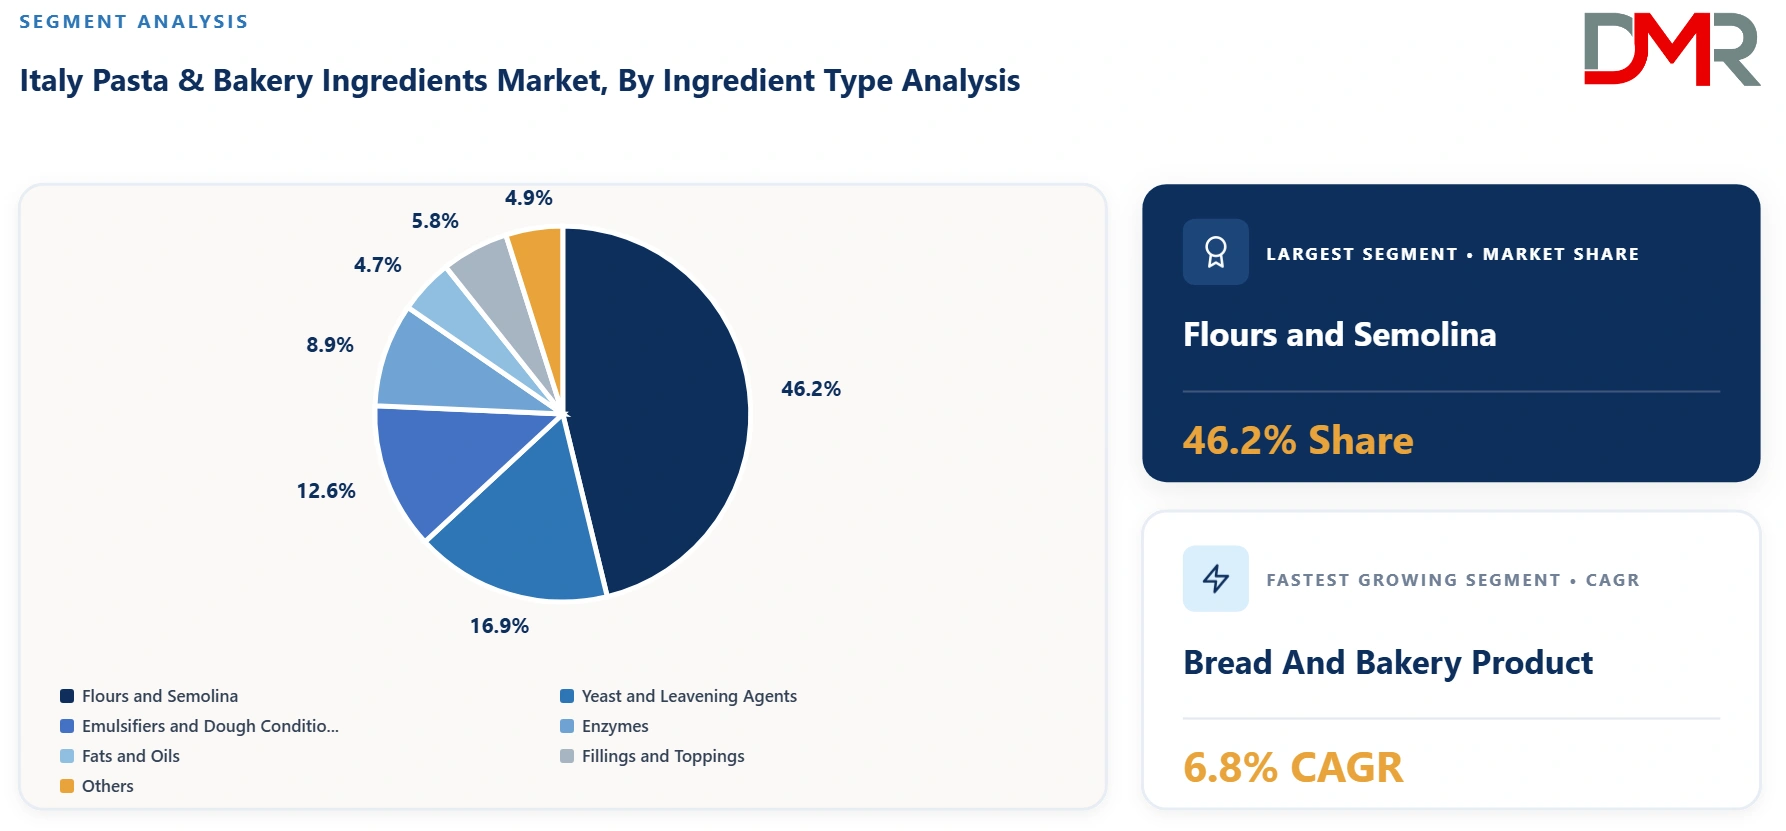
- Flours and Semolina is the leading ingredient type segment in 2026: 46.2%
- Durum Wheat is the leading source segment in 2026: 51.8%
- Dried and Fresh Pasta is the leading application segment in 2026: 38.4%
- Industrial Pasta and Bakery Manufacturers is the leading end user segment in 2026: 64.7%
What is the Italy Pasta & Bakery Ingredients Market and its Market Size?
The Italy Pasta & Bakery Ingredients Market is projected to be valued at USD 3.4 Billion in 2026 and is projected to reach USD 5.3 Billion by 2035, expanding at a CAGR of 5.0% during the forecast period.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Growth is being propelled by Italy's position as the world's largest pasta producer and exporter, deeply rooted culinary tradition supporting sustained domestic bread, pizza, and bakery consumption, and continued strength of Italian durum wheat semolina and specialty flour milling as a foundation of both artisanal and industrial pasta and bakery production. The maturing of gluten-free and alternative grain ingredient technologies capable of meeting the exacting texture and taste standards demanded by Italian consumers, growing international export demand for authentic Italian pasta and bakery products supported by protected geographical indication and quality certification systems, and continued investment in specialty flour and dough ingredient innovation supporting both traditional pastifici and large-scale industrial producers are reshaping the market from a purely commodity flour-based supply category into a more quality- and provenance-differentiated ingredient industry. Investment is accelerating as Italian ingredient suppliers navigate durum wheat supply volatility while pursuing continued innovation in both traditional and modern pasta and bakery product categories.
Use Cases
- Durum Wheat Semolina Sourcing for Premium and Export Pasta Production: Italian pasta manufacturers, both large industrial producers and smaller artisanal pastifici, source high-quality durum wheat semolina meeting strict protein and gluten quality specifications required for premium pasta production destined for both domestic consumption and substantial international export markets.
- Specialty Flour Blends for Traditional Regional Bread and Bakery Products: Italian bakeries and industrial bread manufacturers use specialty flour blends tailored to traditional regional bread varieties, reflecting Italy's diverse regional bakery culinary heritage spanning numerous protected and traditional bread product categories.
- Gluten-Free and Alternative Grain Pasta and Bakery Ingredient Development: Ingredient suppliers develop gluten-free flour blends and alternative grain formulations, such as rice, corn, and legume-based alternatives, enabling pasta and bakery manufacturers to serve growing consumer demand for gluten-free products without compromising the taste and texture standards associated with traditional Italian products.
- Pizza Dough and Focaccia Ingredient Systems for Foodservice and Retail: Ingredient suppliers develop specialized flour, yeast, and dough conditioner systems optimized for pizza and focaccia production, serving both Italy's extensive pizzeria foodservice sector and growing retail frozen and chilled pizza product categories.
Key Takeaways
- Market Size: The Italy Pasta & Bakery Ingredients Market is anticipated to be valued at USD 3.4 Billion in 2026 and is forecast to reach USD 5.3 Billion by 2035, expanding at a CAGR of 5.0%.
- Growth Outlook: Market expansion is sustained by Italy's position as the world's leading pasta producer and exporter, deeply rooted domestic bakery and pasta consumption tradition, and continued international export demand for authentic Italian pasta and bakery products.
- Primary Growth Drivers: Italy's global leadership in pasta production and export, sustained international demand for authentic Italian bakery and pasta products supported by quality certification systems, growing gluten-free and alternative grain product innovation, and continued specialty ingredient investment supporting premiumization are accelerating market growth.
- By Ingredient Type Analysis: Flours and Semolina is projected to lead the ingredient type segment with a 46.2% share in 2026, reflecting its foundational role across pasta and bakery production. Enzymes is the fastest-growing ingredient type segment at 6.8% CAGR, driven by rising manufacturer investment in dough performance and shelf-life optimization technology.
- By Source Analysis: Durum Wheat is expected to dominate with a 51.8% share in 2026, supported by its essential role in Italy's globally significant pasta production industry. Alternative Grains and Gluten-Free is the fastest-growing source segment at 8.6% CAGR, driven by rising consumer demand for gluten-free pasta and bakery products.
- By Application Analysis: Dried and Fresh Pasta is poised to lead with a 38.4% share in 2026, reflecting Italy's position as the world's largest pasta producer. Biscuits and Confectionery is the fastest-growing application segment at 6.2% CAGR, driven by continued innovation and export growth in Italian biscuit and confectionery product categories.
- By End User Analysis: Industrial Pasta and Bakery Manufacturers are projected to dominate with a 64.7% share in 2026, reflecting the scale of Italy's large industrial pasta and bakery production base. Artisanal Bakeries and Pastifici is the fastest-growing end user segment at 6.1% CAGR, driven by continued consumer demand for premium, traditionally produced pasta and bakery products.
Key Drivers in the Italy Pasta & Bakery Ingredients Market
Italy's Global Leadership in Pasta Production and Export
Italy's position as the world's largest producer and exporter of pasta provides a substantial and durable foundation for the country's pasta and bakery ingredients market. Italian pasta manufacturers, supported by an extensive domestic durum wheat milling and semolina production infrastructure, serve both massive domestic consumption and substantial international export demand across European, North American, and increasingly global markets. This established global leadership position, built over generations of production expertise and continually reinforced by strong brand recognition for Italian pasta quality, provides sustained and structurally durable demand for the high-quality durum wheat semolina and related ingredients underpinning Italian pasta production.
Sustained International Demand for Authentic Italian Bakery and Pasta Products
Growing international consumer appetite for authentic Italian food products, supported by protected geographical indication certifications and Italy's strong culinary reputation, continues to drive export demand for Italian pasta, bread, and bakery products. This sustained international demand encourages continued investment in ingredient quality, traceability, and certification systems that support authentic Italian product positioning in international markets, reinforcing a virtuous cycle of quality investment and export market strength across the Italian pasta and bakery value chain.
Restraints in the Italy Pasta & Bakery Ingredients Market
Durum Wheat Supply Volatility and Import Dependency
Italy's domestic durum wheat production, while substantial, does not fully meet the raw material requirements of its massive pasta manufacturing industry, requiring significant durum wheat imports that expose Italian pasta and bakery ingredient suppliers to international commodity price volatility and supply chain risk tied to global durum wheat harvest conditions, particularly in key exporting regions such as Canada and other Mediterranean-adjacent producing countries. This import dependency and associated price volatility represents a meaningful restraint on the Italy Pasta & Bakery Ingredients Market, complicating cost management and long-term pricing strategies for both ingredient suppliers and pasta manufacturers.
Growth Opportunities in the Italy Pasta & Bakery Ingredients Market
Premium and Protected-Origin Ingredient Certification for Export Differentiation
Growing international consumer willingness to pay premium pricing for verified authentic, protected-origin Italian pasta and bakery products presents a significant opportunity for ingredient suppliers to develop and market certified, traceable durum wheat and specialty flour ingredients that support premium product positioning in export markets. Suppliers capable of providing verified origin documentation and quality certification aligned with Italy's protected geographical indication systems can capture premium pricing and stronger, longer-term relationships with both domestic pastifici and international brand customers.
Gluten-Free and Functional Bakery Ingredient Innovation
Rising global and domestic Italian consumer demand for gluten-free and functional bakery and pasta products presents a substantial opportunity for ingredient suppliers developing alternative grain and functional ingredient formulations capable of replicating the taste, texture, and cooking performance of traditional wheat-based Italian products. Suppliers achieving genuine performance parity with traditional formulations, a particularly demanding standard given Italian consumers' strong quality expectations for pasta and bakery products, can capture significant market share in this fast-growing product category.
Trends in the Italy Pasta & Bakery Ingredients Market
Growing Investment in Traceability and Quality Certification Systems
Italian pasta and bakery ingredient suppliers are increasingly investing in digital traceability and quality certification systems that verify durum wheat origin, milling process, and quality specifications, responding to both regulatory requirements and growing international buyer and consumer demand for verified authenticity in Italian food products. This trend reflects the broader importance of provenance and quality verification in supporting Italy's premium positioning within global pasta and bakery export markets.
Consolidation Among Italian Milling and Ingredient Companies
The Italy Pasta & Bakery Ingredients Market is experiencing continued consolidation as larger Italian milling and ingredient companies acquire smaller regional mills and specialty ingredient producers to achieve greater production scale, broaden ingredient portfolio breadth spanning traditional and gluten-free categories, and strengthen relationships with both large industrial pasta manufacturers and growing artisanal and export-oriented pastifici customer segments.
Research Scope and Analysis
The Italy Pasta & Bakery Ingredients Market is segmented by ingredient type, source, application, and end user, covering flours, semolina, yeast, emulsifiers, enzymes, durum and common wheat, alternative grains, and pasta, bread, pizza, and confectionery applications across industrial and artisanal end users.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Ingredient Type Analysis
Flours and Semolina is projected to dominate the Italy Pasta & Bakery Ingredients Market with 46.2% share in 2026, reflecting its foundational and irreplaceable role across both Italy's massive pasta production industry and its extensive bread and bakery product categories. Enzymes is expected to register the highest CAGR of 6.8% during 2026-2035, driven by rising manufacturer investment in dough performance, texture, and shelf-life optimization technology across both industrial and artisanal production.
By Source Analysis
Durum Wheat is anticipated to dominate the Italy Pasta & Bakery Ingredients Market by source, accounting for 51.8% share in 2026, supported by its essential and irreplaceable role in Italy's globally significant pasta production industry, which relies on durum wheat semolina's unique protein and cooking performance characteristics. Alternative Grains and Gluten-Free sourcing is projected to register the highest CAGR of 8.6% between 2026 and 2035, driven by rising domestic and international consumer demand for gluten-free pasta and bakery products.
By Application Analysis
Dried and Fresh Pasta is projected to lead the Italy Pasta & Bakery Ingredients Market with an estimated 38.4% share in 2026, reflecting Italy's position as the world's largest pasta producer and the resulting scale of durum wheat semolina and related ingredient consumption. Biscuits and Confectionery is expected to register the fastest CAGR of 6.2% through 2035, driven by continued product innovation and sustained export growth in Italy's significant biscuit and confectionery product categories.
By End User Analysis
Industrial Pasta and Bakery Manufacturers are projected to dominate the Italy Pasta & Bakery Ingredients Market with 64.7% share in 2026, reflecting the substantial scale of Italy's large industrial pasta and bakery production sector serving both domestic and export markets. Artisanal Bakeries and Pastifici are expected to register the fastest CAGR of 6.1% through 2035, driven by continued consumer demand for premium, traditionally produced pasta and bakery products commanding higher per-unit ingredient value.
The Italy Pasta & Bakery Ingredients Market Report is segmented based on the following:
By Ingredient Type
- Flours and Semolina
- Yeast and Leavening Agents
- Emulsifiers and Dough Conditioners
- Enzymes
- Fats and Oils
- Fillings and Toppings
- Others
By Source
- Durum Wheat
- Common Wheat
- Alternative Grains and Gluten-Free
- Others
By Application
- Dried and Fresh Pasta
- Bread and Bakery Products
- Pizza and Focaccia
- Biscuits and Confectionery
- Others
By End User
- Industrial Pasta and Bakery Manufacturers
- Artisanal Bakeries and Pastifici
- Foodservice Operators
Technology Analysis
Technology development is increasingly shaping competitiveness in the Italy Pasta & Bakery Ingredients Market as milling companies invest in advanced grain sorting, blending, and quality analysis technology to consistently deliver the precise protein and gluten specifications required for premium pasta and bakery production. Growing use of digital traceability systems is supporting the origin and quality verification increasingly demanded by international buyers of authentic Italian pasta and bakery products. Opportunities are expanding for suppliers investing in alternative grain processing technology capable of achieving genuine taste and texture parity with traditional wheat-based products, as well as enzyme and dough conditioner innovation supporting both artisanal and large-scale industrial production efficiency. However, achieving consistent quality and performance while managing durum wheat supply volatility remains a persistent operational and technical challenge across the industry.
Investment and White Space Analysis
Investment opportunities in the Italy Pasta & Bakery Ingredients Market are expanding alongside Italy's global leadership in pasta production and export, sustained international demand for authentic Italian bakery products, and growing gluten-free and alternative grain product innovation. Significant white space exists in premium and protected-origin ingredient certification for export differentiation, gluten-free and functional bakery ingredient innovation achieving genuine taste and texture parity, and digital traceability systems supporting authenticity verification for export markets. Suppliers with strong durum wheat quality and sourcing relationships, established export market brand positioning, and gluten-free innovation capability are positioned to capture premium, longer-duration contracts. However, durum wheat supply volatility and import dependency, along with consolidation-driven competitive pressure, can constrain margins for smaller, regionally concentrated ingredient suppliers.
Competitive Landscape
The Italy Pasta & Bakery Ingredients Market is moderately consolidated and competitive, comprising large diversified Italian milling and ingredient companies, specialty gluten-free and alternative grain ingredient developers, and regional and family-owned mills serving traditional and artisanal pasta and bakery producers. Competition centers on durum wheat sourcing quality and scale, traceability and certification capability, gluten-free and alternative grain innovation, and established relationships with both large industrial manufacturers and Italy's substantial artisanal pastifici and bakery segment. Large diversified Italian companies benefit from established brand recognition, broad product portfolio breadth, and strong export market relationships, while regional and specialty mills compete on traditional product authenticity and closer relationships with artisanal producers. Companies increasingly differentiate through verified origin certification, gluten-free innovation, and premium ingredient positioning rather than commodity flour supply alone.
Some of the prominent players in the Italy Pasta & Bakery Ingredients Market are:
- Barilla Group
- IRCA Group
- Puratos Italia
- CSM Ingredients Italia
- AB Mauri Italy
- Italmill
- Lesaffre Italia
- IREKS Italia
- Molino Casillo
- Agugiaro & Figna Molini
- Molino Spadoni
- Molino Dallagiovanna
- Molino Grassi
- Molino Magri
- Molini Pivetti
- Mulino Padano
- Molino Rossetto
- Molini Bongiovanni
- Molino Quaglia
- Molino Caputo
- Molino Pasini
- Molino Vigevano
- Molino Naldoni
- Molino Verrini
- Il Granaio delle Idee
- Promix
- SACA Italia
- Eurovo Group
- Cereal Docks
- Eridania Italia
- Cargill Italia
- ADM Italia
- Bunge Italia
- Kerry Italia
- Döhler Italia
- Givaudan Italia
- Symrise Italia
- Zuegg
- Sacco System
- Brenntag Italia
- Other Key Players
Recent Developments
- January 2026: Puratos announced Puratos Cascarano, a joint venture between Puratos Italia and Cascarano Vincenzo, strengthening its Italian presence and expanding local support, ingredient solutions, and services for bakers, patissiers, and chocolatiers.
- December 2025: Nexture announced the acquisition of Italian ingredients group Sipral Padana, expanding its value-added food ingredients portfolio and strengthening capabilities across bakery, pastry, confectionery, gelato, foodservice, and industrial food applications.
- November 2025: Nexture announced the acquisition of Frulact, a specialty fruit and vegetable ingredients manufacturer, broadening its portfolio and strengthening its capabilities in value-added ingredients for bakery, dairy, beverages, and other food applications.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 3.4 Bn |
| Forecast Value (2035) |
USD 5.3 Bn |
| CAGR (2026–2035) |
5.0% |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Ingredient Type, By Source, By Application, By End User |
| Country Coverage |
Italy |
Frequently Asked Questions
How big is the Italy Pasta & Bakery Ingredients Market?
▾ The Italy Pasta & Bakery Ingredients Market is projected to be valued at USD 3.4 Billion in 2026 and is projected to reach USD 5.3 Billion by 2035, reflecting Italy's global leadership in pasta production and sustained domestic and export demand for authentic Italian bakery products.
What is the CAGR of the Italy Pasta & Bakery Ingredients Market from 2026 to 2035?
▾ The market is projected to expand at a compound annual growth rate (CAGR) of 5.0% between 2026 and 2035, supported by Italy's pasta export leadership, sustained international demand for authentic products, and growing gluten-free and alternative grain innovation.
What factors are driving the growth of the Italy Pasta & Bakery Ingredients Market?
▾ Growth is driven by Italy's global leadership in pasta production and export, sustained international demand for authentic Italian bakery and pasta products supported by quality certification systems, growing gluten-free and alternative grain product innovation, and continued specialty ingredient investment supporting premiumization.
What are the major trends in the Italy Pasta & Bakery Ingredients Market?
▾ Major trends include growing investment in traceability and quality certification systems, continued consolidation among Italian milling and ingredient companies, and rising innovation in gluten-free and alternative grain ingredient technology.
Who are the key players in the Italy Pasta & Bakery Ingredients Market?
▾ Key market participants include Barilla Group, Molino Casillo, Casillo Group, Molini Pivetti, and Agugiaro & Figna Molini, among other major Italian milling and ingredient companies.
How is the Italy Pasta & Bakery Ingredients Market segmented?
▾ The market is segmented by ingredient type, source, application, and end user, with demand analysis concentrated across Emilia-Romagna, Puglia, Campania, and Lombardy.