Market Snapshot
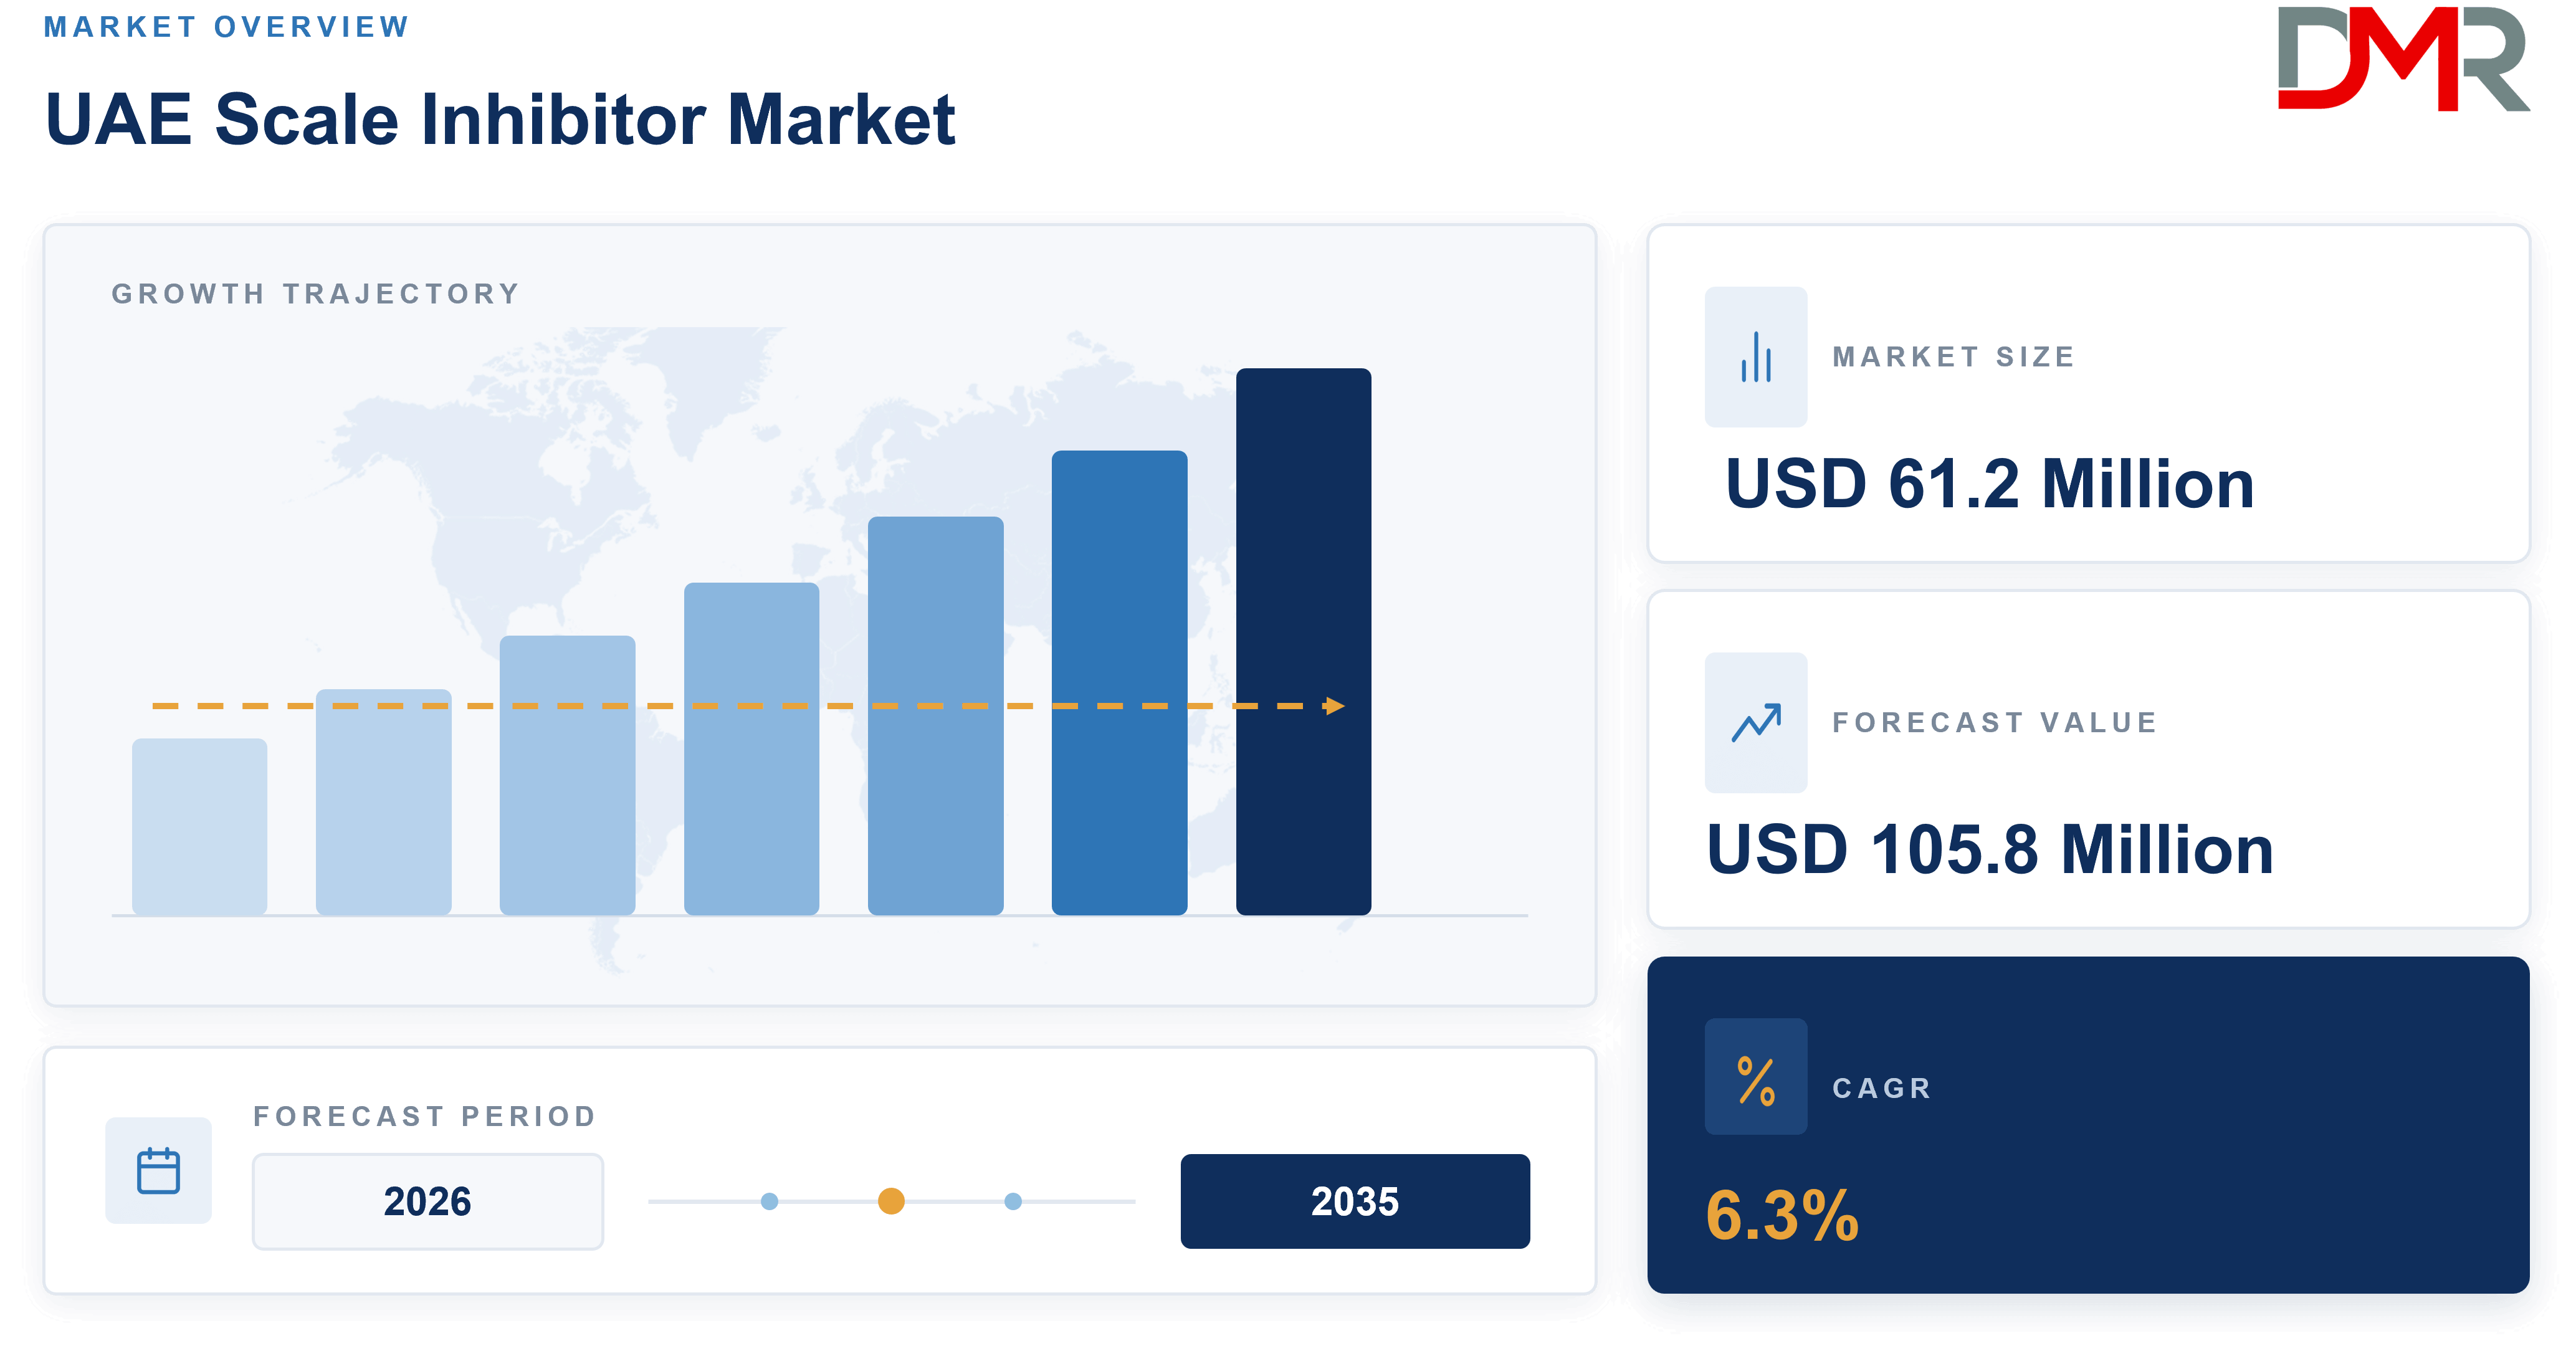
- Market Size (2026): USD 61.2 Mn
- Forecast Value (2035): USD 105.8 Mn
- CAGR (2026-2035): 6.3%
- Leading Product Type (2026): Organic scale inhibitors, approximately 68%
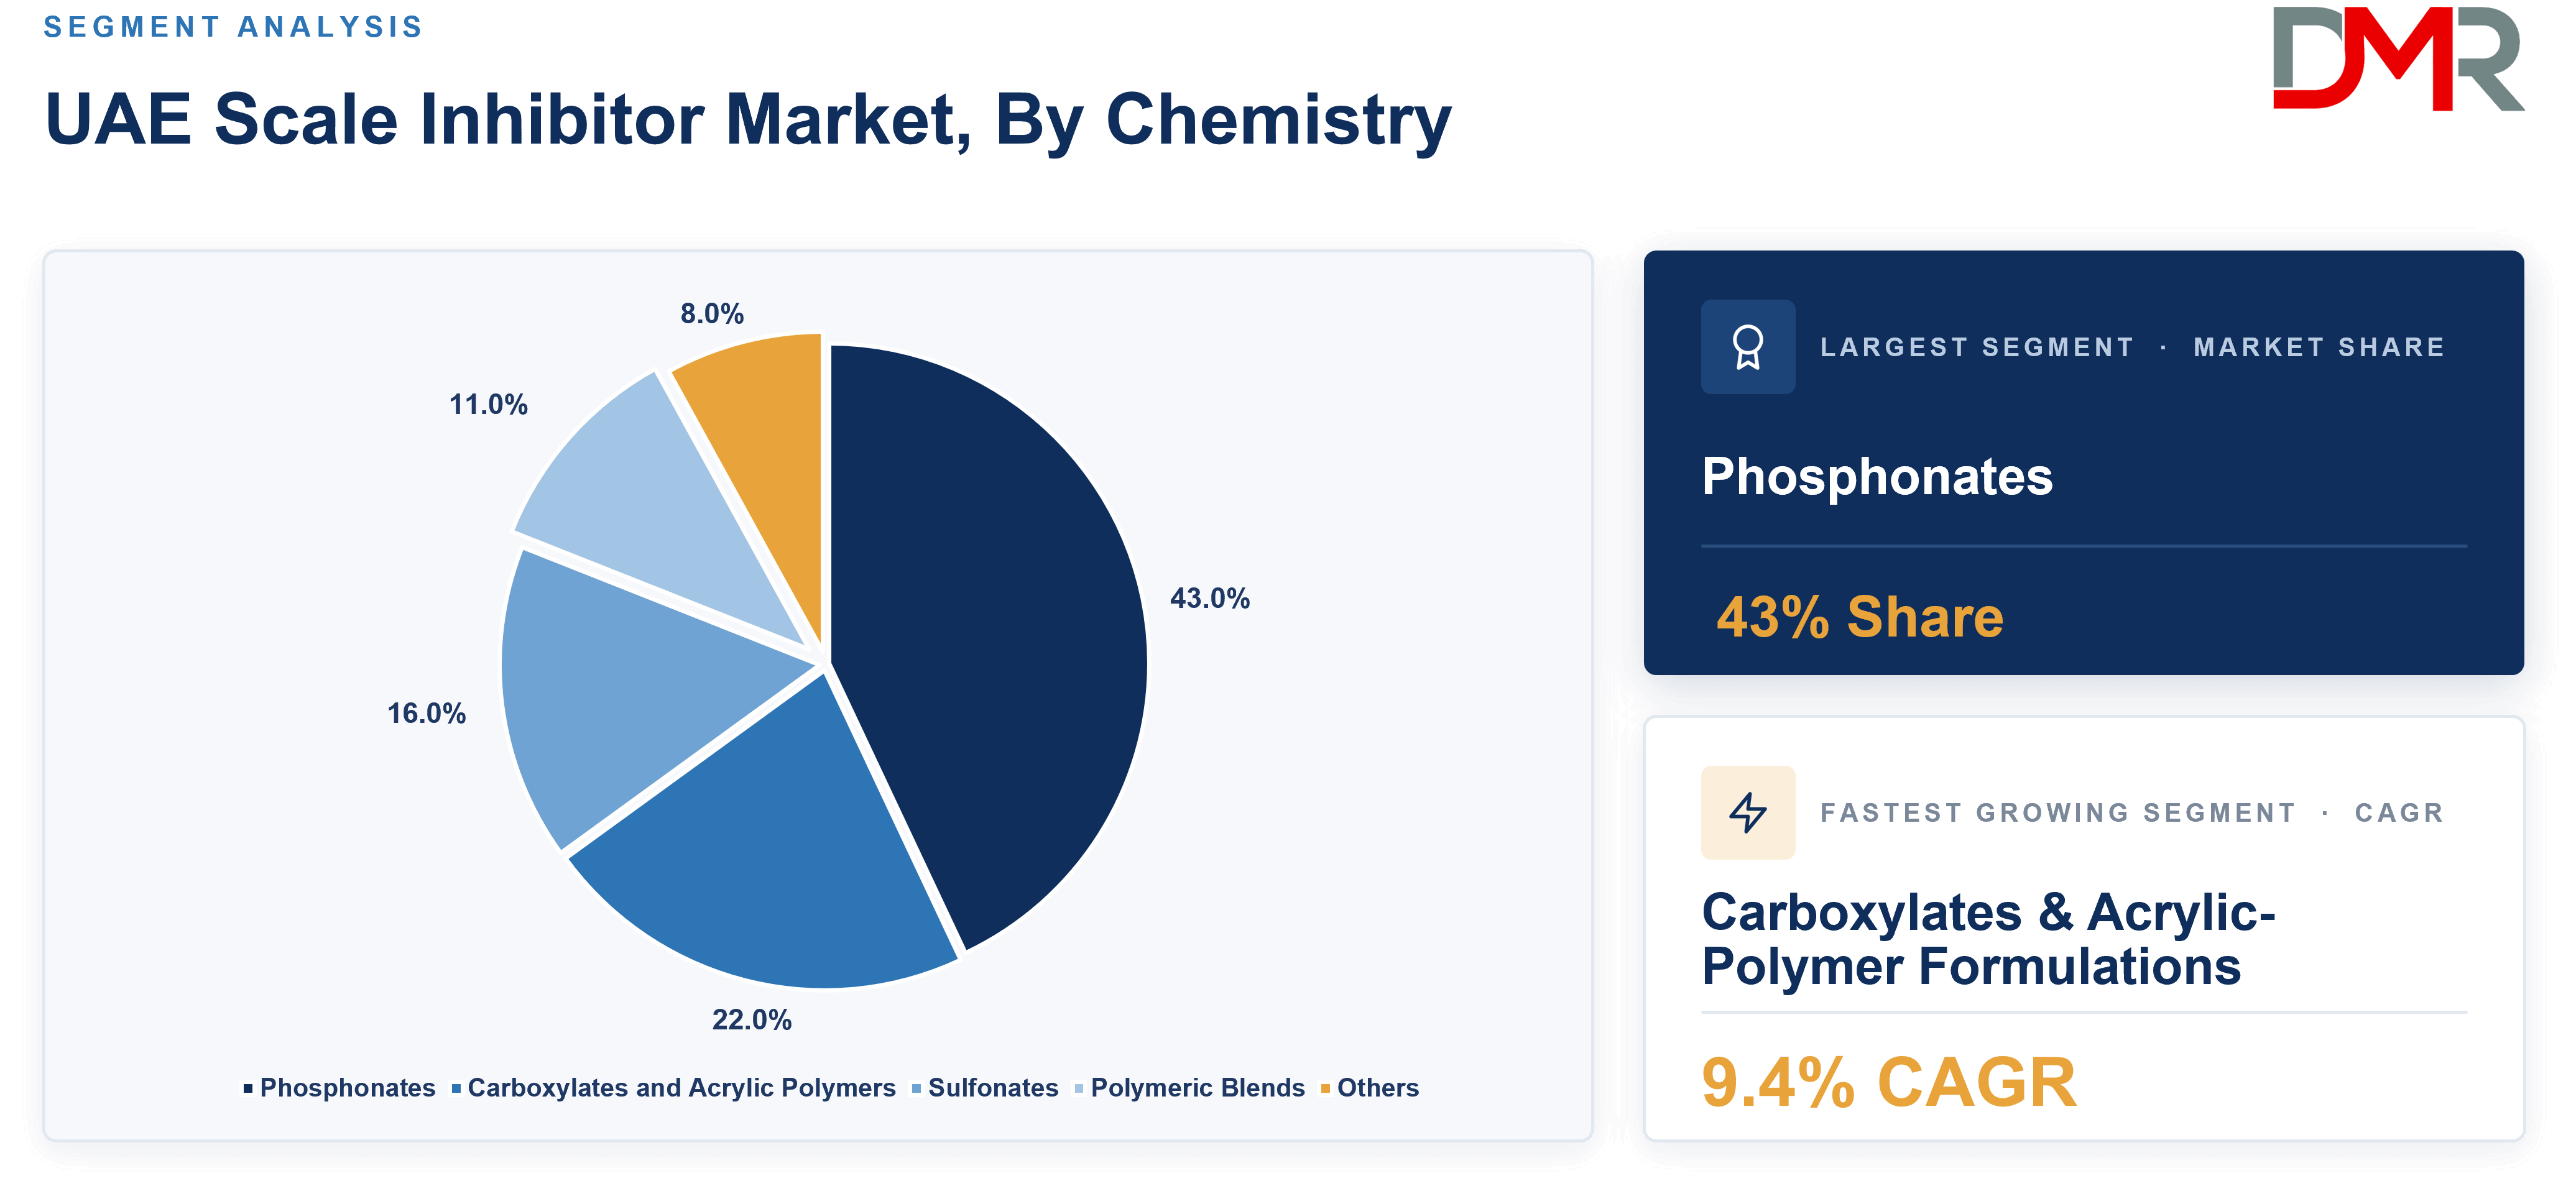
- Leading Chemistry (2026): Phosphonates, around 43%
- Key Players: SLB, Ecolab, Baker Hughes and others
What is UAE Scale Inhibitor Market and its Market Size?
The UAE Scale Inhibitor Market size is estimated to reach USD 61.2 Mn in 2026 and is further anticipated to reach USD 105.8 Mn by 2035, at a CAGR of 6.3%.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
The market covers specialty chemicals that limit precipitation, crystal growth and deposition of inorganic salts on equipment and process surfaces. Scale inhibitors are used where calcium carbonate, calcium sulfate, barium sulfate, silica and related deposits can reduce flow, heat transfer, membrane productivity, or reservoir and well performance. UAE demand spans hydrocarbon production, refining, desalination, power generation and industrial water systems.
Oil and gas applications remain structurally important because produced water, injection water and changing formation conditions can create scaling risks in wells, flowlines, separators and water-handling systems. In mature and water-intensive production environments, chemical treatment is often integrated with surveillance and production-chemistry programs. Treatment selection depends on water composition, temperature, pressure, mineral saturation, metallurgy and the operating profile of each asset.
Water treatment creates a second recurring demand pool. The UAE's reliance on desalination makes antiscalant performance important in membrane systems, particularly reverse osmosis, where mineral deposition can raise pressure requirements and reduce membrane productivity. Industrial cooling, boilers and process-water circuits also require scale control when dissolved minerals concentrate during water reuse or evaporation. Buyers therefore evaluate dosage efficiency, membrane compatibility, stability and total operating cost.
The commercial structure is changing as local industrial development expands. UAE initiatives aimed at domestic chemical production and import substitution create opportunities for local formulation, blending and technical distribution. ADNOC has identified corrosion, scale and asphaltene control chemicals as process-treatment opportunities for UAE production, while the TA'ZIZ chemicals ecosystem is expanding domestic chemical capacity. This supports a market in which local inventory and application support can become as important as the active chemistry itself.
Use Cases
- Oilfield Production: Upstream operators inject scale inhibitors into production and injection systems where incompatible waters and changing pressure conditions can precipitate mineral deposits. Treatment protects wellbore flow paths and surface equipment, helping maintain production capacity and reduce cleaning or intervention requirements.
- Reverse Osmosis Desalination: Water utilities dose antiscalants upstream of reverse osmosis membranes to control precipitation from concentrated feedwater. The objective is to maintain membrane throughput and operating stability while controlling cleaning frequency, chemical consumption and useful membrane life.
- Power Generation: Power producers apply scale-control programs in cooling-water, boiler and auxiliary systems where concentration cycles increase mineral deposition risk. Treatment supports heat-transfer efficiency and reduces deposits that can increase maintenance requirements or affect equipment performance.
- Industrial Process Water: Chemical, food, manufacturing and other industrial plants use scale inhibitors in recirculating water and process circuits. Operators select formulations according to water chemistry and equipment metallurgy, reducing deposits that can restrict flow or impair heat-transfer surfaces.
Key Takeaways
- Market Size & Share: UAE demand is estimated at USD 61.2 Mn in 2026, with organic formulations projected to hold approximately 68% of product demand.
- Chemistry Analysis: Phosphonate-based products are expected to represent around 43% of 2026 chemistry demand because of established performance across oilfield and water-treatment applications.
- Demand Concentration: Oil and gas is projected to account for nearly 39% of 2026 application demand, supported by production, injection-water and process-system requirements.
- Water Infrastructure: Water treatment and desalination represent a major recurring demand pool as reverse osmosis capacity and industrial water reuse expand.
- Growth Segment: High-purity and specialty low-phosphorus formulations are positioned for faster expansion as membrane compatibility and environmental considerations influence product selection.
- Supply Strategy: Local blending, inventory and technical service can improve responsiveness for customers requiring rapid formulation adjustment and dependable chemical availability.
How AI/Gen AI is Transforming the UAE Scale Inhibitor Market?
AI is affecting scale-control programs through interpretation of water chemistry, production and asset data. Machine learning can identify relationships between mineral saturation, temperature, pressure, flow and treatment dosage that are difficult to detect through fixed dosing rules. For oilfield applications, models can help rank wells by scaling risk and support chemical treatment adjustments as produced-water conditions change. In desalination, analytics can compare feedwater chemistry with membrane performance indicators to identify conditions associated with increasing deposition risk.
Generative AI is more relevant to engineering workflow than to chemical formulation itself. It can summarize laboratory reports, water analyses, chemical-treatment histories and maintenance records, helping engineers compare treatment performance across assets. Digital twins can model changes in process conditions before operators alter chemical dosing. These tools remain decision-support systems, with laboratory compatibility testing and field validation still required before significant treatment changes are implemented.
- Predictive Scale Risk: Machine learning can combine water chemistry and operating data to flag assets with increasing precipitation risk.
- Digital Twins: Digital models can test treatment and process scenarios before changes are introduced into operating systems.
- LLM Engineering Review: Generative AI can organize water analyses, laboratory results and chemical-treatment records for faster technical assessment.
- Dosing Optimization: Optimization models can support dosage adjustments when mineral concentration, flow or operating conditions change.
Key Drivers in the UAE Scale Inhibitor Market
Two demand forces shape the UAE market most strongly: intensive desalination and water treatment activity, and the scale-management needs of hydrocarbon production and processing.
- Desalination Capacity and Water Reuse: Reverse osmosis and other desalination systems concentrate dissolved minerals as water passes through treatment stages, creating a persistent need for antiscalants that control precipitation before it affects membrane performance. The UAE's water-security model therefore generates recurring chemical demand rather than a one-time equipment requirement. Industrial reuse adds another layer because repeated circulation increases dissolved-constituent concentration. Suppliers demonstrating membrane compatibility, stable performance and efficient dosage have a stronger position. More treated water and tighter operating targets create more opportunities for measured scale-control programs.
- Oilfield Water Handling and Production Chemistry: Scale formation can restrict flow and impair production when formation water and injected water mix or when pressure and temperature changes alter mineral solubility. Scale inhibitors are integrated into production-chemistry programs for wells, injection systems and surface equipment. UAE operators also have large downstream and water-handling assets where deposit control affects equipment reliability. Demand is supported by recurring treatment because water chemistry changes with field conditions and production strategy. Suppliers with field testing, squeeze-treatment capability, monitoring and chemistry customization can capture higher-value contracts than vendors competing only on standard chemical supply.
Restraints in the UAE Scale Inhibitor Market
Scale inhibitor demand is recurring, but product selection is technically sensitive. A treatment that works in one water system may not perform adequately when mineral composition, temperature or operating conditions change.
- Complex Water Chemistry: Scale formation can involve multiple minerals and changing saturation conditions, making product selection more complicated than choosing a universal chemical. Calcium carbonate, calcium sulfate, barium sulfate and silica require different control strategies, while oilfield conditions can shift as water cut and injection profiles change. Suppliers often support laboratory screening, compatibility checks and field trials before approval. This increases qualification time and favours vendors with application laboratories and experienced technical teams. It also limits rapid substitution when an incumbent formulation has a strong field history.
- Environmental and Treatment Efficiency Requirements: Water-treatment buyers increasingly balance scale-control performance with chemical consumption, discharge considerations and compatibility with downstream processes. High dosage can raise operating cost, while under-treatment can cause deposits and equipment problems. In desalination, a formulation must also perform without creating unacceptable membrane interactions. These constraints encourage higher-performance products but increase development and qualification requirements. Suppliers that cannot document dosage efficiency, stability and compatibility can face longer procurement cycles even when their products appear competitive on purchase price.
Growth Opportunities in the UAE Scale Inhibitor Market
Commercial white space is strongest where scale inhibition is bundled with monitoring, formulation engineering and local supply rather than sold as a standalone chemical.
- High-Purity Antiscalants for Desalination: Expansion of reverse osmosis capacity creates an opportunity for suppliers offering high-performance formulations designed for specific UAE feedwater conditions. Products that maintain membrane productivity at low dosage and support longer cleaning intervals can differentiate from generic antiscalants. Local technical teams can strengthen the proposition by linking chemical selection to feedwater analysis and membrane operating data.
- Oilfield Specialty Treatment Programs: High-temperature, high-pressure and mixed-water environments require formulations capable of controlling difficult deposits without disrupting production chemistry. Suppliers can expand value by combining scale-inhibitor supply with squeeze-treatment design, laboratory compatibility testing and field monitoring. This model increases switching costs while giving operators a measurable basis for treatment optimization.
Trends in the UAE Scale Inhibitor Market
Product development is moving toward greater formulation specificity, lower chemical consumption and closer integration between treatment chemistry and operating data.
- Low-Phosphorus Formulations: Water operators are evaluating products that reduce phosphorus loading while retaining scale-control performance. This supports demand for polymeric, blended and specialty chemistries that can meet application requirements with lower environmental burden.
- Condition-Based Dosing: Operators are increasingly using water-quality measurements, process data and monitoring results to adjust treatment rather than relying only on fixed dosing. This can reduce chemical waste while protecting assets during changing operating conditions.
- High-Purity Desalination Chemistry: Reverse osmosis systems require antiscalants compatible with membrane materials and concentrated feedwater. Suppliers are emphasizing product stability, low dosage and predictable performance under high recovery conditions.
- Local Chemical Supply: UAE industrial diversification is increasing interest in domestic blending, storage and distribution. Local supply can reduce lead times and support faster product trials, especially for large energy and water customers.
Research Scope and Analysis
Segment performance is assessed across five axes: product type, chemistry, application, end use industry and distribution channel. Each axis identifies the sub-segment carrying the largest share of 2026 revenue and the one expanding fastest through 2035, with the commercial reason behind each position.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Product Type
Organic scale inhibitors are projected to hold approximately 68% of 2026 product demand because phosphonate, polymer and blended organic chemistries offer broad performance across desalination, industrial water and oilfield applications. Their flexibility supports formulation adjustment when mineral composition or operating conditions change. Growth, however, is concentrated in specialty high-purity formulations, expanding at a CAGR of 9.7% from 2026 to 2035 as desalination operators seek efficient products compatible with membrane systems and lower treatment consumption. The shift favours suppliers that can document performance under local feedwater conditions and support dosage optimization through technical service.
By Chemistry
Phosphonates are expected to remain the leading chemistry in 2026, accounting for around 43% of demand because of their established use in threshold inhibition and crystal-growth control across industrial and oilfield systems. They remain attractive where proven field performance matters. The steeper trajectory sits with carboxylates and acrylic-polymer formulations, projected to expand at a CAGR of 9.4% through 2035 as buyers seek specialty performance across membrane water treatment and applications with tighter phosphorus considerations. Polymer-based products can also be formulated for specific mineral combinations, increasing their relevance in customized treatment programs.
By Application
Oil and gas is projected to account for nearly 39% of 2026 application demand, supported by scale risks in production wells, injection systems, flowlines and process equipment. The need is recurring because water chemistry changes as production and injection conditions evolve. Growth, however, is concentrated in water treatment and desalination, advancing at a CAGR of 8.8% through 2035 as reverse osmosis capacity, water reuse and industrial treatment requirements expand. The application also favours specialty formulations because membrane compatibility, recovery rate and feedwater chemistry directly influence product selection and dosage.
By End Use Industry
Oil and gas is expected to represent approximately 42% of 2026 end-use demand, reflecting the UAE's large hydrocarbon production, processing and water-handling infrastructure. Scale management is embedded in production-chemistry and asset-integrity programs, supporting recurring purchases. Power generation is set to record the faster trajectory, with a CAGR of 8.6% through 2035 as cooling, boiler and desalination-linked utility systems require tighter control of mineral deposition. Suppliers that combine scale control with water chemistry monitoring and technical support are positioned to capture a larger share of this expanding demand.
By Distribution Channel
Direct sales and technical contracts are projected to hold around 61% of 2026 distribution demand because large energy, utility and industrial customers require product qualification, application engineering and dependable supply. Direct contracts facilitate field trials and dosage optimization. Specialty chemical distributors are expanding faster, however, at a CAGR of 9.1% from 2026 to 2035 as smaller industrial buyers seek local inventory and access to multiple treatment chemistries. Distributors with formulation support, application knowledge and regional stock can gain share where buyers value rapid delivery and technical responsiveness.
The UAE Scale Inhibitor Market Report is Segmented Based on the Following
By Product Type
- Organic Scale Inhibitors
- Inorganic Scale Inhibitors
- Hybrid Scale Inhibitors
- Specialty High-Purity Scale Inhibitors
- Others
By Chemistry
- Phosphonates
- Carboxylates and Acrylic Polymers
- Sulfonates
- Polymeric Blends
- Others
By Application
- Oil and Gas
- Water Treatment and Desalination
- Power Generation
- Industrial Process Water
- Chemical and Petrochemical Processing
- Others
By End Use Industry
- Oil and Gas
- Water and Wastewater
- Power Generation
- Chemical and Petrochemical
- Manufacturing
- Food and Beverage
- Others
By Distribution Channel
- Direct Sales and Technical Contracts
- Specialty Chemical Distributors
- Industrial Trading Companies
- Online and Catalogue Channels
- Others
Pricing Analysis
Pricing in the UAE scale inhibitor market depends on active chemistry, formulation purity, dosage efficiency, application severity, packaging, technical support and delivered inventory rather than a single commodity benchmark. Standard water-treatment formulations face stronger price competition, while oilfield and membrane-grade products can command greater value when they solve difficult scaling conditions or reduce treatment consumption. The commercial opening is in specialty products supported by application engineering and performance monitoring. The main pricing brake is competition among imported products and distributors with broad chemical portfolios. Buyers are increasingly able to compare treatment cost per unit of water or production output rather than only chemical price per kilogram.
Export/Import Analysis
The UAE combines substantial domestic consumption with a strong position as a regional chemicals and logistics hub. Specialty scale-control products and chemical intermediates can enter through established import channels, while domestic blending and formulation can reduce lead times and tailor products to local water and oilfield conditions. UAE industrial diversification is strengthening the case for local chemical supply and import substitution. The commercial opportunity is strongest for suppliers that combine imported active ingredients with UAE-based formulation, inventory and technical service. Exposure to international freight, raw-material prices and qualification requirements remains a constraint, particularly for products used in critical desalination and oilfield systems.
Competitive Landscape
The competitive landscape combines global oilfield chemical suppliers, water-treatment companies, specialty chemical producers and UAE distributors. Large providers compete through formulation breadth, laboratory testing, field service, monitoring and established relationships with energy and utility customers. Regional distributors compete on inventory, responsiveness and access to multiple international brands. Competition is increasingly based on treatment performance and technical support rather than chemical availability alone. Local formulation and application engineering can strengthen supplier positions as UAE industrial procurement places greater emphasis on domestic value creation and resilient supply chains.
Some of the Prominent Players in the UAE Scale Inhibitor Market Are
-
SLB
- Baker Hughes
- Halliburton
- ChampionX
- Ecolab
- Nalco Water
- Solenis
- Veolia Water Technologies
- SUEZ
- Kurita Water Industries
- BASF
- Clariant
- Nouryon
- LANXESS
- Dow
- Evonik Industries
- Arxada
- Italmatch Chemicals
- Buckman
- Cortec Corporation
- Innospec
- Dorf Ketal
- Lubrizol
- Afton Chemical
- King Industries
- Univar Solutions
- Brenntag
- IMCD
- Kemira
- Thermax
- Hydranautics
- Avista Technologies
- Genesys International
- Water Treatment Products
- BWA Water Additives
- REDA Industrial Materials FZE UAE
- BASF FZE
- Culligan Middle East FZE
- Fluidz UAE LLC
- Eflochem Chemicals Blending Co
- Other Key Players
Recent Developments
- In May 2026, TA'ZIZ and Alpha Dhabi announced a strategic collaboration supporting up to 14 industrial chemicals and approximately 2.2 million tonnes per year of additional capacity. The initiative strengthens the domestic chemicals ecosystem and expands the potential customer and supplier base for specialty process-treatment chemicals.
- In January 2026, ADNOC and TAQA announced a 27-year utilities agreement supporting the TA'ZIZ Industrial Chemicals Zone in Ruwais. The project includes electricity, steam, process cooling, water and wastewater infrastructure, strengthening the industrial base that will consume and support specialty process chemicals.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 61.2 Mn |
| Forecast Value (2035) |
USD 105.8 Mn |
| CAGR (2026-2035) |
6.3% |
| Historical Data |
2021 - 2025 |
| Forecast Data |
2026 - 2035 |
| Base Year |
2025 |
| Segments Covered |
By Product Type, By Chemistry, By Application, By End Use Industry, By Distribution Channel |
| Regional Coverage |
The UAE |
Frequently Asked Questions
How big is the UAE Scale Inhibitor Market?
▾ The UAE Scale Inhibitor Market is estimated at USD 61.2 Mn in 2026. Demand is supported by oil and gas production, desalination, industrial water treatment, power generation and process systems where mineral deposition can reduce flow, membrane performance or heat-transfer efficiency.
What is the growth rate of the UAE Scale Inhibitor Market?
▾ The market is projected to expand at a CAGR of 6.3% from 2026 to 2035, reaching USD 105.8 Mn by 2035. Growth is supported by desalination, water reuse, hydrocarbon production chemistry and expanding industrial activity in the UAE.
What is driving demand in the UAE Scale Inhibitor Market?
▾ Desalination and hydrocarbon production are the strongest structural demand drivers. Reverse osmosis systems require antiscalants to manage mineral precipitation, while oilfield production and injection systems need scale control as formation and injected waters interact under changing pressure and temperature conditions.
Who are the key players in the UAE Scale Inhibitor Market?
▾ Key participants include SLB, Baker Hughes, Halliburton, ChampionX, Ecolab, Nalco Water, Solenis and Kurita Water Industries. The market also includes specialty chemical producers and UAE distributors that provide local inventory, formulation support and application engineering.
Which product type leads the UAE Scale Inhibitor Market?
▾ Organic scale inhibitors are projected to lead product demand in 2026, accounting for approximately 68%. Their broad application range and formulation flexibility support use across oilfield production, desalination, industrial water and other process-treatment systems.