Market Snapshot
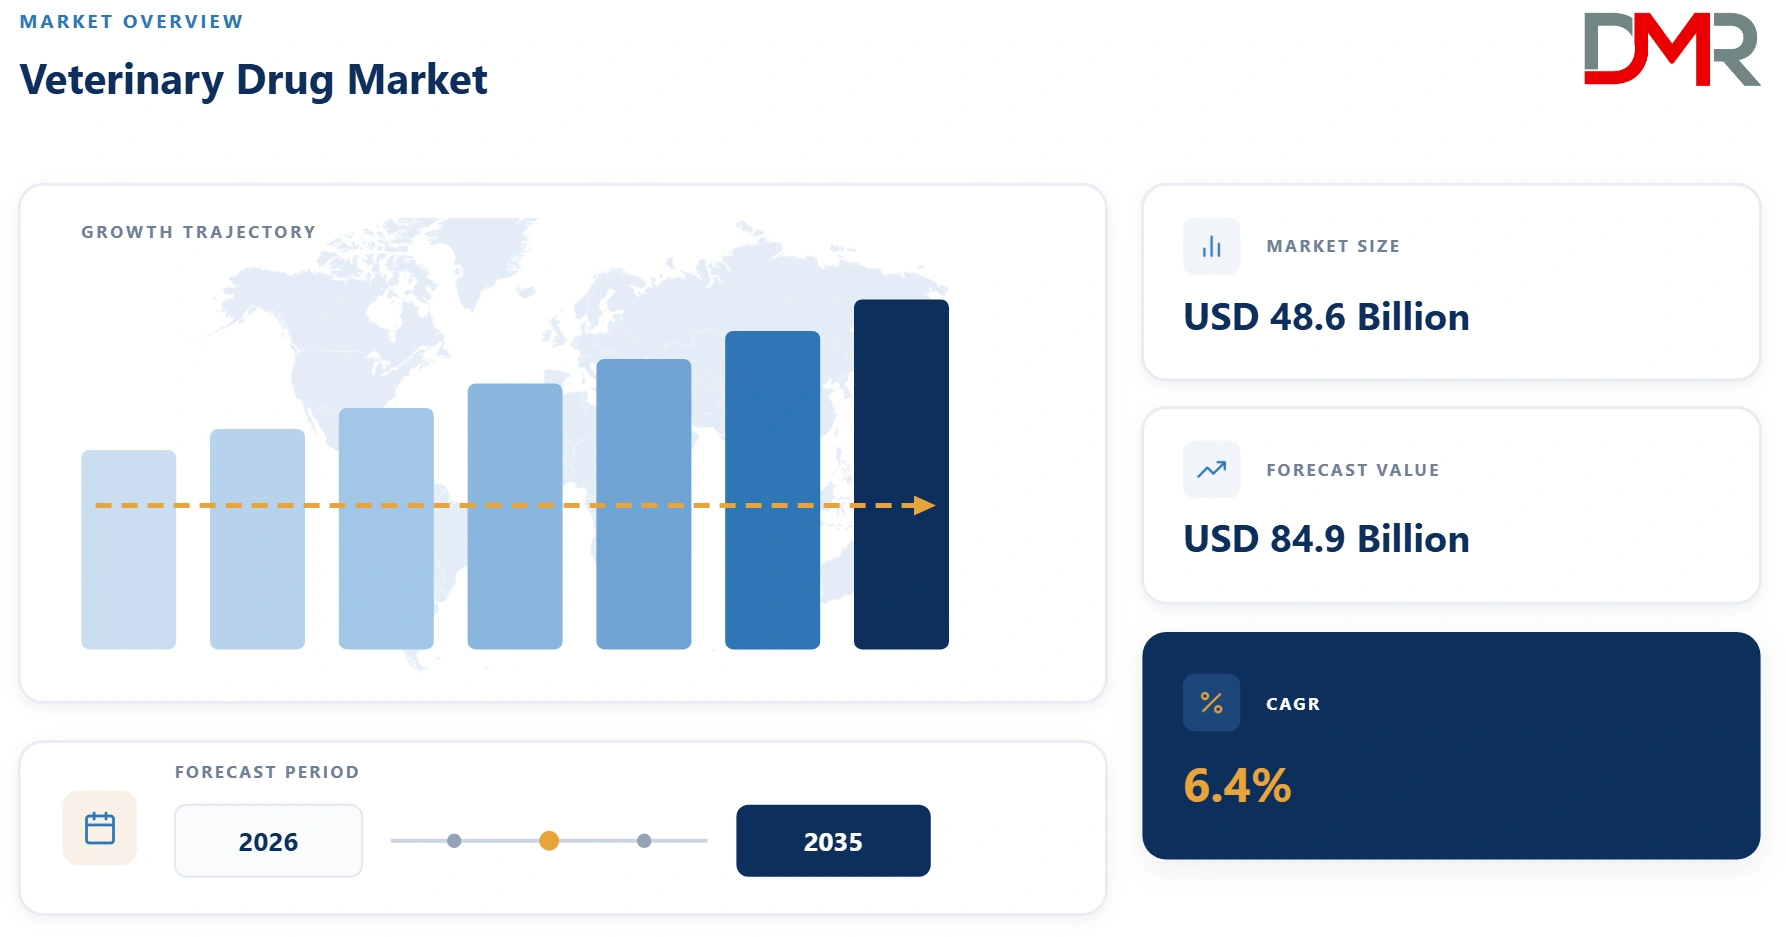
- Market Size (2026): USD 48.6 Bn
- Forecast Value (2035): USD 84.9 Bn
- CAGR (2026-2035): 6.4%
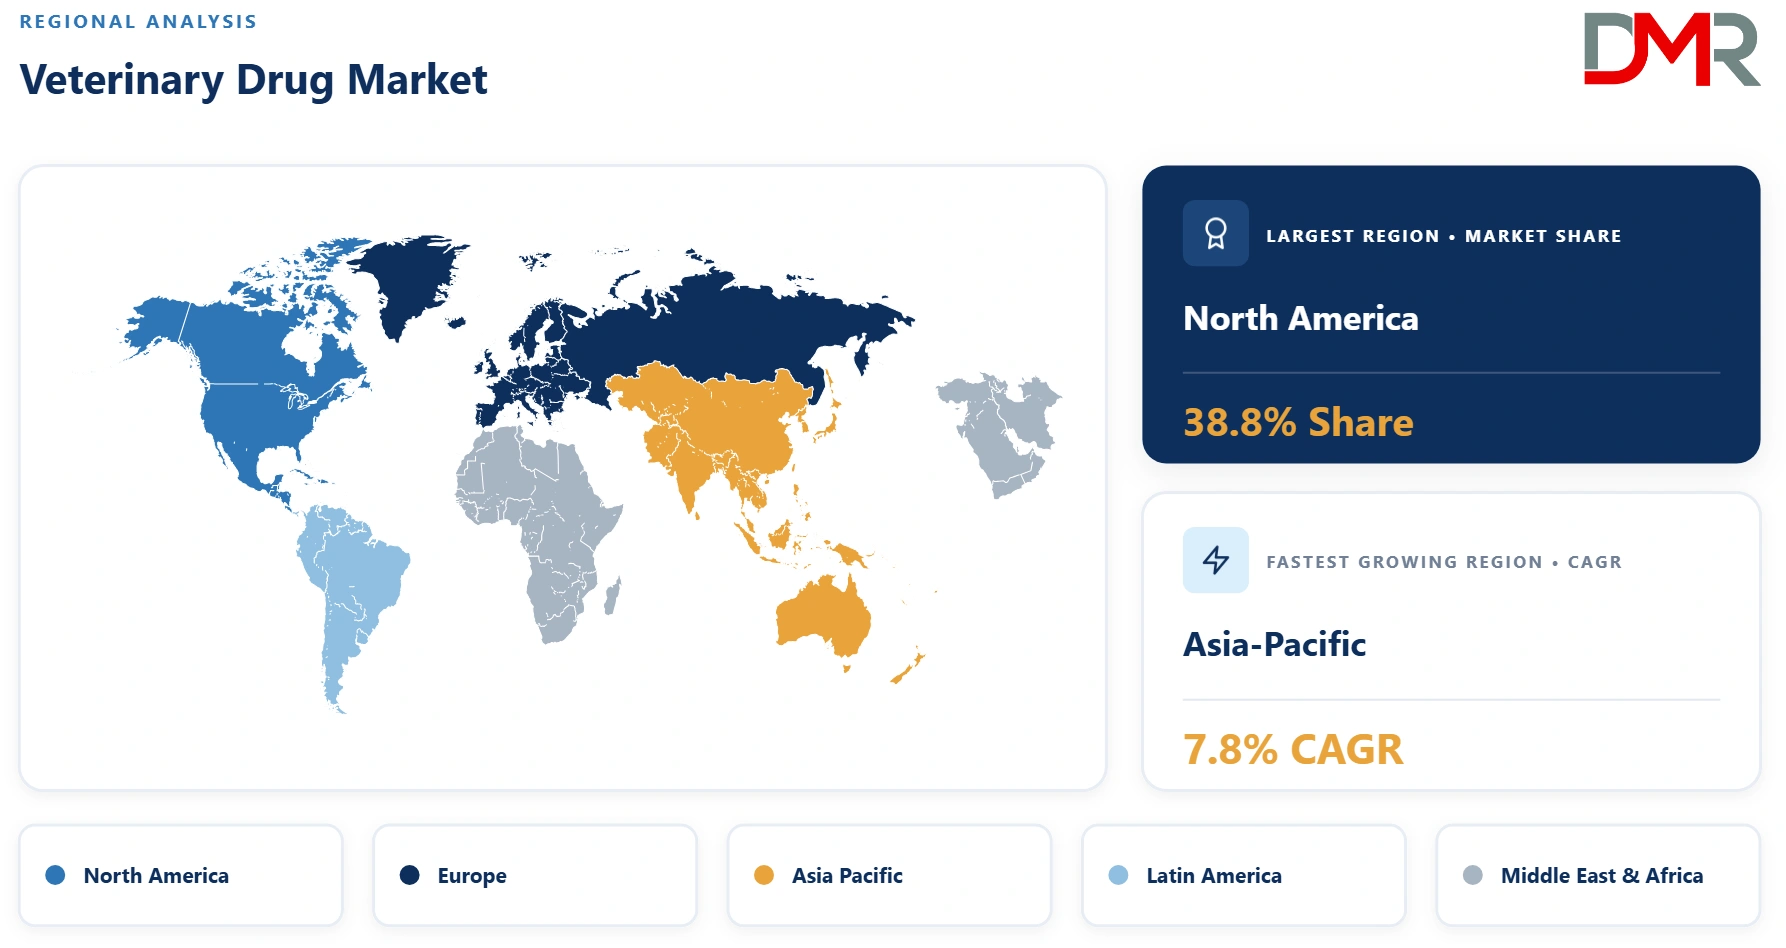
- Largest Region (2026): North America, approximately 38.8%
- Fastest-Growing Region: Asia-Pacific
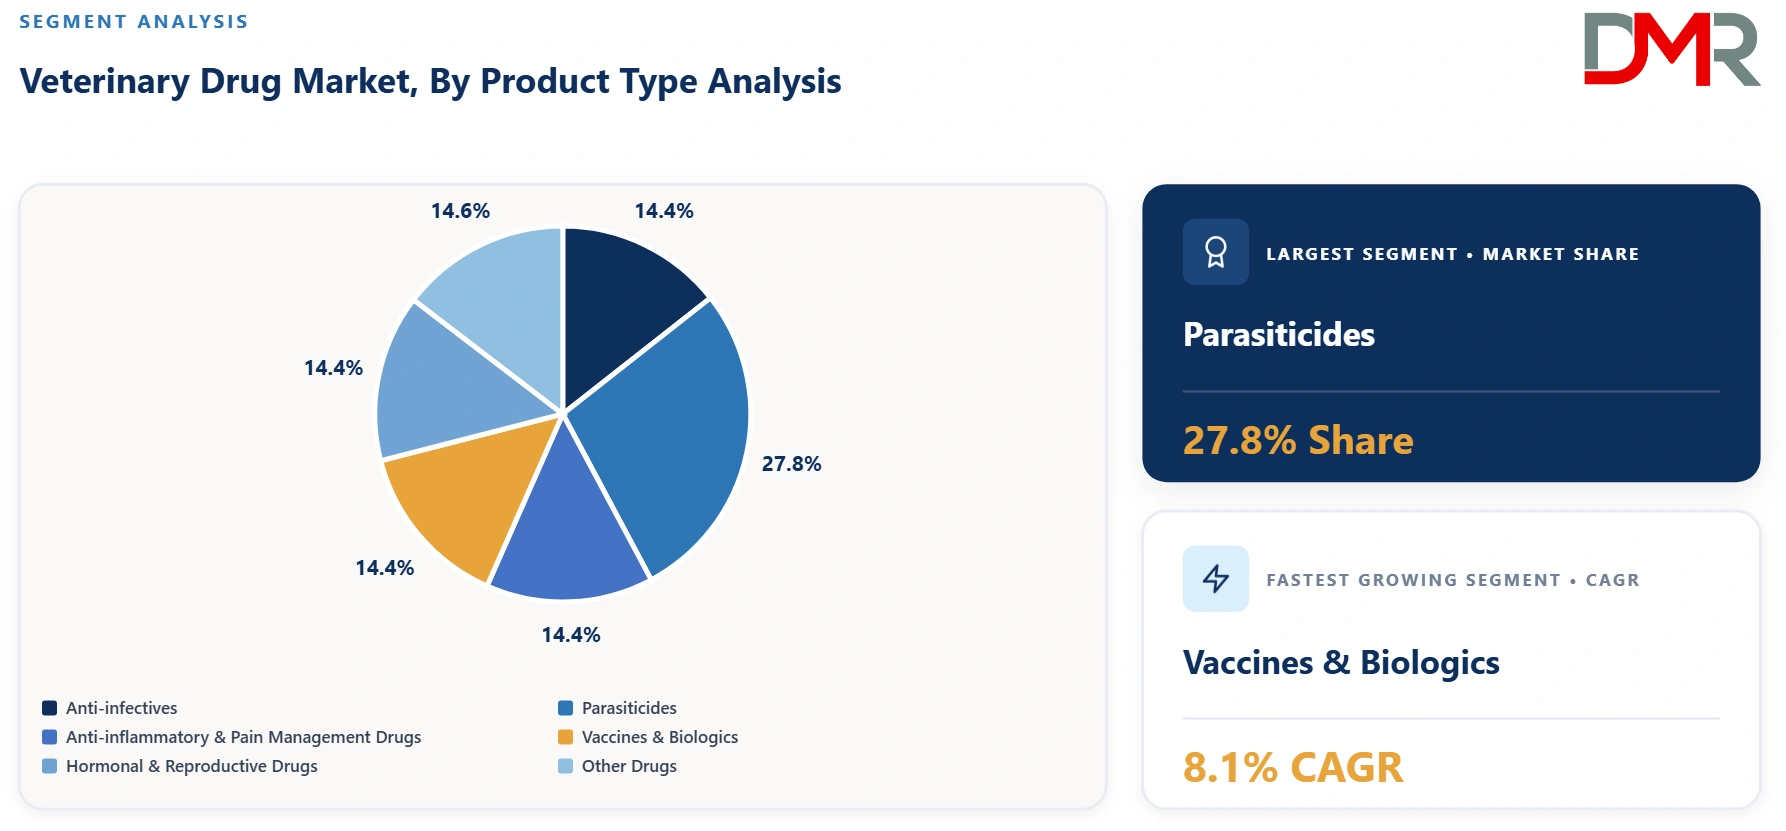
- Leading Product Type (2026): Parasiticides, around 27.8%
- Leading Animal Type (2026): Companion Animals, close to 58.6%
- Key Players: Zoetis, Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco, and Others
What is Veterinary Drug Market and its Market Size?
Global Veterinary Drug Market size is estimated to reach USD 48.6 Bn in 2026 and is further anticipated to reach USD 84.9 Bn by 2035, at a CAGR of 6.4%.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Veterinary drugs are pharmaceutical and biological products used to prevent, diagnose, control, or treat diseases and health conditions in companion animals, livestock, equine populations, and other animals. The market includes anti-infectives, parasiticides, anti-inflammatory and pain therapies, vaccines and biologics, hormonal and reproductive medicines, and other prescription or non-prescription veterinary products.
Demand is supported by rising pet healthcare expenditure, livestock disease prevention, food-security requirements, zoonotic disease surveillance, and the need to improve animal welfare and productivity. Companion-animal treatment increasingly includes long-term management of dermatology, osteoarthritis, cardiac disease, endocrine disorders, epilepsy, cancer, and other chronic conditions, while livestock medicine remains closely linked to herd health, vaccination, parasite control, reproductive management, and outbreak prevention.
Innovation is shifting toward longer-acting formulations, combination parasiticides, monoclonal antibodies, targeted immunotherapies, advanced vaccines, and species-specific therapies. These products can improve dosing convenience, treatment adherence, and clinical outcomes. At the same time, antimicrobial stewardship is reshaping the use of antibiotics in food-producing animals and encouraging preventive health, vaccination, diagnostics, and targeted prescribing.
Commercial performance depends on regulatory approvals, veterinary adoption, product safety, manufacturing reliability, distribution reach, and evidence of clinical or productivity benefits. Large animal-health companies benefit from broad portfolios and global channels, while regional manufacturers compete through local disease expertise, pricing, generics, and livestock-focused distribution.
Use Cases
- Companion Animal Chronic Disease Management: Veterinarians prescribe pain, dermatology, cardiac, endocrine, neurologic, and other medicines for long-term management of chronic diseases in dogs, cats, and other pets.
- Parasite Prevention and Treatment: Parasiticides protect animals from fleas, ticks, heartworm, intestinal worms, mites, and other parasites, supporting animal welfare and reducing vector-borne disease risks.
- Livestock Disease Prevention: Vaccines, anti-infectives, antiparasitic medicines, and reproductive products support herd and flock health, productivity, biosecurity, and continuity of food production.
- Emergency and Acute Treatment: Veterinary drugs are used in surgery, trauma, infection, anesthesia, pain control, inflammation, and other acute-care settings across clinics, hospitals, farms, and field services.
Key Takeaways
- Market Size & Share: Global revenue is estimated at USD 48.6 Bn in 2026, with North America contributing approximately 38.8%.
- Product Type Analysis: Parasiticides lead with around 27.8% share, while Vaccines & Biologics are projected to grow at 8.1% CAGR.
- Animal Type Analysis: Companion Animals account for approximately 58.6% of 2026 revenue and are projected to expand at 7.2% CAGR.
- Route Analysis: Parenteral products lead with approximately 37.9% share, while oral formulations are projected to expand at 7.1% CAGR.
- Regional Analysis: Asia-Pacific is projected to record the fastest regional expansion at approximately 7.8% CAGR through 2035.
- Distribution Analysis: Online Pharmacies are projected to expand at approximately 9.6% CAGR as digital prescription fulfillment increases.
How AI/Gen AI is Transforming the Veterinary Drug Market?
AI is increasingly applied across veterinary drug discovery, clinical development, pharmacovigilance, manufacturing, and commercial forecasting. Machine-learning models can help identify therapeutic targets, predict compound properties, prioritize vaccine antigens, analyze pathology and laboratory data, and improve selection of animals for clinical studies. These tools can shorten early discovery cycles and support more targeted development programs.
Generative AI can assist with literature synthesis, protocol drafting, safety case processing, regulatory documentation, medical information, and veterinarian education. In supply chains, predictive models can integrate seasonality, disease outbreaks, prescribing patterns, and regional demand to improve inventory planning. Adoption remains dependent on validated datasets, expert review, data governance, and compliance with veterinary regulatory requirements.
- Drug Discovery: AI can prioritize compounds, biologic targets, and repurposing candidates for animal-specific indications.
- Pharmacovigilance: Automated classification can help organize adverse-event reports and identify emerging safety signals for expert review.
- Clinical Development: Predictive analytics can support study design, site selection, enrollment, endpoint assessment, and dose optimization.
- Demand Forecasting: AI can improve production and inventory planning by combining prescription trends, seasonality, outbreaks, and channel data.
Key Drivers in the Global Veterinary Drug Market
Rising Companion Animal Healthcare Expenditure
Increasing pet ownership, humanization of companion animals, and longer pet lifespans are raising demand for preventive and therapeutic medicines. Owners are more willing to treat chronic conditions such as osteoarthritis, allergies, cardiac disease, epilepsy, diabetes, and cancer, supporting recurring pharmaceutical use. Advanced diagnostics are also identifying disease earlier, expanding the treated population. This trend benefits parasiticides, dermatology drugs, pain therapies, cardiac medicines, biologics, vaccines, and other high-value categories across developed and urbanizing markets.
Growing Focus on Livestock Health and Disease Prevention
Livestock producers rely on veterinary medicines to reduce disease losses, protect productivity, maintain reproductive performance, and comply with animal-health and food-safety requirements. Disease outbreaks can create substantial economic losses, increasing investment in vaccination, parasite control, biosecurity, and targeted treatment. The need to manage zoonotic risks and transboundary animal diseases further supports veterinary pharmaceutical demand. Preventive health programs are becoming more important as antimicrobial stewardship policies encourage reduced dependence on routine antibiotic use.
Restraints in the Global Veterinary Drug Market
Stringent Regulatory Requirements and Long Approval Timelines
Veterinary medicines require evidence of safety, efficacy, quality, manufacturing consistency, and appropriate labeling before commercialization. Food-producing animal products may also require residue, withdrawal-period, and environmental assessments. These requirements increase development costs and extend timelines, particularly for new molecular entities and biologics. Global manufacturers must manage different approval systems across jurisdictions, while smaller developers may face financing constraints during lengthy clinical and regulatory programs.
Antimicrobial Resistance and Restrictions on Antibiotic Use
Concern over antimicrobial resistance is changing prescribing and production practices, especially in livestock. Regulators and industry groups increasingly emphasize responsible use, veterinary oversight, diagnostics, vaccination, and disease prevention. Restrictions on routine or growth-promotion uses of medically important antimicrobials can reduce demand for some established drug categories. Manufacturers therefore need to develop alternatives and support stewardship programs while maintaining effective treatment options for clinically justified infections.
Growth Opportunities in the Global Veterinary Drug Market
Expansion of Biologics and Targeted Therapies
Monoclonal antibodies, targeted immunotherapies, advanced vaccines, and other biologics are opening new treatment opportunities in pain, dermatology, infectious disease, oncology, and chronic conditions. These products can offer differentiated mechanisms and longer dosing intervals, creating premium categories with strong veterinarian interest. Continued investment in species-specific targets, manufacturing platforms, and clinical validation can broaden biologic use beyond established companion-animal indications.
Emerging-Market Veterinary Infrastructure
Urban pet ownership and commercial livestock production are expanding across Asia-Pacific, Latin America, the Middle East, and parts of Africa. Improving veterinary infrastructure, organized distribution, diagnostic access, and preventive-care awareness creates opportunities for branded and generic medicines. Companies can expand through local partnerships, regional manufacturing, veterinary chains, digital channels, and disease-specific portfolios adapted to local epidemiology and affordability.
Trends in the Global Veterinary Drug Market
Long-Acting and Convenience-Focused Formulations
Manufacturers are developing once-yearly injectables, long-duration biologics, combination parasiticides, palatable chewables, and simplified topical products to improve adherence. Convenience is particularly important in chronic companion-animal therapy and parasite prevention, where missed doses can reduce effectiveness. Longer-acting products can also strengthen veterinarian involvement and create differentiated value propositions.
Greater Emphasis on Preventive Medicine and Vaccination
Animal-health strategies are shifting toward prevention through vaccination, parasite control, diagnostics, biosecurity, nutrition, and early intervention. In livestock, this supports productivity while reducing unnecessary antimicrobial exposure. In companion animals, preventive care increases recurring demand for vaccines and parasiticides. Advances in vaccine platforms and disease surveillance are expected to strengthen this trend.
Research Scope and Analysis
The market is analyzed by Product Type, Animal Type, Route of Administration, and Distribution Channel, with regional assessment across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Product Type
Parasiticides is estimated to lead the product type category with around 27.8% of revenue in 2026, supported by established veterinary use, broad product availability, and recurring treatment requirements. Growth, however, is concentrated in Vaccines & Biologics, projected to expand at a CAGR of 8.1% between 2026 and 2035. Expansion is supported by product innovation, improved disease diagnosis, preventive health programs, and greater access to veterinary services. Competitive positioning will depend on clinical differentiation, safety, dosing convenience, regulatory status, pricing, and reliable supply.
By Animal Type
Companion Animals is estimated to lead the animal type category with around 58.6% of revenue in 2026, supported by established veterinary use, broad product availability, and recurring treatment requirements. Growth, however, is concentrated in Companion Animals, projected to expand at a CAGR of 7.2% between 2026 and 2035. Expansion is supported by product innovation, improved disease diagnosis, preventive health programs, and greater access to veterinary services. Competitive positioning will depend on clinical differentiation, safety, dosing convenience, regulatory status, pricing, and reliable supply.
By Route of Administration
Parenteral is estimated to lead the route of administration category with around 37.9% of revenue in 2026, supported by established veterinary use, broad product availability, and recurring treatment requirements. Growth, however, is concentrated in Oral, projected to expand at a CAGR of 7.1% between 2026 and 2035. Expansion is supported by product innovation, improved disease diagnosis, preventive health programs, and greater access to veterinary services. Competitive positioning will depend on clinical differentiation, safety, dosing convenience, regulatory status, pricing, and reliable supply.
By Distribution Channel
Veterinary Hospitals & Clinics is estimated to lead the distribution channel category with around 54.7% of revenue in 2026, supported by established veterinary use, broad product availability, and recurring treatment requirements. Growth, however, is concentrated in Online Pharmacies, projected to expand at a CAGR of 9.6% between 2026 and 2035. Expansion is supported by product innovation, improved disease diagnosis, preventive health programs, and greater access to veterinary services. Competitive positioning will depend on clinical differentiation, safety, dosing convenience, regulatory status, pricing, and reliable supply.
The Global Veterinary Drug Market Report is Segmented Based on the Following
By Product Type
- Anti-infectives
- Parasiticides
- Anti-inflammatory & Pain Management Drugs
- Vaccines & Biologics
- Hormonal & Reproductive Drugs
- Other Drugs
By Animal Type
- Companion Animals
- Livestock Animals
- Equine
- Other Animals
By Route of Administration
- Oral
- Parenteral
- Topical
- Other Routes
By Distribution Channel
- Veterinary Hospitals & Clinics
- Retail Pharmacies & Drug Stores
- Online Pharmacies
- Other Channels
Regional Analysis
Veterinary drug demand reflects the distribution of companion-animal spending, livestock production, veterinary infrastructure, disease burden, regulatory standards, and access to preventive and therapeutic products.
Region with the Largest Revenue Share
North America is estimated to account for approximately 38.8% of global veterinary drug revenue in 2026. The region benefits from high companion-animal healthcare spending, extensive veterinary infrastructure, commercial livestock production, advanced diagnostics, and rapid adoption of new therapies. The United States represents the majority of regional demand and remains a major launch market for parasiticides, dermatology drugs, pain therapies, vaccines, and biologics. Strong veterinarian engagement and established animal-health distribution support continued revenue growth.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
Region with the Highest CAGR
Asia-Pacific is projected to record the highest regional CAGR at approximately 7.8% from 2026 to 2035. Growth is supported by rising pet ownership, increasing household incomes, livestock intensification, improving veterinary access, and stronger awareness of vaccination and disease prevention. China, India, Japan, South Korea, and Australia provide diverse opportunities across companion and production animals. Regional manufacturing, distributor partnerships, and digital channels are improving product availability.
By Region
- North America: The US, Canada
- Europe: Germany, France, The UK, Italy, Spain, Rest of Europe
- Asia-Pacific: China, Japan, India, Australia, South Korea, Rest of APAC
- Latin America: Mexico, Brazil, Colombia, Argentina, Rest of LATAM
- Middle East & Africa: Saudi Arabia, The UAE, South Africa, Rest of MEA
Regulatory Landscape
Veterinary drugs are regulated through national frameworks covering product quality, safety, efficacy, manufacturing, labeling, pharmacovigilance, prescribing, and distribution. Products for food-producing animals may also require residue studies, maximum residue limits, withdrawal periods, and environmental assessments. Antimicrobial stewardship has become a major policy focus, with tighter controls on medically important antibiotics in livestock. Novel biologics, vaccines, and conditionally approved therapies may follow specialized pathways. Manufacturers operating globally must coordinate registrations, safety surveillance, manufacturing changes, and lifecycle management across multiple authorities.
Technology Analysis
Technology development is expanding beyond conventional small molecules toward monoclonal antibodies, recombinant vaccines, novel adjuvants, long-acting injectables, combination parasiticides, and precision drug-delivery systems. Digital pharmacovigilance, AI-supported discovery, genomic surveillance, and advanced manufacturing analytics are also influencing product development. In livestock, diagnostics and herd-monitoring systems can support more targeted medicine use, while companion-animal innovation increasingly focuses on chronic disease and dosing convenience. Companies with integrated R&D, biologics manufacturing, regulatory expertise, and veterinary data capabilities are positioned to capture higher-value therapeutic opportunities.
Competitive Landscape
The veterinary drug market combines large multinational animal-health companies with regional manufacturers, generic suppliers, vaccine specialists, and therapeutic innovators. Competition centers on efficacy, safety, spectrum of protection, dosing convenience, veterinarian trust, regulatory coverage, price, and distribution. Leading companies use R&D, licensing, acquisitions, product lifecycle management, and geographic expansion to strengthen portfolios. Growth categories include biologics, dermatology, pain management, combination parasiticides, and advanced vaccines, while antimicrobial stewardship is reshaping established livestock portfolios.
Some of the Prominent Players in the Global Veterinary Drug Market Are:
- Zoetis Inc.
- Merck Animal Health
- Boehringer Ingelheim Animal Health
- Elanco Animal Health Incorporated
- Virbac S.A.
- Ceva Santé Animale
- Dechra Pharmaceuticals
- Vetoquinol S.A.
- Phibro Animal Health Corporation
- Norbrook Laboratories
- Bimeda
- HIPRA
- Bioveta a.s.
- Indian Immunologicals Limited
- Hester Biosciences Limited
- Kyoritsu Seiyaku Corporation
- Orion Animal Health
- Chanelle Pharma
- Animalcare Group plc
- Eco Animal Health Group plc
- Ourofino Saúde Animal
- Alivira Animal Health
- Zenex Animal Health
- Ashish Life Science
- Veko Care
- Tianjin Ringpu Bio-Technology Co., Ltd.
- Jurox Pty Ltd
- Laboratorios Calier
- Laboratorios Karizoo
- Vetanco
- Brouwer
- Agrovet Market Animal Health
- Teknofarma
- NITA-FARM
- Endovac Animal Health
- Agrolabo S.p.A.
- Vet-Agro Sp. z o.o.
- Provet Group
- Zydus Animal Health
- Intas Animal Health
- Other Key Players
Recent Developments
- In June 2026, the U.S. FDA issued an Emergency Use Authorization for generic nitenpyram tablets to treat New World screwworm infestations in dogs and cats.
- In February 2026, Merck Animal Health received U.S. FDA approval for NUMELVI (atinvicitinib tablets) for control of pruritus associated with allergic dermatitis in dogs.
- In December 2025, Elanco received USDA approval for Befrena (tirnovetmab), an anti-IL31 monoclonal antibody injection for canine allergic and atopic dermatitis.
- In December 2025, Elanco announced full USDA approval of Trutect, its canine parvovirus monoclonal antibody.
- In July 2025, Merck Animal Health received U.S. FDA approval for BRAVECTO QUANTUM, a once-yearly injectable flea and tick treatment for dogs.
- In May 2025, Merck Animal Health received U.S. FDA approval for MOMETAMAX SINGLE, a single-dose in-clinic treatment for otitis externa in dogs.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 48.6 Bn |
| Forecast Value (2035) |
USD 84.9 Bn |
| CAGR (2026–2035) |
6.4% |
| The US Market Size (2026) |
USD 15.1 Bn |
| Historical Data |
2021 – 2025 |
| Forecast Data |
2026 – 2035 |
| Base Year |
2025 |
| Segments Covered |
By Product Type, By Animal Type, By Route of Administration, By Distribution Channel |
| Regional Coverage |
North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
Frequently Asked Questions
How big is the Global Veterinary Drug Market?
▾ Global Veterinary Drug Market size is estimated to reach USD 48.6 Bn in 2026 and is projected to reach USD 84.9 Bn by 2035, growing at a CAGR of 6.4%.
What is the growth rate of the Global Veterinary Drug Market?
▾ The market is expected to expand at an estimated CAGR of 6.4% from 2026 to 2035, supported by companion-animal healthcare spending, livestock disease prevention, vaccination, and pharmaceutical innovation.
Which region holds the largest share in the Global Veterinary Drug Market?
▾ North America leads the market with approximately 38.8% of global revenue in 2026, supported by advanced veterinary infrastructure, high pet-health expenditure, and commercial livestock demand.
Who are the key players in the Global Veterinary Drug Market?
▾ Prominent companies include Zoetis, Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco Animal Health, Virbac, Ceva Santé Animale, Dechra Pharmaceuticals, and Vetoquinol.
Which segment is leading the Global Veterinary Drug Market?
▾ Parasiticides lead the product-type category with an estimated 27.8% share in 2026, supported by recurring parasite prevention and treatment demand across companion and production animals.
Which segment is expanding fastest in the Global Veterinary Drug Market?
▾ Vaccines & Biologics are projected to record the fastest product-type growth at approximately 8.1% CAGR through 2035 as preventive and targeted therapies expand.
What are the major growth drivers in the Global Veterinary Drug Market?
▾ Major drivers include rising pet healthcare spending, livestock disease prevention, greater vaccination adoption, growing chronic disease treatment, and innovation in biologics and long-acting medicines.